PBF Energy Beats As Windfall Cracks Turn Into Net Cash And An 18% Dividend Hike, But The Stock Has Already Retreated From Its Highs
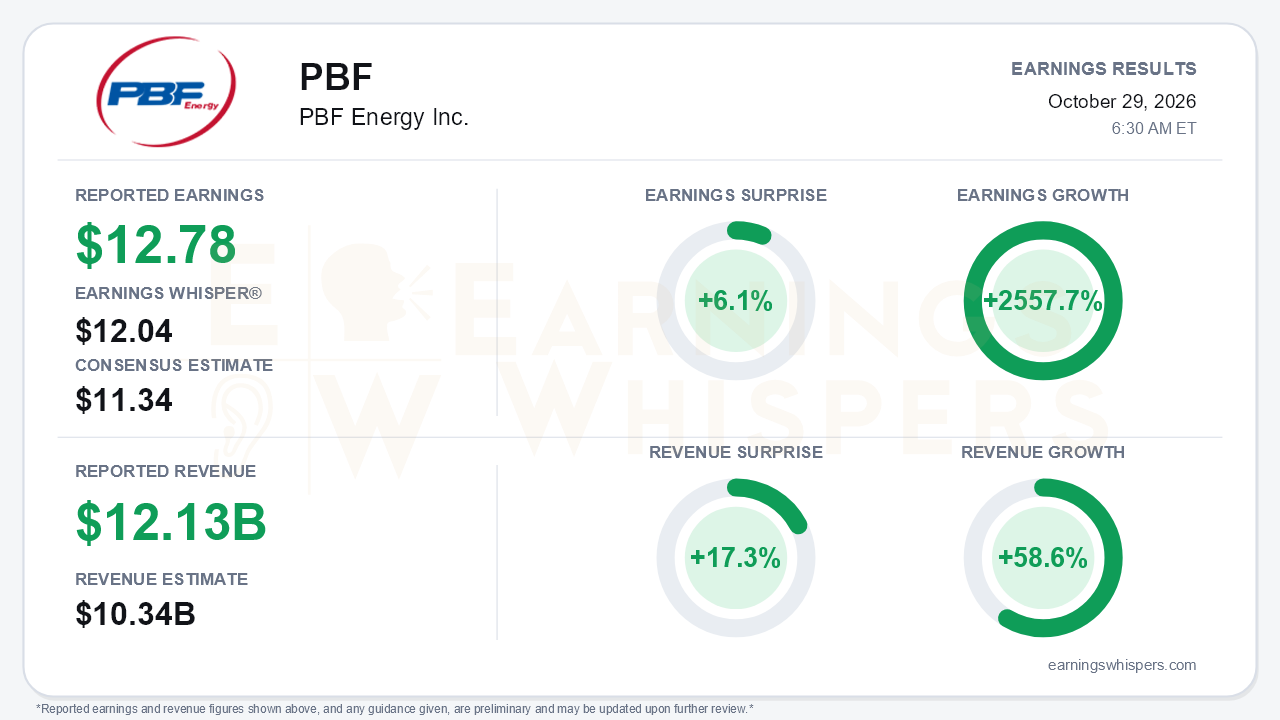
PBF Energy delivered a quarter that was less about the beat than about what the company did with the money. Adjusted earnings of $12.78 per share topped the $11.34 consensus by 6.1% and cleared the $12.04 Earnings Whisper number. Revenue of $12.133 billion beat the $10.34 billion estimate by 17.3% and rose 58.6% year over year. Earnings grew 2557.7% from the year-ago adjusted loss of $0.52 per share, a swing from red ink to the largest quarterly profit in this cycle. Third-quarter adjusted EPS alone exceeded the first half of 2026 combined, a sharp sequential acceleration. The central takeaway is that PBF converted an extraordinary margin environment into a structurally different balance sheet. The company ended the quarter with $426 million of net cash, compared with $855 million of net debt in the second quarter and $2.3 billion in the first.
The quality of this beat is better than the year-ago comparison suggests. Last year's third-quarter GAAP profit of $1.45 per share leaned on a $250 million insurance gain and a $94 million terminal sale. This quarter had neither. Special items were a modest $28.9 million after-tax charge, mostly debt-extinguishment losses from refinancing, so GAAP EPS of $12.54 sat close to the adjusted figure. The earnings still came from the market, not from self-help. The NYH 2-1-1 crack averaged $64.77 versus $25.82 a year earlier, and gross refining margin reached $34.56 per barrel versus $9.00. Cost discipline was uneven. Systemwide refining opex rose to $7.80 per barrel from $7.35, with Chalmette and the East Coast notably higher. G&A climbed to $127.4 million from $74.0 million, and the effective RIN basket more than doubled to $14.36.
Operationally, the story is restoration plus mix. Martinez is fully back, lifting West Coast throughput to 293,100 barrels per day from 234,000. West Coast opex fell to $10.41 per barrel from $12.81, and the region posted the system's best margin at $38.64 per barrel. Heavy crude rose to 30% of the slate from 25%, as Brent-Maya differentials widened to $19.16 from $8.15. Management flagged that differential, driven by freight and Latin American heavy barrels, as a fourth-quarter tailwind. St. Bernard Renewables also contributed more: PBF's share of equity income reached $62 million, up from $27.5 million in the second quarter, and the joint venture paid its first dividend of roughly $20 million.
The forward catalysts lean constructive:
- Fourth-quarter throughput guidance of 925,000 to 985,000 barrels per day carries no scheduled turnarounds.
- A final Martinez insurance payment, which management expects to be similar in size to prior ones of about $250 million, should arrive before year-end.
- After the post-quarter redemption of the $800 million 9.875% notes, management expects 2027 interest expense to fall by at least $130 million.
- Smaller organic projects add incremental upside: the Torrance hydrogen plant acquisition, the Chalmette jet project scaling to 20,000 barrels per day for under $20 million, and a Paulsboro gasoline yield project.
Bears still have legitimate ammunition. Deferring the Chalmette and Toledo turnarounds flatters 2026 but loads downtime and spending into 2027, for which capex guidance has not been given. RBI opex savings are running $8 million to $10 million short of target. Fourth-quarter cash flow faces a cash tax payment. Management itself acknowledged that a Middle East normalization could compress cracks. Buybacks remain deprioritized.
The market setup is more complicated than the surprise implies. Investor sentiment was negative heading into the report and weakened further, from -0.06 to -0.17, a meaningful but not dramatic deterioration. Shares entering the release at $73.28 were up 12.7% from the $65.00 open after the July report and sat 38% above the 200-day moving average. However, they were also 20.7% below the October 14 52-week high of $92.46, meaning investors had already given back a large slice of the crack-driven run before PBF reported. Trend readings are mixed, with momentum positive while the AVWAP trend is negative, consistent with a stock that rallied hard and then cooled.
The bottom line is that PBF reported a clean, high-quality beat in a windfall environment. More importantly, it used that windfall to erase net debt, slash future interest costs and raise the dividend 18%, changes that will outlast the current crack spreads. The skepticism in sentiment and the pullback from October's high reflect fair doubt about how long $60-plus cracks persist and how heavy 2027 turnarounds will be. Still, PBF now enters any downturn from a far stronger financial position than it held at the start of the year.
Read our earnings preview for PBF Energy Inc.: https://www.earningswhispers.com/article/PBF/21116
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 6 hours | |
| 6 hours | |
| Oct-21 | |
| Oct-14 | |
| Oct-07 | |
| Oct-02 | |
| Sep-28 | |
| Sep-28 | |
| Sep-24 | |
| Sep-23 | |
| Sep-14 | |
| Sep-14 | |
| Sep-11 | |
| Sep-03 |
