Patrick Industries Faces RV Slump Test As Marine Strength Must Carry The Quarter
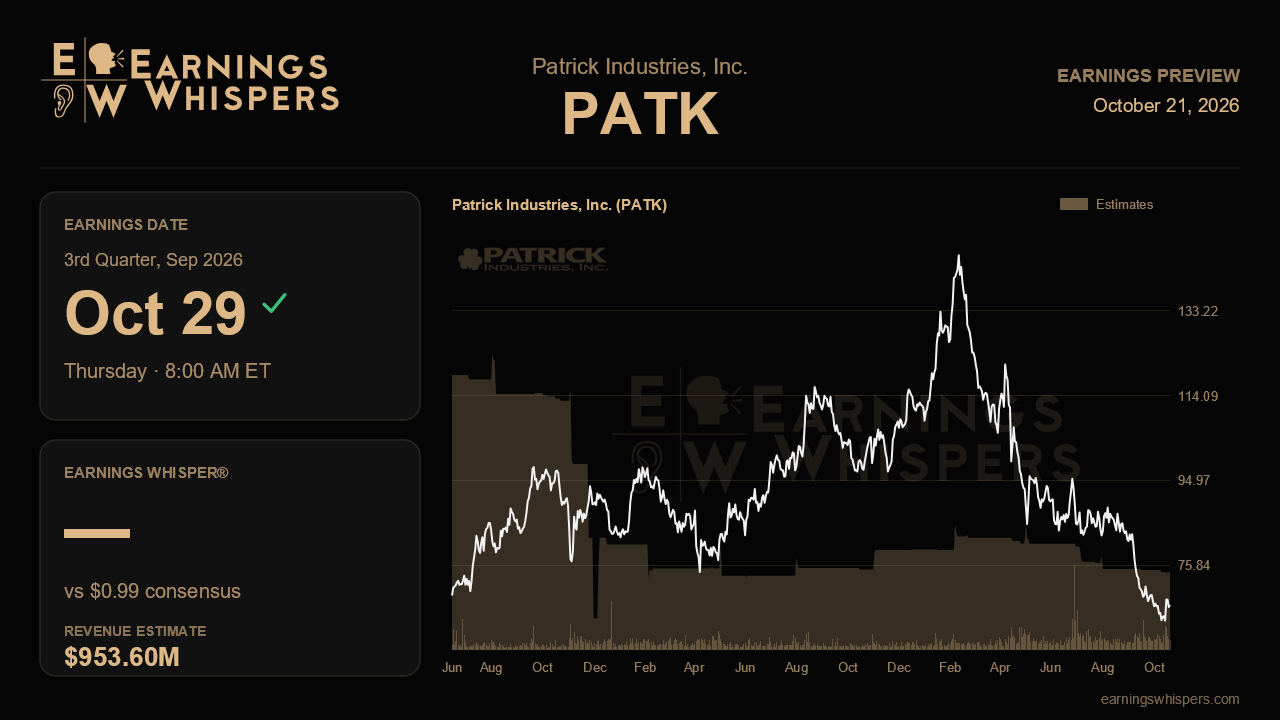
Patrick Industries heads into its third-quarter report with a stock that has already absorbed a great deal of bad news and a forecast that still asks a lot of its healthier businesses. Management has cut its 2026 RV outlook twice, trimmed its margin and cash flow targets, and warned that second-half RV run rates would fall 20% to 25% from first-half levels. Yet the Street is looking for only a modest year-over-year decline. That gap between a sharply weaker core market and a fairly gentle consensus is the central tension heading into the October 29 release, due before the opening bell.
Analysts expect earnings of $0.99 per share on revenue of about $953.6 million. That compares with $1.01 and $975.6 million a year ago, implying declines of roughly 2% on both lines. This is contraction, but mild contraction, and it is a big step down from the $1.29 and $1.04 billion posted last quarter. The sequential drop fits management's warning about a softer second half. The modest year-over-year slip, however, assumes that marine and power sports keep doing much of the heavy lifting while RV revenue, which fell 15% to $407 million in the second quarter, keeps shrinking.
That makes the diversified segments the first thing to check. Marine revenue rose 22% last quarter to $191 million against flat industry powerboat shipments, and content per unit climbed 22% on a trailing basis, helped by electrical solutions acquisitions. Power sports grew 28% for a second straight quarter on rising attachment rates for cab enclosures and HVAC on utility side-by-sides. If both segments hold growth near those levels, the consensus looks reachable. If either cools meaningfully, there is little cushion, because RV content gains, still up 7% per unit last quarter, can only partially offset a wholesale shipment forecast now sitting at 285,000 to 300,000 units.
Margins are the second swing factor. Management lowered its full-year adjusted operating margin outlook from expansion of 70 to 90 basis points earlier in the cycle to flat versus 2025, with a possible extra 20 basis point hit from volume-based affordability programs offered to RV customers. Add incoming duties on imported luan plywood and the third quarter is when those costs should begin showing up. A margin that holds near last year's level would validate the revised framework; another step below the 7.5% posted in the second quarter would suggest the guide is still drifting lower. Cash flow deserves equal attention. Operating cash flow guidance was cut to $320 million to $350 million and free cash flow to about $250 million, partly because composite inventory has been slow to turn. Net leverage rose to 3.0 times, and buybacks are now restricted under the pending all-stock merger with LCI Industries, so working capital release is the main lever for improving the balance sheet before that deal closes.
The market has priced in considerable pain. Shares have fallen about 25% since the last report while the S&P 500 gained 4.5%, and at $66.86 the stock sits near the bottom of its post-earnings range of $63 to $89.65 and far below its 200-day average of roughly $97. Sentiment remains bearish but has eased noticeably from the prior quarter, which hints that some investors see the reset as largely done. That raises the stakes for a fourth consecutive guidance cut, which would undercut the idea that expectations have finally found a floor.
The real question is whether the October report shows guidance stabilizing. If management holds its RV unit, margin and cash flow targets while marine and power sports keep compounding, the softening narrative could begin to shift toward one of a trough with a merger synergy story on top, including the roughly $150 million in run-rate savings targeted with Lippert. Another round of reductions would instead suggest the RV downturn is still outrunning Patrick's diversification.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 5 hours | |
| Oct-15 | |
| Sep-16 | |
| Aug-26 | |
| Aug-14 | |
| Aug-14 | |
| Aug-03 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-17 | |
| Jul-16 | |
| Jul-16 | |
| Jul-09 |
