Patrick Industries Beats On Margins As Powersports Accelerates, But Cash Flow Cuts And A Clouded LCI Deal Keep The Setup Fragile
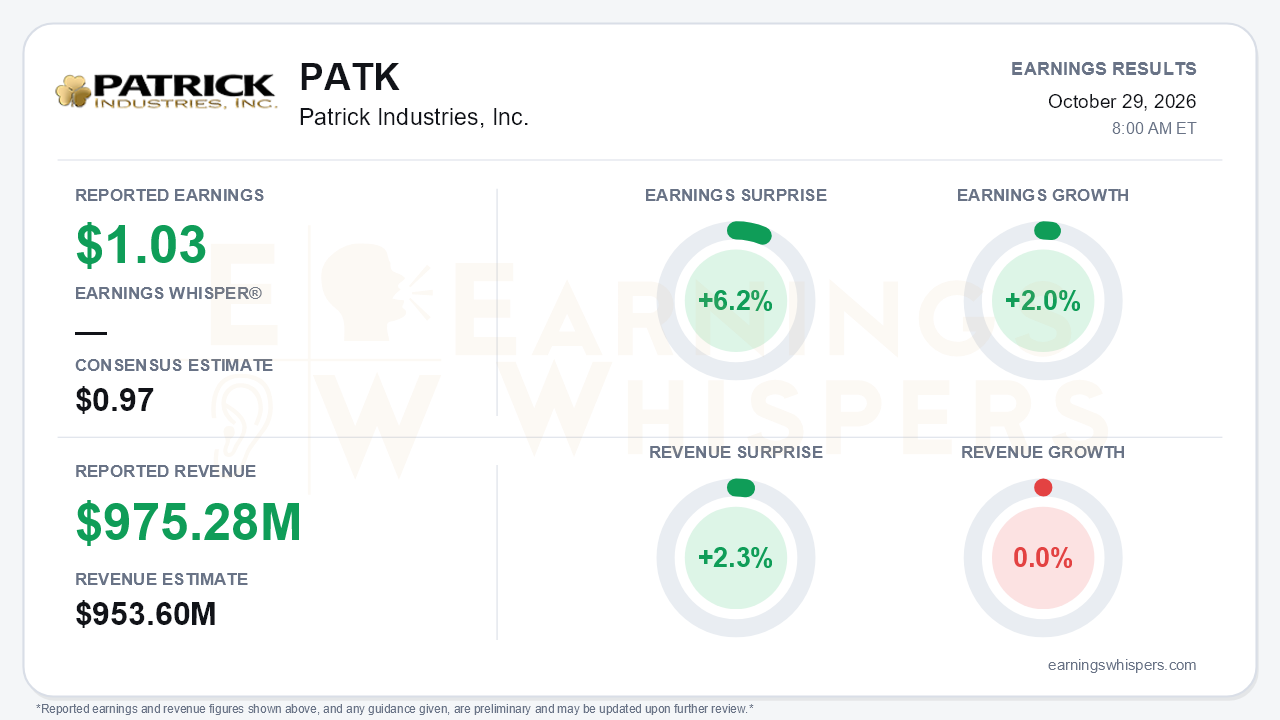
Patrick Industries delivered a cleaner third quarter than its battered share price implied. Adjusted EPS of $1.03 beat the $0.97 consensus by 6.2% and rose 2.0% from a year ago. Revenue of $975.28 million topped the $953.6 million estimate by 2.3% and was flat year over year, a respectable result given that RV, still Patrick's largest end market, fell 15%. The central tension is that a stabilizing margin story arrived alongside another cut to cash flow guidance, further erosion in RV content, and fresh uncertainty over the company's own transformational merger.
The quality of the beat deserves scrutiny. Adjusted net income actually slipped to $33.6 million from $35.3 million. The EPS gain came from a lower diluted share count, as dilution from convertible notes and warrants fell to roughly $0.03 per share from $0.07. GAAP results looked far worse. Diluted EPS fell to $0.64 from $1.01, and operating margin compressed to 5.1% from 6.8%, largely because of $14.7 million in merger-related costs and $2.0 million in restructuring charges. Beneath those charges, operations held up well. Gross margin improved to roughly 23.6% from 22.6%. Adjusted EBITDA rose 3% to $116 million, and adjusted EBITDA margin expanded 40 basis points to 11.9%, reversing an 80-basis-point decline in the second quarter. Warehouse and delivery expense climbed about 10% on flat sales, an early sign of the fuel and freight pressure management expects to persist into 2027.
The segment mix tells a story of diversification doing its job, with uneven quality across the portfolio.
- **Powersports:** Revenue grew 30% to $128 million, accelerating from 28% in the prior two quarters. Management raised its 2026 outlook to low-double-digit content growth and high-single-digit unit growth, up from low single digits for both.
- **Housing:** Growth improved to 4% from 2% in the second quarter and a 6% decline in the first.
- **Marine:** Revenue still rose 14%, but that was down from 22% in the second quarter, and quarterly content-per-unit growth slowed sharply to 5% from 22%.
- **RV:** Quarterly content per unit turned negative at -3%, after +2%, +6% and +13% in the preceding three quarters. That is a meaningful reversal for a business whose pitch has long rested on content gains outrunning unit cycles. The 2026 RV wholesale range was trimmed to 285,000-295,000 units, far below the 315,000-330,000 assumed in the first quarter.
The forward picture is split. Bulls can point to the following:
- An initial 2027 outlook calling for adjusted operating margin up 30-50 basis points despite flat RV and marine shipments.
- A "Patrick 2.0" efficiency program, including restructuring targeting about $10 million in annualized savings, with charges coming in the fourth quarter.
- The launch of Patrick Printing Solutions.
- Marine engineered electrical and tower systems shipping for model-year 2027.
- An M&A pipeline that management says is picking up.
Bears have legitimate ammunition as well:
- Full-year free cash flow guidance has been cut every quarter this year, from about $300 million to $230-250 million. Operating cash flow guidance fell to $300-330 million from $380-400 million at the start of the year.
- Third-quarter operating cash flow improved to $78 million from $9 million, but merger costs and working capital are weighing on the full year.
- An outside party has made an all-cash offer for LCI Industries, putting the Patrick-LCI all-stock combination in question just weeks before the November 18 shareholder vote.
- Management flagged consumer confidence at its weakest since 2014 and the risk that OEMs diversify suppliers in response to the merger.
- Merger covenants have halted buybacks.
Investor sentiment heading into the report remained negative but improved noticeably, rising from -0.24 after the July report to -0.05. That suggests expectations had already been reset lower. The price action explains why. Shares fell 22% from the $89.65 open after the July report to $69.93. They now sit 27.3% below the 200-day moving average of $96.14 and only 11% above the $63.00 52-week low set on October 12. The Earnings Whispers trend signals remain mostly negative, with price, momentum and AVWAP readings all pointing down, while sequential growth is neutral.
The market setup is more complicated than the surprise implies. The operating quarter argues that Patrick's margin structure is holding through a deep RV downturn. The stock, however, is increasingly trading on merger uncertainty and cash generation, and neither improved on this report.
The bottom line is that Patrick posted a credible stabilization quarter, with adjusted margins expanding, powersports accelerating and a 2027 margin target that assumes no cyclical help. The beat leaned on a lower share count, though, and the persistent cash flow cuts, negative RV content trend and rival bid for LCI keep the investment case hostage to factors beyond quarterly execution.
Read our earnings preview for Patrick Industries, Inc.: https://www.earningswhispers.com/article/PATK/21115
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-21 | |
| Oct-15 | |
| Sep-16 | |
| Aug-26 | |
| Aug-14 | |
| Aug-14 | |
| Aug-03 |
