PHINIA Must Prove Second-Quarter Strength Survives Without Tariff Refunds As Shares Slump
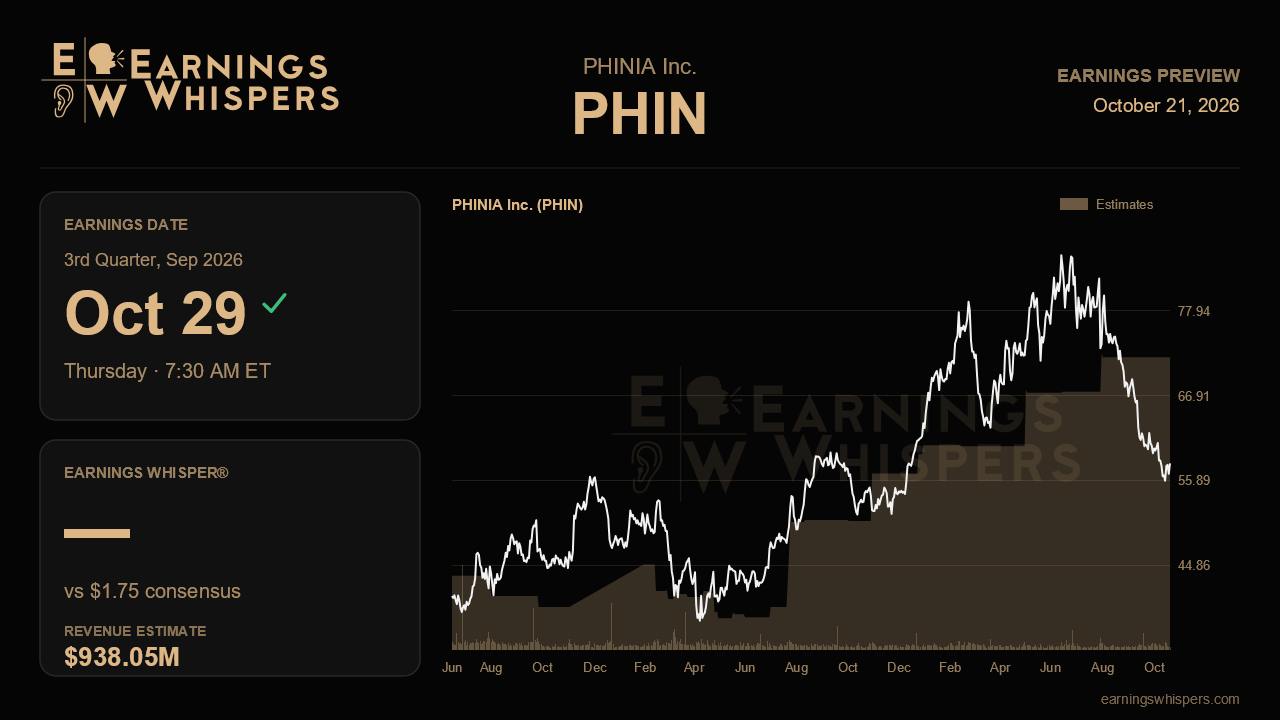
PHINIA heads into its third-quarter report with an odd mismatch between what management said three months ago and what the market has done since. The company sounded more confident on its last call, raising its free cash flow outlook and announcing an accretive acquisition. Yet the stock has fallen about 25% since then while the S&P 500 gained roughly 4.5%. The October 29 release, due before the open, now has to answer a pointed question: was the second quarter's improvement real operating momentum, or was it mostly a one-time tariff gift?
The Street is looking for adjusted earnings of $1.75 a share on revenue of about $938 million. That would mean roughly 10% earnings growth on only about 3% revenue growth from a year ago, so the forecast depends on margins and a shrinking share count rather than strong volume. The sequential bar is the bigger issue. Last quarter's $1.53 benefited from about $11 million of EBITDA from tariff refunds, which management said will not recur. Reaching $1.75 without that help means underlying profit has to improve meaningfully, through the supply-chain savings management cited as an offset, firmer commercial vehicle demand, and continued buybacks.
Guidance makes the setup harder to read. Management narrowed its 2026 revenue range to $3.57 billion to $3.67 billion and kept the midpoint unchanged, but consensus sits near $3.69 billion, slightly above the top of that range. At the same time, the company trimmed the top of its adjusted EBITDA outlook to $485 million to $515 million and lowered its margin band to 13.5% to 14.1%. First-half EBITDA came to about $245 million, which implies a back half of roughly $240 million to $270 million. A third quarter near or above the second quarter's $130 million, without the refund, would strongly support the view that earnings power is building. A result closer to $120 million would suggest the trimmed range was a warning, not just caution.
Several threads from the last call deserve close attention. Management described commercial vehicle order boards as firming after earlier hints of recovery, and that should start to appear in revenue mix and in the tone of commentary. China's light-vehicle market, which was down by mid-teens, emerged last quarter as a new weak spot, and any sign that the decline is spreading or deepening would undercut the revenue range. Incentive compensation added about $9 million of cost in the second quarter. Because that expense is tied partly to the share price, the recent selloff could ease it, but investors should look for confirmation. Cash generation also matters. Adjusted free cash flow of $74 million last quarter, helped by unusually light capital spending, supported the higher $210 million to $250 million target. Another strong quarter would protect the buyback, which management said Stoba will not slow.
The Stoba deal, expected to close in the fourth quarter, will not affect these results. Updates on timing, integration plans and the safeguards around Stoba's work for competitors could still influence how investors value the company's push into aerospace, defense and semiconductor equipment.
Sentiment has turned sharply. Bearish readings have climbed from near neutral before the last report to a clear majority now. The stock trades around $58, well below its 200-day moving average near $72 and close to its post-earnings low of $55, a long way from the $87 peak of the prior quarter. That points to lowered expectations, but it is not a sign of a turnaround. The core question is whether PHINIA can show margins holding up once the tariff windfall disappears. If it can, the recent selloff looks overdone. If it cannot, the trimmed EBITDA outlook may prove to have been the more honest signal from last quarter.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-19 | |
| Oct-13 | |
| Oct-01 | |
| Sep-29 | |
| Sep-28 | |
| Sep-01 | |
| Aug-31 | |
| Aug-13 | |
| Aug-06 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-28 |
