PHINIA Beats On Record Profitability And Raises Guidance, But A Stalled Top Line And Buyback-Driven EPS Leave A Battered Stock Seeking Proof
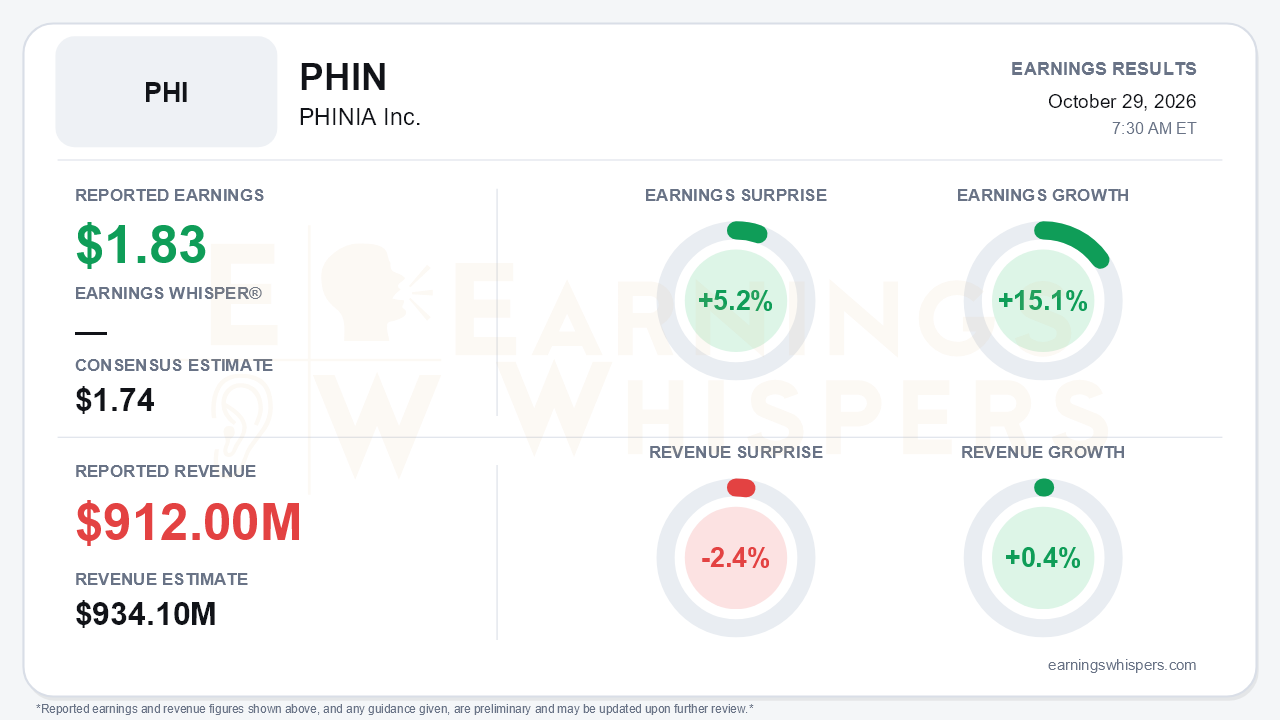
PHINIA delivered the kind of profit quarter its shares have not been trading on. Adjusted EPS of $1.83 beat the $1.74 consensus by 5.2% and grew 15.1% year over year, both records. Adjusted EBITDA reached a record $135 million at a 14.8% margin, and management raised and tightened full-year guidance for the second straight quarter. The top line tells a different story. Revenue of $912 million missed the $934.1 million consensus by 2.4% and grew just 0.4%, down from 5.6% in the second quarter and 10.3% in the first. Expanding profitability on top of a stalling sales base is the central tension, and it explains why a beat-and-raise arrives with the stock pinned near its lows.
The quality of the beat deserves scrutiny. Adjusted net earnings rose about 8%, from $63 million to $68 million. Adjusted EPS rose almost twice as fast because diluted shares fell to 37.1 million from 39.6 million, so the $65 million of third-quarter buybacks and earlier repurchases did a meaningful share of the work. Tariffs also cut both ways. The release says tariff refunds owed to customers reduced reported sales, yet it also credits the "favorable timing of tariff recovery mechanisms" as the main reason the margin rose 20 basis points. GAAP EPS of $1.80 versus $0.33 looks dramatic but mostly reflects $53 million of spin-off-related separation costs in the year-ago quarter, not an operating step change. A $3 million tax provision on $70 million of pretax income also flattered GAAP results.
The call made a more credible case for the underlying business than the headline revenue suggests. Management sized the tariff-refund drag at $21 million, of which about $7 million was one-time. The release states that core sales grew $21 million excluding tariff volatility. Profitability is clearly improving:
- Adjusted EBITDA margin has climbed from 13.0% in the fourth quarter of 2025 to 13.1%, 13.8% and now 14.8%.
- Power Systems margin improved to 12.1%, from 11.0% in the second quarter and 9.3% in the first.
- Aftermarket held at 17.1%, with segment sales up 4.2%.
Investors should note one contributor to that trajectory. R&D is stepping down from the mid-3% range of sales in the first half to the mid-2% range in the second, even though the release cited higher year-over-year R&D as a headwind. Power Systems sales fell 1.8%, and China light-vehicle and commercial-vehicle weakness, customer pricing pressure and unrecovered freight and commodity costs remain real.
The forward-looking evidence is better than the quarter itself. Revenue guidance is now $3.625 billion to $3.675 billion, and adjusted EBITDA guidance is $500 million to $520 million. Management said more than half of the EBITDA raise is organic, driven by North American and European commercial-vehicle strength and launches ramping faster than expected. The rest comes from stoba, which closed October 1 and brings roughly $80 million of revenue and $25 million of EBITDA at accretive margins. Management also expects fourth-quarter revenue to exceed the third quarter's, against normal seasonality, and said order boards "filled in" after the second quarter. Other catalysts include:
- an aerospace pipeline of 8 customers and 13 programs;
- a first methanol engine win in China;
- a CNG injector award in India;
- a lower 28-30% adjusted tax rate.
The raise was characterized as in line with estimates, however, so it validates expectations rather than resetting them.
Cash flow gives bears legitimate ammunition. Operating cash flow fell $32 million to $87 million on repatriation withholding taxes and higher receivables. Receivables rose to $902 million from $804 million at year-end. Adjusted free cash flow of $73 million was down $31 million, yet the company returned $76 million, or 104% of that figure. Short-term borrowings rose $73 million in the quarter, and net debt climbed to $657 million from $611 million. Leverage of 1.3x is comfortable, but buybacks are now partly debt-funded.
The market setup heading into the report was decidedly hostile. Investor sentiment swung from essentially neutral (-0.02) to firmly negative (-0.65), a genuinely large deterioration. Shares fell 26% from the $77.90 opening after the July report to $57.68. That leaves them 19.2% below the 200-day moving average and less than 5% above the October 14 inter-earnings low of $55, after peaking at $80.91 in early August. The Earnings Whispers trend signals lean negative on price, sequential growth and AVWAP.
The bottom line is that PHINIA's report offered more fundamental reassurance than a stock near its lows implies: record margins, a second guidance raise, accelerating program launches and an accretive acquisition. Skeptics will focus on near-flat revenue, a beat amplified by share count reduction and tariff timing, and weaker cash conversion. The fourth quarter now carries the burden of proof. A counter-seasonal revenue increase and stronger collections would go a long way toward showing that the margin story rests on more than timing.
Read our earnings preview for PHINIA Inc.: https://www.earningswhispers.com/article/PHIN/21119
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 12 hours | |
| 16 hours | |
| 16 hours | |
| Oct-21 | |
| Oct-19 | |
| Oct-13 | |
| Oct-01 | |
| Sep-29 | |
| Sep-28 | |
| Sep-01 | |
| Aug-31 | |
| Aug-13 | |
| Aug-06 | |
| Jul-31 | |
| Jul-30 |
