Teck's Q3 Test: Can Quebrada Blanca Stability Absorb A Flagged Second-Half Slowdown?
Teck Resources heads into its third-quarter report with a story that has changed dramatically in a year. The troubled ramp-up at Quebrada Blanca, once the overhang on every conversation about the stock, has given way to three straight quarters of stable output, a record 61% adjusted EBITDA margin and a balance sheet that keeps adding cash. The question now is whether that momentum can hold through a second half that management openly warned would be softer, and the Street's numbers suggest analysts have taken that warning seriously.
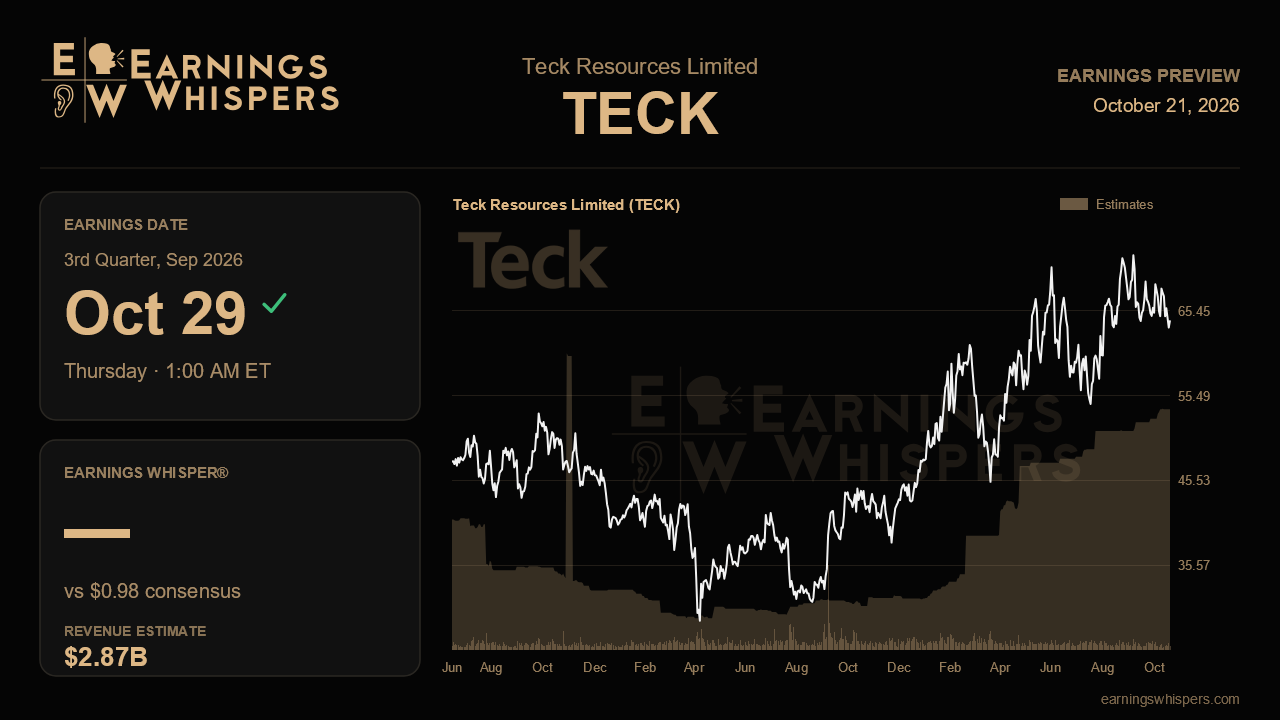
Consensus calls for earnings of $0.98 per share on revenue of $2.87 billion. Against the year-ago quarter, that is a big step up: EPS would rise about 78% from $0.55, and revenue would climb nearly 17%. Sequentially, however, the picture is more nuanced. Revenue is expected to rise from $2.60 billion last quarter, yet EPS is forecast to fall well short of the $1.35 Teck posted in the second quarter. In other words, analysts expect the top line to keep growing while profitability retreats from its peak. That gap is the heart of this report, and it implies the record margin is not expected to repeat.
Management laid the groundwork for exactly that. On the last call, it reaffirmed annual guidance rather than raising it and declined to steer investors toward the top of its ranges despite two strong quarters. The reasons were specific: planned mill downtime at Highland Valley Copper to tie in the mine life extension, lower grades there, softer output from Antamina, and the seasonal diesel deliveries at Red Dog that tend to inflate zinc unit costs in the third quarter. Energy costs were already shaving roughly seven cents a pound off copper costs, a headwind that byproduct credits from molybdenum, silver and zinc had more than offset. Whether that offset survives lower volumes is a key swing factor. Copper net cash unit costs fell to $1.64 a pound last quarter from $2.02; holding anywhere near that level while Highland Valley runs below capacity would be a strong signal of underlying cost discipline.
Quebrada Blanca remains the linchpin. A fourth consecutive quarter of steady throughput with no tailings-related downtime would cement the turnaround thesis and lend credibility to management's more offensive talk of accelerating Rock Bench 6 and de-bottlenecking toward 165,000 to 185,000 tonnes per day. Any update on whether the roughly $100 million Rock Bench 6 acceleration is moving ahead would show whether that confidence is translating into capital decisions. Trail, which swung from a marginal contributor to more than $200 million in quarterly gross profit, also deserves attention given the new federal critical-metals agreement and fresh feed deals. Finally, the Anglo American merger was waiting only on Chinese regulatory approval, with no remedies requested, so clarity on timing and closing mechanics could matter as much as the quarter itself.
The market has leaned in. Shares are up about 9% since the last report, beating the S&P 500 by roughly five percentage points, and sentiment has flipped from mildly bearish before the prior report to moderately bullish now. At $64.33, the stock sits comfortably above its 200-day moving average near $60 but about 11% below its post-earnings high of $72.56, leaving room in both directions rather than signaling a stretched setup.
Ultimately, this report is less about whether Teck can match its record quarter and more about whether the slowdown proves as contained as management promised. A dip in margins driven by flagged, temporary factors, paired with continued stability at Quebrada Blanca and resilient cash generation, would keep the improvement narrative intact. Signs that cost pressure or operational hiccups are spreading beyond the known second-half issues would challenge it.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 5 hours | |
| 7 hours | |
| Oct-19 | |
| Oct-07 | |
| Oct-06 | |
| Oct-02 | |
| Sep-21 | |
| Sep-21 | |
| Sep-16 | |
| Sep-14 | |
| Sep-11 | |
| Sep-11 | |
| Sep-10 | |
| Sep-10 | |
| Sep-08 |
