Teck Resources Beats On Record Copper Prices And Cuts Cost Guidance, But Weather, A Strike And Merger Approval Risk Cloud The Quarter
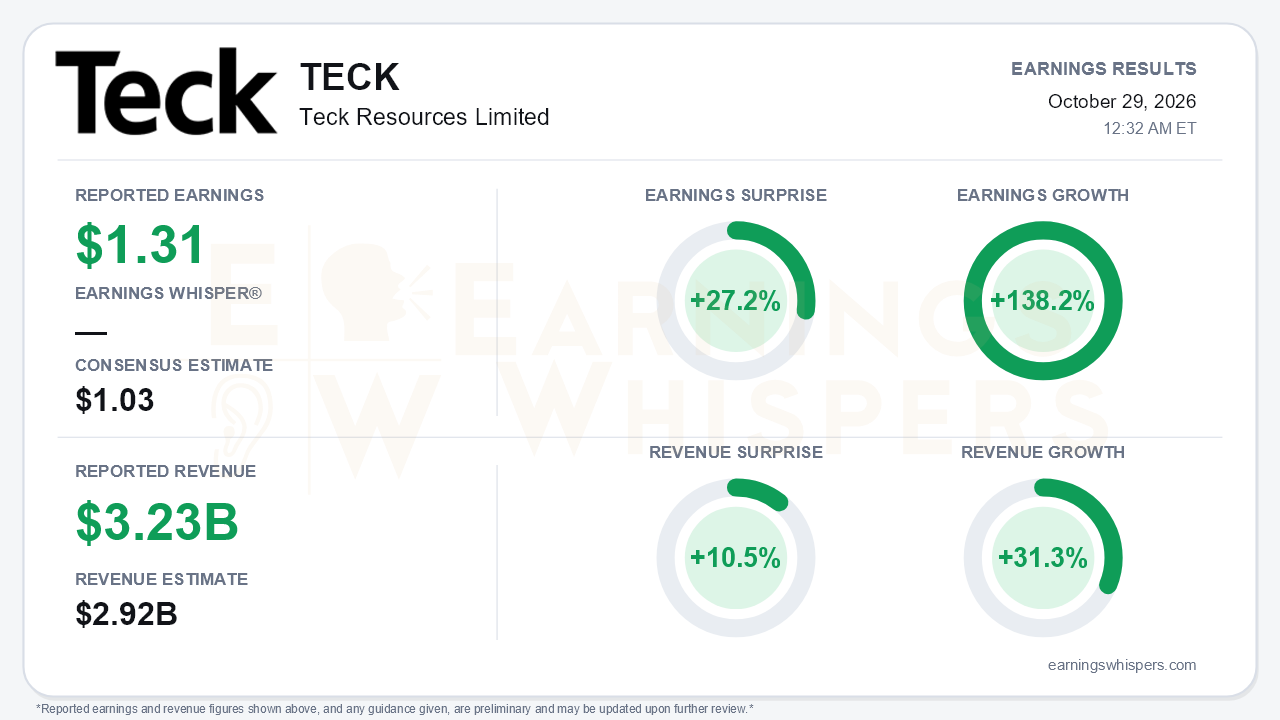
Teck Resources delivered a large third-quarter beat. Earnings Whispers reported adjusted earnings of $1.31 per share on revenue of $3.228 billion. That topped the $1.03 consensus by 27.2% and the $2.92 billion revenue estimate by 10.5%. Earnings grew 138.2% year over year and revenue rose 31.3%. The company reports in Canadian dollars, so its own figures differ: adjusted EPS was C$1.88, versus C$0.76 a year ago, and revenue was C$4.517 billion. The normalized figures above are on a US-dollar basis. The driver was not mysterious. Copper averaged a record US$6.40 per pound, and adjusted EBITDA nearly doubled to C$2.3 billion. The central tension is that prices did the heavy lifting in a quarter when operations stumbled. Production fell sequentially, margins compressed from Q2's peak, and new labor and regulatory risks emerged after the quarter closed.
The quality of the beat holds up better than the GAAP headline suggests, but the distinction matters. Reported EPS of C$3.24 was inflated by C$1.36 per share from an C$888 million pre-tax impairment reversal at Trail, plus C$0.26 of favorable tax items. The adjusted C$1.88 is the cleaner figure. Even on that basis, the cash generation was real:
- Operating cash flow reached C$1.6 billion.
- Net cash climbed to C$1.9 billion, up from C$1.2 billion in Q2 and C$150 million at the end of 2025.
- Liquidity rose to C$10.9 billion.
Copper net cash unit costs fell to US$1.77 per pound from US$2.09, helped by lower smelter charges. The Trail reversal is non-cash, but it signals that management now embeds higher long-term zinc price assumptions.
Beneath the headline, the operating trend weakened. August snowstorms and power outages at Quebrada Blanca cut throughput and blocked access to higher-grade ore. The impact showed up across the mine's metrics:
- QB copper output fell to 47,200 tonnes from 55,800 in Q2.
- Recoveries slipped to 81.1% and grades to 0.55%.
- QB unit costs jumped to US$2.48 per pound from US$1.83 sequentially.
Total copper production of roughly 116,000 tonnes was up 11% from a year ago but well below the 140,000 tonnes produced in Q1. The call analysis put the adjusted EBITDA margin at 51%, down from a record 61% in Q2. EBITDA itself rose only modestly from C$2.2 billion. Carmen de Andacollo endured an extended weather shutdown and is now guided to the low end of its range. Zinc unit costs rose sharply year over year on Red Dog grade decline, and diesel inflation is pushing capitalized stripping to the high end of guidance. Sustaining capital is heading to the top half of its range because Rock Bench 6 was not in the original budget.
The call nonetheless preserved a credible forward story. This was the first explicit cost-guidance cut of the year:
- Copper net cash unit costs lowered to US$1.80-2.00 per pound from US$1.85-2.20.
- Zinc net cash unit costs roughly halved to US$0.30-0.40.
- Highland Valley, Red Dog and Trail guided toward the high end of their production ranges.
The cost improvement owes much to by-product pricing rather than purely operational gains. At QB, management held 2026 guidance of 200,000-235,000 tonnes. It pointed to a fourth straight quarter without tailings-related downtime, no further planned shutdowns this year, and Rock Bench 6 plus permanent tailings infrastructure targeted for Q1 2027. Opening additional mining faces should reduce QB's vulnerability to weather. Still, management did not steer QB toward either end of its range, which leaves little room for another disruption.
Bears have legitimate ammunition on the risk side:
- **Highland Valley strike:** The strike began October 24 and the operation is running at reduced capacity, which sits awkwardly with the high-end production guidance.
- **Merger approval:** China's SAMR approval is the last outstanding condition for the Anglo American merger, and media reports have raised questions about concentrate offtake requests. Management declined to characterize those reports, and its tone was more guarded than in prior quarters.
- **Antamina:** A fatality occurred at the joint venture on October 27.
On the positive side, the future leadership team has been named. The deal still targets close within the original 12-18 month window and carries roughly US$800 million in expected synergies. San Nicolás also secured its key environmental permit.
Investor sentiment moved from slightly negative (-0.06) to slightly positive (+0.01) heading into the report. That is a modest improvement, not a decisive shift in expectations. The stock has gained 7.0% since the open after the July report and sits 4.5% above its 200-day moving average. However, shares are 13.1% below the 52-week high of $72.56 set on September 8, which means much of the record-copper rally was given back as the QB disruptions surfaced. The Earnings Whispers trend signals are mixed. Momentum is positive, but sequential growth and AVWAP are negative, consistent with a business still growing year over year while losing some quarter-to-quarter traction.
The bottom line is that Teck converted record copper prices into a sizable beat, a stronger balance sheet and lower cost guidance. Its operational footing, however, looks less secure than it did after Q2. Sustaining the setup depends on QB recovering through the Q1 2027 tailings milestones, a short Highland Valley strike, and a clean SAMR approval. Without those, the company leans entirely on copper prices staying near records.
Read our earnings preview for Teck Resources Limited: https://www.earningswhispers.com/article/TECK/21135
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-26 | |
| Oct-24 | |
| Oct-21 | |
| Oct-21 | |
| Oct-19 | |
| Oct-07 | |
| Oct-06 | |
| Oct-02 | |
| Sep-21 | |
| Sep-21 | |
| Sep-16 |
