WEC's Third-Quarter Report Hinges On A Promised Capital Plan Raise And Oracle Clarity
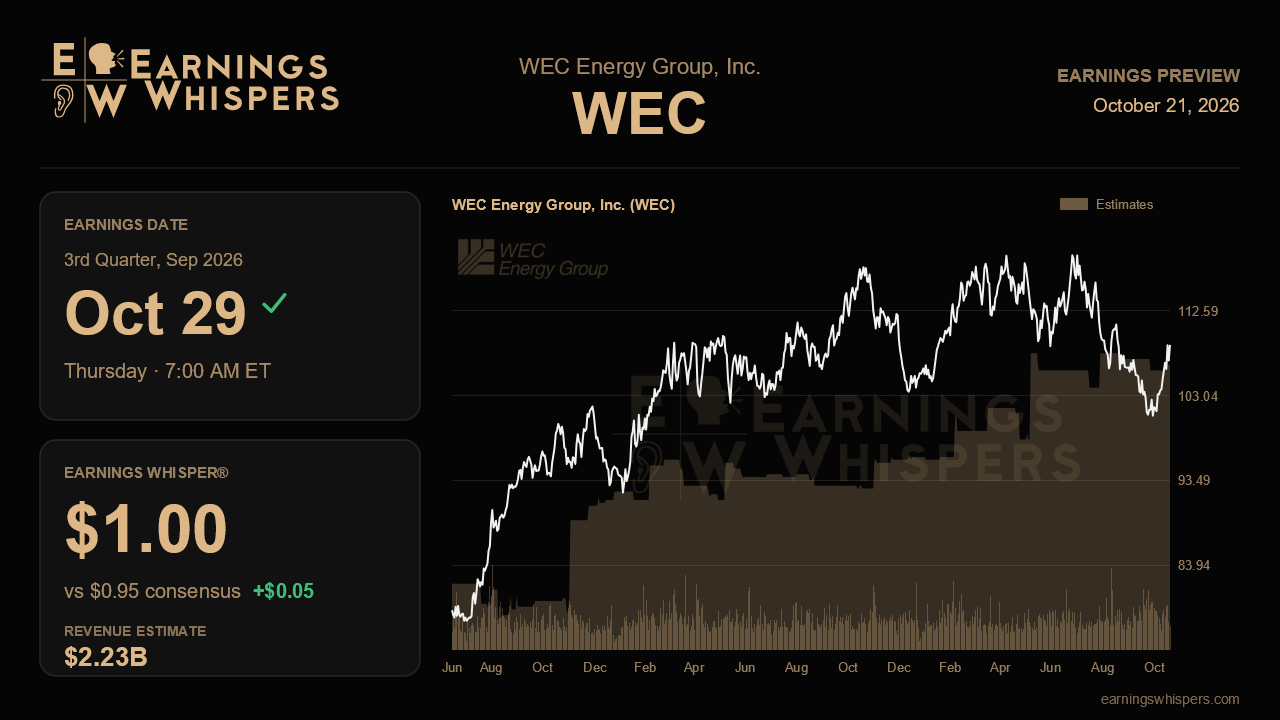
WEC Energy Group heads into its third-quarter report with an unusual split between what management promised and what the stock has done. On the last call, executives all but pre-announced a bigger capital plan, pointing to data-center load that pushed weather-normal retail electric sales up 4.2% and a pipeline of new 400 to 500 megawatt customers. Since then, the shares have slipped 4.8% while the S&P 500 gained 3.9%, a gap of nearly nine points. The October 29 release, due before the open, is the moment management has to show that the growth story is bigger than the worries weighing on the stock.
The near-term numbers set a fairly demanding bar for a regulated utility. Analysts expect earnings of $0.95 per share, up about 14.5% from $0.83 a year ago, on revenue of roughly $2.23 billion, a 6% increase. That earnings pace is well above the company's long-term 7% to 8% growth target, which reflects the steady drumbeat of rate-base expansion, including AFUDC equity on construction work, that added $0.13 to second-quarter results. The whisper number sits at $1.00, a nickel above consensus. For a utility, that is not trivial; it suggests the more engaged crowd expects summer weather and rate-base contributions to push results comfortably past the published estimate. Full-year 2026 guidance of $5.51 to $5.61 has been reaffirmed three straight times without a raise, so a strong third quarter could reopen the question of whether management finally nudges toward the upper end.
The bigger story, though, is the capital plan. The five-year budget climbed from $36.5 billion to $37.5 billion over the past year, and management flagged further upside from transmission, a potential Point Beach nuclear replacement at roughly $2 billion to $2.5 billion per gigawatt, possible combined-cycle gas, and the simple addition of another plan year. A meaningful step up would validate the claim that earnings growth accelerates into the upper half of the 7% to 8% range from 2028. A modest bump, or a delay, would undercut the improving tone that defined the last call. Any named new very large customer would add weight, since management suggested an announcement could come by year-end.
Oracle is the swing factor on the risk side. The company is pursuing credit support for the Port Washington project while Oracle challenges the very large customer collateral requirement in court. Management downplayed the threat, and the written tariff order with its A- credit standard drew praise from all three rating agencies. Investors should want concrete progress on securing Oracle's financial commitment, along with continued construction updates at the Vantage site, where a first facility could arrive in late 2027. Political noise, including a gubernatorial candidate's talk of a data center moratorium, is harder to resolve in one quarter but will color how the market values that pipeline.
Beneath the data-center headlines, the core business is softer. Management cut its 2026 outlook for weather-normal sales excluding the mine and large customers to roughly flat, down from about 1.5% growth, and trimmed Illinois PIPE spending because of labor shortages. Evidence that core demand has stabilized and that Illinois crews are ramping would ease concerns that the base is eroding while attention focuses on hyperscalers.
Sentiment has cooled, with bearish readings deepening to 15.2% from 9.4% heading into the last report. The stock trades at $108.75, below its 200-day average of $111.25 and in the lower half of its post-earnings range between $99.80 and $114.44. That leaves room for relief if the plan delivers. Ultimately, the report turns on whether WEC can convert its data-center momentum into a larger, credible capital plan while showing the Oracle dispute is a negotiation rather than a fracture.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Sep-02 | |
| Aug-10 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-22 | |
| Jul-16 | |
| Jul-16 |
