WEC Energy Beats On Weather, But The $47.5 Billion Data-Center Plan Is The Real Story As Core Demand Stalls
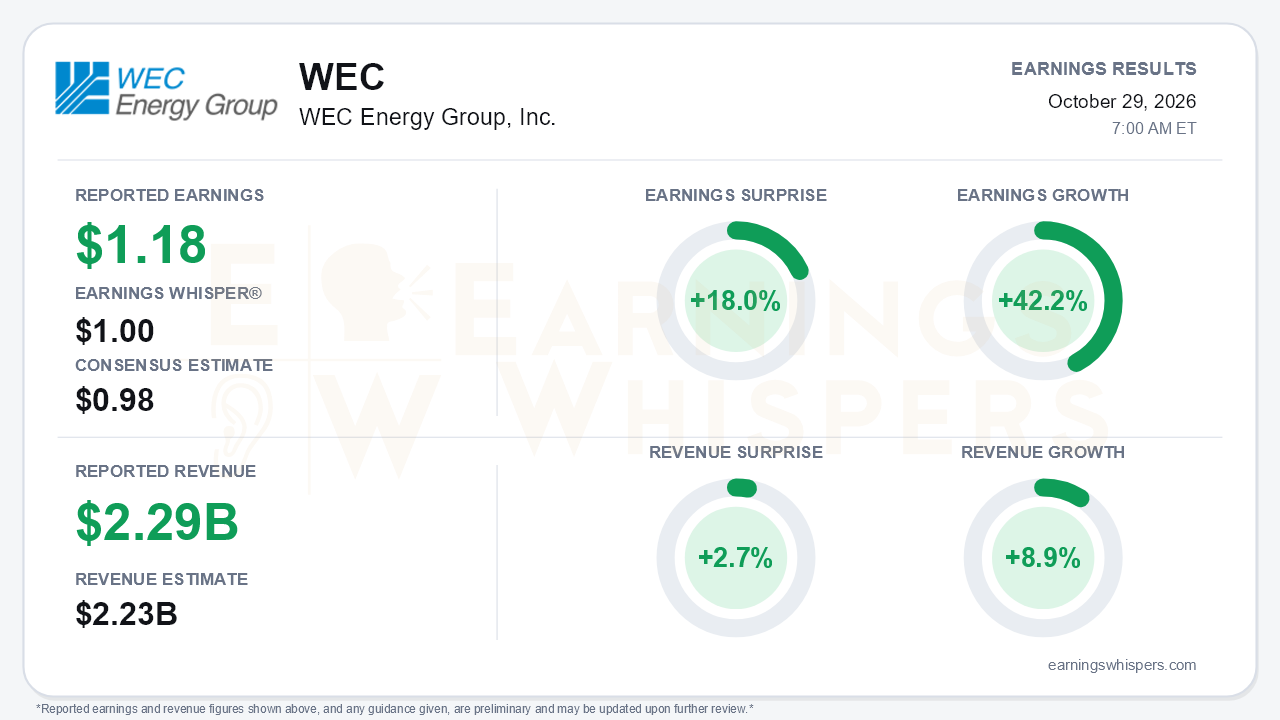
WEC Energy Group delivered a third-quarter beat that was decisive in size but secondary in importance. Earnings of $1.18 per share topped the $0.98 consensus by 18.0% and cleared the $1.00 Earnings Whisper number. Earnings grew 42.2% from 83 cents a year ago and finished well above the $0.92-$0.98 range management had guided on the second-quarter call. Revenue of $2.291 billion rose 8.9% and beat estimates by 2.7%. The more consequential development came on the call. WEC added $10 billion to its five-year capital plan and raised its long-term EPS growth target to 7-9+%. It said it can do both without raising its equity issuance plans. That is the central takeaway: the quarter was flattered by weather, but the forward earnings algorithm genuinely improved.
The quality of the beat deserves scrutiny. Management credited warmer-than-normal weather, capital plan execution, and efficiency. The call made clear that roughly $0.08 of the upside came from favorable weather and operations-and-maintenance timing, partly stock-compensation timing that should not recur. Below the operating line, other income nearly doubled to $49.5 million from $23.8 million. Nine-month AFUDC-equity, a non-cash credit tied to construction spending, more than doubled to $139.5 million. That is a byproduct of the build-out rather than cash earnings, and it is happening while interest expense climbs. Full-year guidance moved to $5.60-$5.64 from $5.51-$5.61, but that raise was in line with what the Street expected. In other words, the beat was largely absorbed rather than extended.
The headline also masks softer core demand. Reported retail electric deliveries, excluding the iron ore mine and very large customers, rose 3.3%, helped by a 5.1% jump in residential use. On a weather-normal basis, that same customer base grew just 0.4%, down from 1.2% in the second quarter. Management now expects full-year weather-normal sales from this base to be flat, versus roughly 1.5% growth it anticipated earlier in the year. It also trimmed its Wisconsin gas sales outlook to 0.5-0.8% from 0.7-1%. Excluding the hyperscale load, WEC is essentially a no-growth utility right now.
That hyperscale load is where the investment case has shifted. The new 2027-2031 plan totals $47.5 billion, up from $37.5 billion. That supports a 13.4% asset growth rate and forecast demand growth of 4.9 GW, up 1 GW. Projected load in the Microsoft I-94 region rose to 3.2 GW from 2.6 GW, with potential of 4.5-5 GW. An unnamed roughly 400 MW customer delivered the 'third customer' management had hinted at earlier. The Oracle credit-support issue that clouded the prior call is resolved. Oracle has met its tariff security obligations and will subscribe to energy from Point Beach, the nuclear plant whose roughly 1,000 MW supply contract with NextEra would be extended 20 years, pending approval. The financing structure matters as much as the capex. Very large customers will pay cash returns on construction work in progress. That keeps planned equity near $5.5 billion and cuts the equity content of incremental spending to about 40% from 50%. Management said it expects to reach the upper end of the 9% target, with the 'plus' likely in 2028-29. It also lowered its dividend payout target to 60-70%.
Bears have legitimate ammunition. Assets tied to very large customers are projected to reach about 29% of the total by 2031, up from roughly 15% by 2030 in the prior plan. That is a meaningful concentration bet on a handful of technology tenants. The American Transmission Company line serving the Vantage/Oracle site had to be refiled and now faces a compressed 12-15 month build. In Illinois, an administrative law judge recommended a 9.48% return on equity and a 50% equity ratio for Peoples Gas and North Shore Gas, and pipe-replacement work is lagging because of labor constraints. The plan also assumes debt costs in the upper-6% range, and equity needs are concentrated in the early years.
The market entered the report unconvinced. Shares closed at $110.50 the day before the release, down 3.3% from the open after the July report. They sat about 0.8% below the 200-day moving average. The stock hit a 52-week low of $99.80 on Oct. 1 and has since rallied 10.7%, though it remains below the $114.44 inter-earnings high. Investor sentiment stayed modestly negative and slipped slightly, from -0.094 to -0.115, so expectations were not elevated going in.
The bottom line is that WEC's third-quarter beat was real but low-quality, propped up by weather, expense timing, and non-cash construction income. Meanwhile, organic demand outside the data-center pipeline has stalled. What changed is the long-term setup. A larger capex plan, faster EPS growth targets, resolved Oracle risk, and flat equity needs give the stock a more credible growth story than its recent trading reflects. Execution on transmission timelines and the growing reliance on a few hyperscale customers now matter more than any single quarter's weather.
Read our earnings preview for WEC Energy Group, Inc.: https://www.earningswhispers.com/article/WEC/21150
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 3 hours | |
| 12 hours | |
| 13 hours | |
| Oct-22 | |
| Oct-21 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Sep-02 | |
| Aug-10 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 |
