Wesco's Record Backlog Meets A Cautious Street As Cash Flow Becomes The Real Test
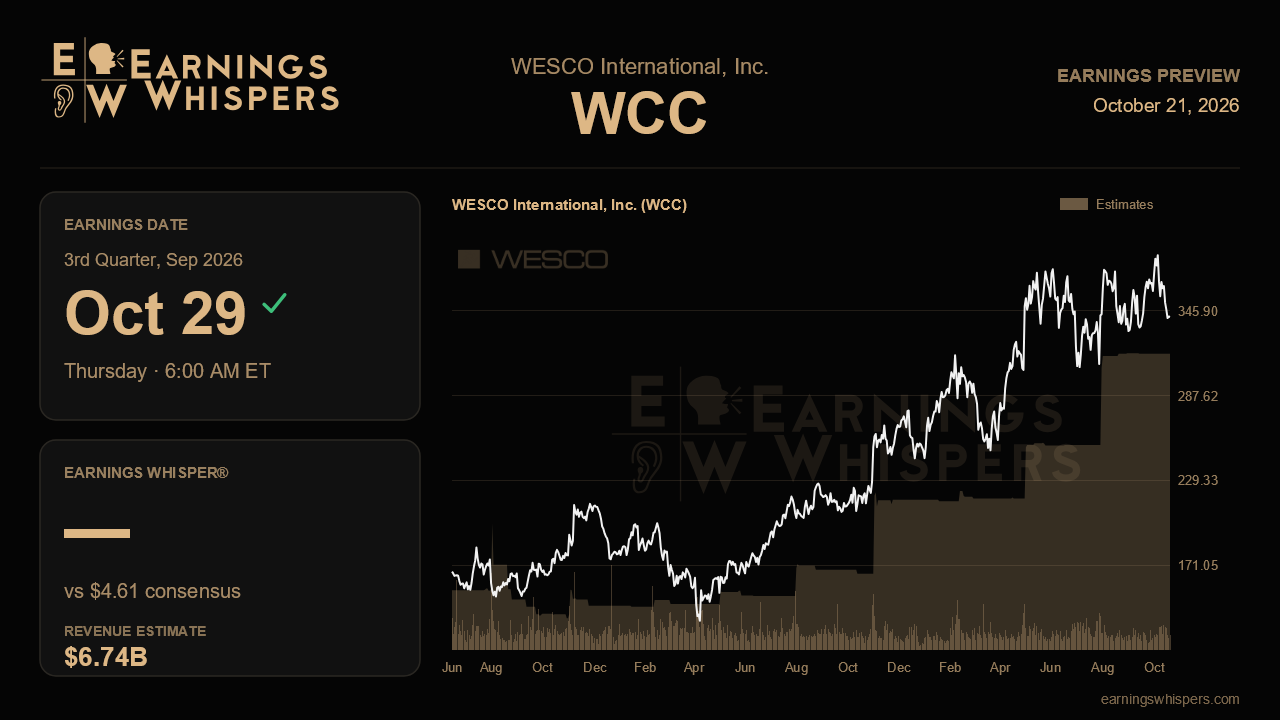
Wesco International enters its third-quarter report with the kind of operating story most distributors would envy: four straight quarters of double-digit sales growth, a record backlog, and a full-year outlook raised twice. Yet the stock has barely moved since the company last reported, and the mood around it has cooled. That gap between a company that keeps raising the bar and a market that seems reluctant to pay for it is what makes the October 29 release, due before the open, more interesting than a routine checkpoint.
Wall Street is looking for earnings of $4.61 a share on revenue of about $6.74 billion. That would mean roughly 17.6% EPS growth and 8.7% revenue growth from a year ago, but only a sliver of improvement over the second quarter's $4.57 and $6.67 billion. The revenue estimate looks notably restrained. Sales rose 13% last quarter, management said preliminary July sales per workday were running up around the mid-teens, and full-year guidance now calls for 10% to 12% reported growth. A consensus implying high-single-digit growth suggests analysts are either building in caution for August and September or simply have not caught up. If Wesco delivers anything close to the pace it described in July, the top line has room to clear the bar comfortably.
Earnings are a slightly different matter. Management warned that third-quarter EBITDA margin would slip modestly from the second quarter because of project mix, which is a natural consequence of large data center and infrastructure jobs that carry lower gross margins than day-to-day product sales. That guidance helps explain why the EPS estimate barely rises sequentially. The question is whether the margin dip is as mild as promised. Last quarter, Communications and Security Solutions posted its first double-digit EBITDA margin ever at 10.2%, Electrical and Electronic Solutions reached 9.2% on a record gross margin, and Utility and Broadband Solutions climbed back to 10%. Holding most of those gains while absorbing heavier project mix would validate the idea that the margin improvement is structural rather than a one-quarter peak. A sharper slide, or continued pressure from public power competition in the utility business, would challenge it.
Beyond the headline numbers, several threads from the last call deserve follow-through. Data center sales reached roughly $1.5 billion last quarter, and management lifted its full-year data center growth outlook to above 30%. Equally important was the claim that growth outside data centers had broadened to mid-single digits. Evidence that the non-data-center business is still expanding would ease concerns that Wesco is a single-theme story. Backlog, which jumped about 60% overall, should ideally hold near record levels and begin converting into sales. Early updates on the multi-year hyperscaler grid services award, which management described as margin accretive, and on the integration of the Newark Engineering cooling acquisition would show whether those new catalysts are moving from announcement to revenue.
The softest spot remains cash. Management cut the low end of its free cash flow range to $300 million to $600 million after second-quarter free cash flow came in at just $32 million, with working capital absorbing about 20% of sales. Investors will want proof that the new receivables and inventory initiatives are gaining traction. Sentiment has slipped from 52.5% bullish to 36.1%, still positive but noticeably less enthusiastic, and the stock's 1.7% gain trails the S&P 500 by nearly three points. At about $342, shares sit above their 200-day average but in the lower portion of their post-earnings range of roughly $328 to $389.
That combination sets up a clear test. Wesco has largely proven that demand is strong and broadening. What it now needs to show is that faster growth can translate into cash rather than simply more inventory and receivables. Steady margins, an intact or raised outlook and visible working capital improvement would keep the narrative firmly on track.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-13 | |
| Oct-09 | |
| Oct-08 | |
| Oct-07 | |
| Sep-29 | |
| Sep-18 | |
| Sep-11 | |
| Aug-27 | |
| Aug-26 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 |
