Wesco Crushes Estimates And Raises Again As Backlog Surges 80%, But Cash Conversion And A Pre-Report Sentiment Slide Complicate The Setup
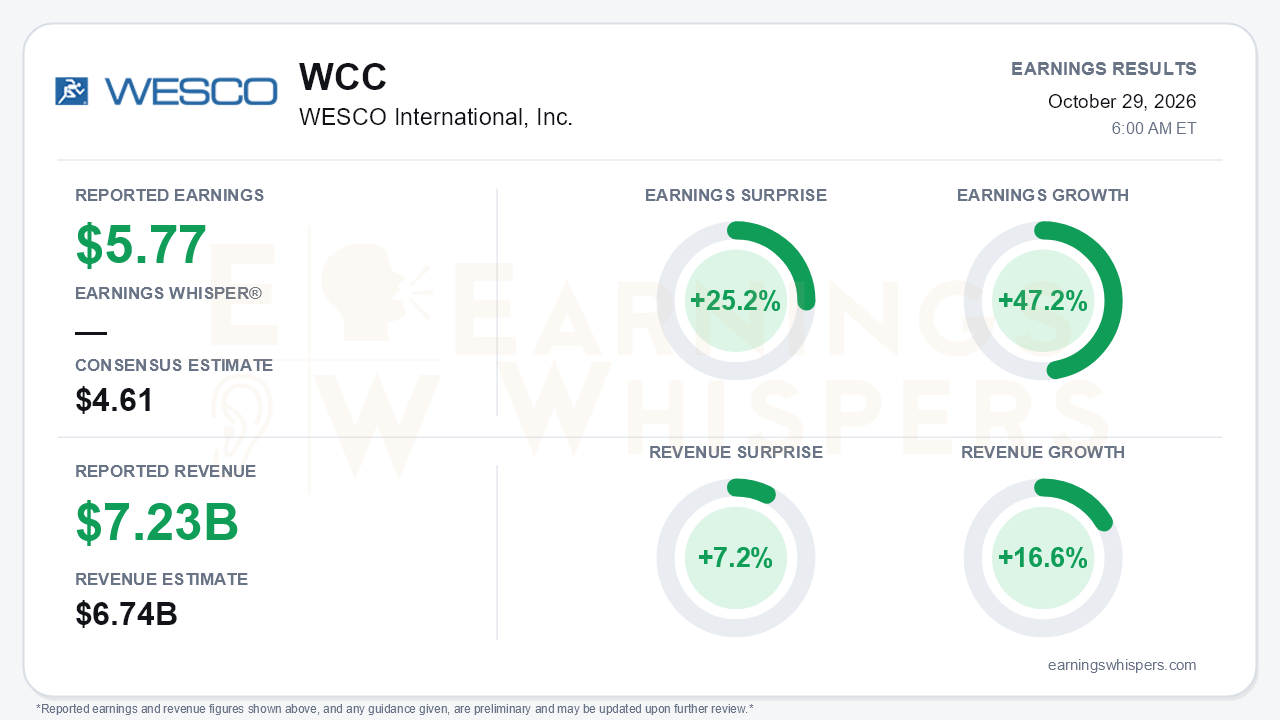
Wesco International delivered the kind of quarter that resets the debate about its growth profile. Adjusted EPS of $5.77 beat the $4.61 consensus by 25.2% and grew 47.2% year over year, while revenue of $7.226 billion topped the $6.74 billion estimate by 7.2% and rose 16.6%. More important than the size of the beat is the trajectory. Organic growth accelerated to 17% from 13% in the second quarter, 12% in the first and 9% in the fourth quarter of 2025. Management also raised full-year guidance for the third consecutive quarter, lifting adjusted EPS to $18.00-$18.50 from $16.00-$17.50. The original February range was $14.50-$16.50. That is the central takeaway: this is no longer a distributor riding a single data center theme, but one whose growth is broadening and compounding.
The quality of the beat largely holds up. Adjusted gross margin rose 40 basis points to 21.7%, and adjusted SG&A fell to 14.4% of sales from 14.7%, even with higher incentive compensation. Adjusted EBITDA margin expanded 100 basis points to 7.8%, up from 7.3% in the second quarter, so leverage is improving sequentially as well as year over year. Refinancing of the 7.25% 2028 notes cut net interest expense to $93.6 million from $99.0 million. A higher tax rate of 24.4% was a modest drag. The gap between GAAP EPS of $5.43 and the adjusted figure is driven mainly by $24.8 million of digital transformation costs, more than double the prior-year amount. Investors should track that ongoing spending, although management now says the program will deliver at least 100 basis points of EBITDA benefit.
Beneath the headline, the mix story strengthened. Data center sales jumped about 55% to $1.8 billion, accelerating from roughly 45% growth in the second quarter. Non-data center sales grew 7%, up from mid-single digits. CSS posted 21% organic growth and a record 10.7% EBITDA margin. EES accelerated to 18% growth from 11%. Backlog is the most striking figure. It was up more than 80% in total, versus 60% in the second quarter and 22% in the first, with CSS backlog up 140% and UBS backlog up 90%. Management attributes this to multi-year customer commitments. October sales per workday running up high teens suggest momentum carried into the fourth quarter. The company also described data centers as margin accretive and pointed to enterprise and private AI buildouts widening demand beyond hyperscalers.
Bears still have legitimate ammunition, and most of it centers on cash. Free cash flow was $184 million, a sharp turnaround from negative $89 million a year ago, but only 64.6% of adjusted net income. The full-year guide was held at $300-$600 million despite roughly $1 billion of added sales expectations, and that range had already been cut from $500-$800 million last quarter. Year to date, receivables consumed about $1.0 billion and inventory about $705 million. Those drains were offset largely by a $1.15 billion increase in payables and by customer advances, while rising supplier prepayments added to the working-capital load. Growth is consuming capital, and the offsets depend on payment timing. Other caveats came from the call:
- The fourth-quarter guide implies a sequential margin step-down.
- UBS grew only 6%, with broadband flat.
- Some backlog items are one to two years from becoming revenue.
- Data centers now represent about 23% of sales, a concentration analysts tied to moratorium headlines.
The market setup is more complicated than the surprise implies. Investor sentiment weakened materially into the report, falling to 0.21 from 0.53 after the prior quarter. It remains positive but is far less enthusiastic. Price action shows the same cooling. Shares set a 52-week high of $388.64 on October 6, then slid to an inter-earnings low of $312.94 on October 23, a nearly 20% drawdown in under three weeks. At $347.22 the day before the report, the stock was just 3.3% above its post-July opening price, 6.3% above its 200-day moving average and 10.7% below the recent peak. The internal trend readings are mixed, with momentum positive but AVWAP negative, which fits a stock that has churned rather than trended since the last report.
That combination matters. Fundamentals accelerated across nearly every operating line just as investor enthusiasm faded, likely reflecting anxiety about data center durability more than anything in Wesco's own results. The preliminary 2027 framework calls for mid-to-high single-digit growth with further margin expansion. That is a deceleration from 2026, but it rests on a record backlog. The November 10 data center event gives management a near-term venue to address concentration concerns directly.
The bottom line is that Wesco delivered an accelerating, broad-based quarter with a third straight guidance raise and a backlog that underwrites 2027. Cash conversion and data center concentration are the real debates, not demand. With sentiment reset sharply lower and shares well off their October high, expectations entering the print were more tempered than the results warranted.
Read our earnings preview for WESCO International, Inc.: https://www.earningswhispers.com/article/WCC/21149
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-27 | |
| Oct-23 | |
| Oct-21 | |
| Oct-13 | |
| Oct-09 | |
| Oct-08 | |
| Oct-07 | |
| Sep-29 | |
| Sep-18 | |
| Sep-11 | |
| Aug-27 | |
| Aug-26 |
