Xcel's Capital Plan Roll-Forward Puts 9%-Plus Growth Promise To Its First Real Test
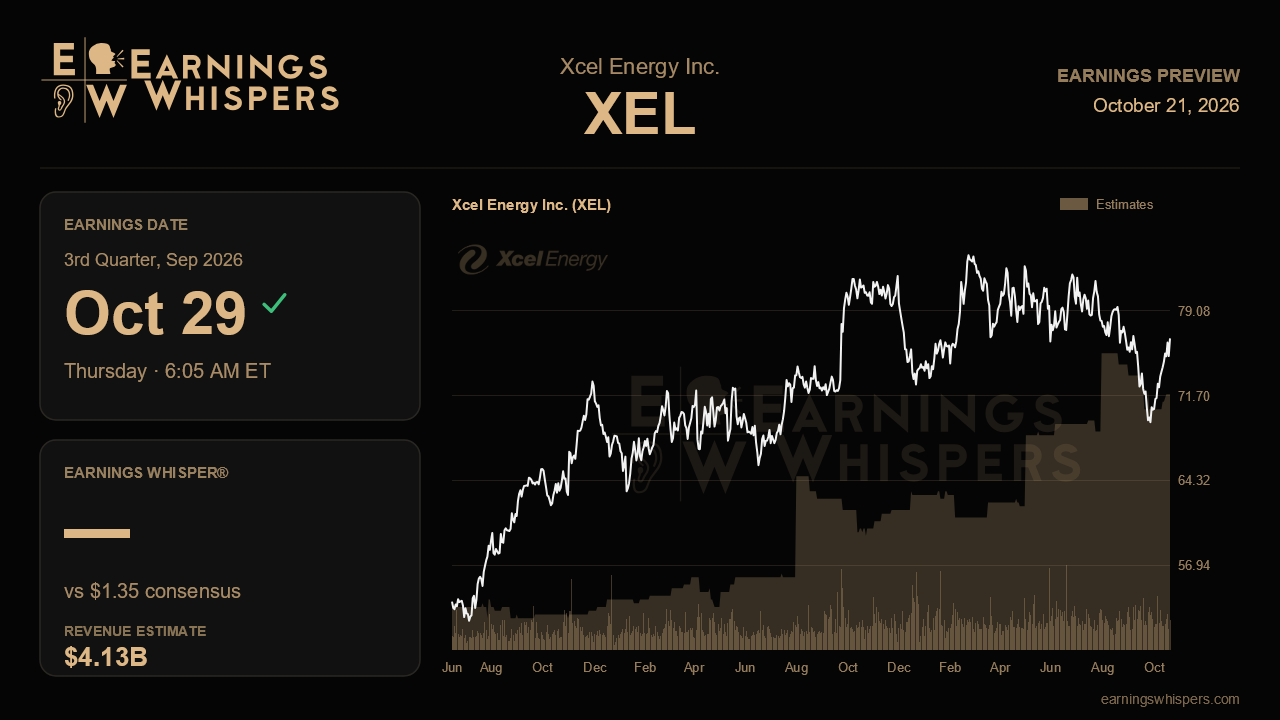
Xcel Energy's third-quarter report carries more weight than a typical utility print. Last quarter management deferred its big refresh, signaling that the capital plan would be rolled forward this fall off a new 2027 to 2031 base, with rate-base growth pushing well into double digits and the long-term earnings growth target nudged to an average of 9% or better through 2030. The stock has not waited for the details. Shares are down about 5% since the last report while the S&P 500 gained roughly 4.5%, so Xcel arrives at this release with a constructive story and a skeptical tape.
The quarter itself sets a reasonable bar. Analysts expect earnings of $1.35 a share on revenue of about $4.13 billion, up roughly 9% and 5.5%, respectively, from $1.24 and $3.92 billion a year ago. That earnings growth rate sits almost exactly on management's long-term algorithm, which is the point: a regulated utility earns credibility by delivering the promised trajectory, not by blowing past it. For the full year, the company has reaffirmed guidance of $4.04 to $4.16 a share, and the consensus of $4.11 sits in the upper half of that range. The Street is not asking for a raise, but it is assuming execution goes well, leaving little room for a weather or cost stumble in the fourth quarter.
The operating evidence that matters most falls into three buckets. First is the capital pipeline. Line-of-sight incremental investment jumped from $7 billion-plus to $10 billion-plus after Southwestern Public Service won about 2,600 megawatts, or roughly $6 billion, of company-owned generation in its competitive solicitation. The roll-forward should show how much of that converts into the formal plan and how quickly, since management acknowledged that a good portion of the spending and data-center load lands in the early 2030s. A plan heavy on back-end dollars would temper the near-term growth story. Second is demand. Weather-adjusted electric sales slowed to 2.1% year to date from 2.8% in the first quarter, yet the company held its 3% full-year target. That gap now needs to close, and a third quarter that fails to show acceleration would raise doubts about how fast large-load customers are actually showing up. Third is data-center contracting: progress toward the 6 gigawatt contracted target by the end of 2027, any read on the 4 gigawatt solicitation expected to conclude by year-end, and follow-through on large-load tariffs after Minnesota's approval and filings in Colorado and Wisconsin.
The pressure points have not gone away. Higher interest expense and equity dilution together shaved about 18 cents from second-quarter results, and a bigger capital plan only raises the stakes on financing. Management said roughly 85% of its $7 billion five-year equity need is already addressed, which helps, but any upsized plan will bring the question of fresh equity back to the table. Colorado wildfire exposure is another swing factor after a dry, low-snowpack season with more proactive power shutoffs than last year, plus a mitigation plan refile and legislation pending for 2027. Commentary that shows those costs contained and recoverable would ease a lingering discount.
Sentiment is modestly bearish and essentially unchanged from the prior quarter, which suggests investors are not leaning hard in either direction. Technically, the stock trades around $76.68, below its 200-day moving average near $78 and in the upper portion of a post-earnings range between about $69 and $81, a band notably lower and wider than the prior quarter's. A clean report with a convincing roll-forward could push shares back above that average.
Ultimately, this report hinges on whether the roll-forward turns a raised investment ceiling into a rate base and financing plan that credibly supports growth of 9% or more. If capital conversion, sales acceleration and equity needs line up, the recent underperformance looks like an opportunity. If the new plan leans on distant spending or heavier dilution, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-16 | |
| Oct-09 | |
| Oct-08 | |
| Oct-07 | |
| Oct-06 | |
| Sep-30 | |
| Sep-15 | |
| Aug-27 | |
| Aug-22 | |
| Aug-12 | |
| Aug-06 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 |
