Xerox Must Prove Its Raised Outlook Can Survive Equipment Slump And Rising Costs
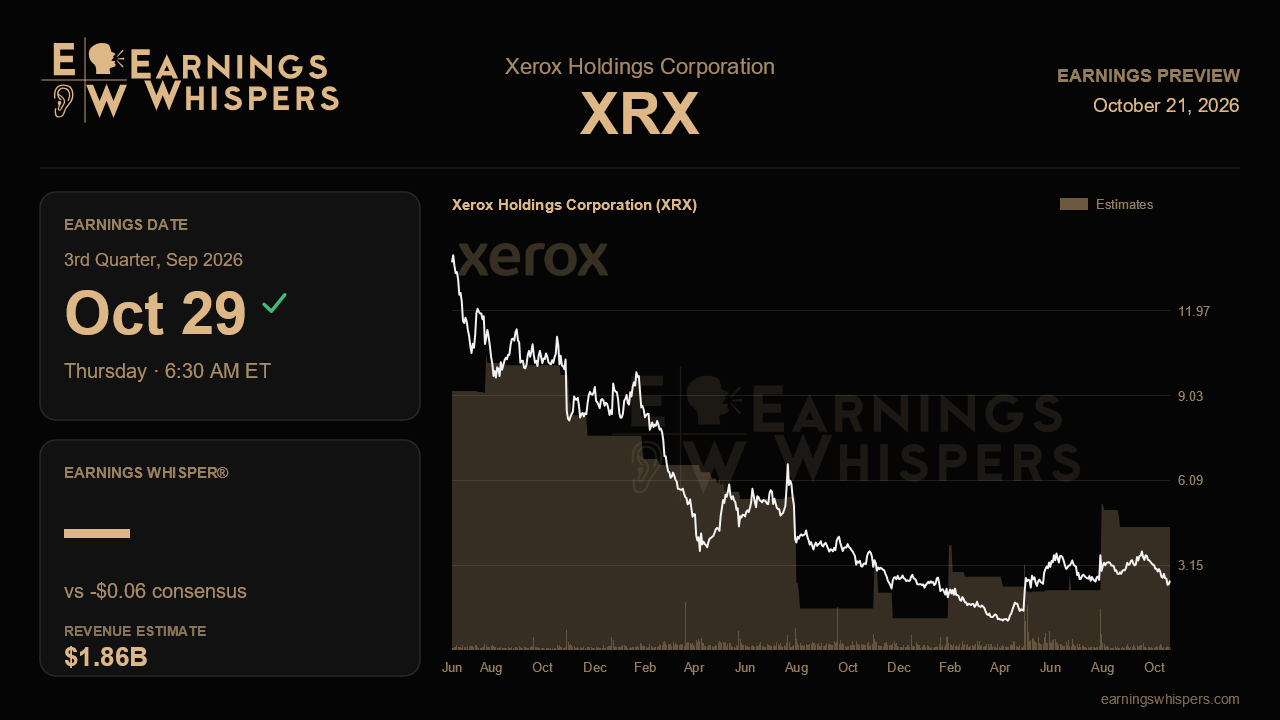
Three months ago, Xerox gave investors something they had not heard in a while: a raise across nearly every line that matters. Revenue guidance went up, the Lexmark synergy target went up, operating income guidance went up, and the year-end leverage goal got meaningfully more ambitious. The market has responded by knocking the stock down nearly 24% while the S&P 500 gained about 4.5%. That gap is the story heading into the third-quarter report on October 29, before the opening bell. Either the Street does not believe the new management team's numbers, or it believes the risks flagged on the last call are already eating into them.
The expectations bar is low on the surface. Consensus calls for a loss of 6 cents a share, against a 20-cent profit a year ago and a 36-cent result last quarter, along with revenue of roughly $1.86 billion, down about 5% from last year. Part of that EPS swing reflects how distorted the bottom line has become. A one-time tariff recovery flattered the second quarter, and the valuation allowance continues to scramble the GAAP tax rate, so headline earnings are a noisy guide to underlying progress. Revenue is the cleaner yardstick. Management now expects about $7.6 billion for the year, and consensus sits at $7.59 billion, essentially right on the guide. That leaves little cushion. A third quarter landing short of $1.86 billion would push more of the burden onto the fourth quarter and invite doubts about whether the raise was premature.
The most important operational question is equipment. Pro forma equipment revenue fell 13% last quarter, a sharp deterioration from a 2% decline in the first quarter, as mid-range A3 and OEM sales weakened. Management said plainly it is not counting on a mid-range recovery, and instead pointed to the entry segment, where demand outran supply and created a backlog it expects to convert in the back half. This report is the first real test of that claim. Evidence that the entry backlog shipped, along with early traction from the new unified Xerox-brand hardware, the self-built 9 Series platform, and production launches such as the IJP 900 and Proficio PX models, would support the idea that equipment can stabilize even without help from the mid-range. Another double-digit decline with no visible backlog benefit would undercut the revenue stabilization pillar that CEO Pastor has made central to his pitch.
IT Solutions is the second pressure point. Gross billings growth slowed to 4% from 21% in the first quarter, and segment margin slipped to 3.7% as the company rebuilt its sales force and new signings slipped. Investors should look for bookings to firm up as those hires mature; continued deceleration would suggest the business is losing momentum rather than simply digesting investment. On profitability, two straight quarters of adjusted margin expansion have leaned heavily on Lexmark synergies, now targeted at no less than $350 million with roughly half realized this year. The swing factors are oil and memory costs, both of which management flagged as moving against it. Holding margin gains despite those headwinds would be the strongest validation of the cost story.
Sentiment has soured noticeably, with bearish readings more than doubling from the prior quarter. The stock, at $2.61, trades just above its 200-day moving average and near the bottom of its post-earnings range of $2.44 to $3.78, so the market is braced for disappointment. Deleveraging matters here too: progress toward gross leverage under 5x and steady free cash flow toward the roughly $250 million target would ease balance sheet anxiety that clearly weighs on the shares.
Ultimately, this quarter hinges on whether the entry backlog and synergy gains can offset a shrinking mid-range business and rising input costs. If they can, the raised outlook looks credible and the selloff overdone. If not, the second-quarter optimism will look like a tariff-aided head fake.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-19 | |
| Oct-15 | |
| Oct-08 | |
| Sep-23 | |
| Sep-17 | |
| Sep-11 | |
| Sep-09 | |
| Sep-08 | |
| Sep-08 | |
| Sep-08 | |
| Aug-10 | |
| Aug-05 | |
| Aug-03 | |
| Jul-30 |
