Xerox Beats A Loss Estimate But Cuts Profit And Cash Guidance As Memory Costs And Mix Erase Its Print Stabilization
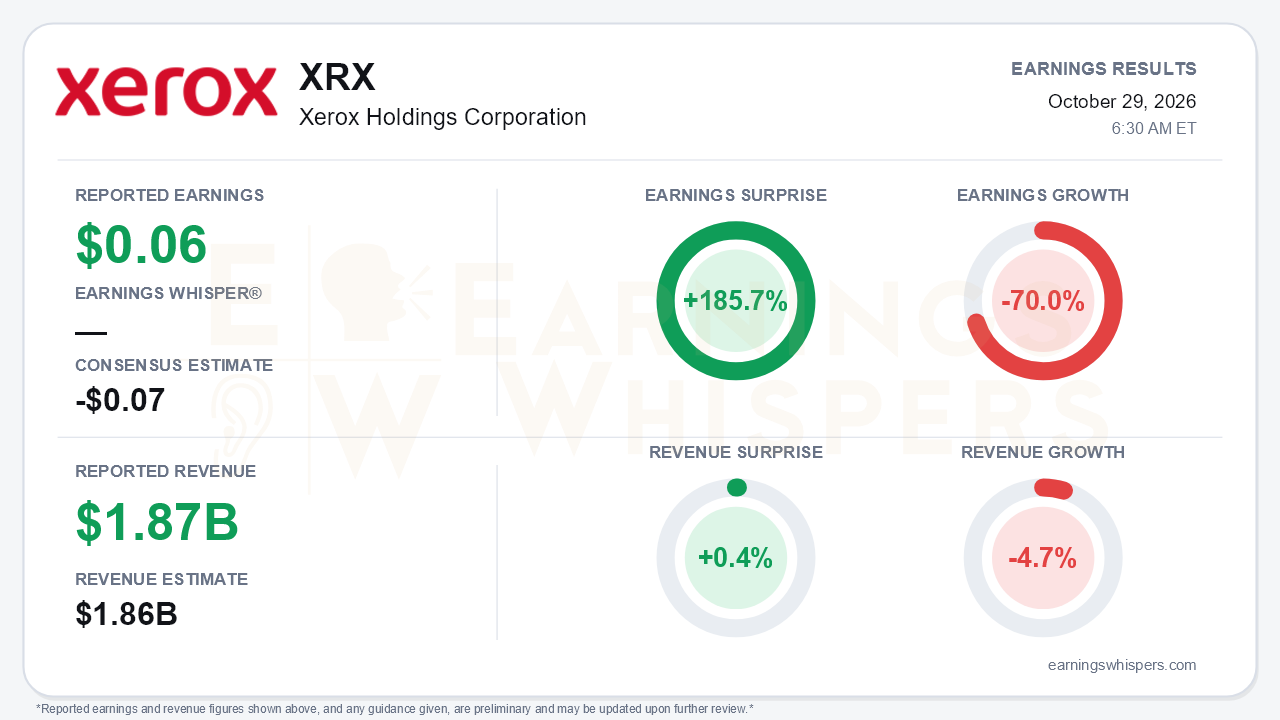
Xerox cleared a very low bar in the third quarter, and the quarter's most important information came after the headline numbers. The company reported earnings of $0.06 per share against a consensus estimate for a $0.07 loss, a 185.7% surprise. Revenue of $1.868 billion topped the $1.86 billion consensus by 0.4%. Earnings still fell 70.0% year over year and revenue declined 4.7%. The $0.06 figure matches Xerox's "normalized" adjusted EPS, which adds back tax effects tied to valuation allowances. The company's headline adjusted EPS was $0.02. Underneath, management cut full-year adjusted operating income guidance to $450-475 million from $555-605 million. It cut free cash flow guidance to $50-100 million from about $250 million and suspended both common and preferred dividends. That is the central tension: the print business is showing its first real revenue stabilization in years, yet the profit and cash outlook deteriorated sharply.
The Earnings Whispers guidance note reads "reaffirms." That is accurate only for revenue, which Xerox held at roughly $7.6 billion. On every profitability and cash metric, guidance moved lower. The quality of the beat also deserves scrutiny. Adjusted operating margin doubled to 6.6% from 3.3%, but adjusted gross margin rose only 60 basis points, to 29.5%. Most of the improvement came from a $103 million reduction in selling, administrative and general expense, driven by Lexmark synergies, lower incentive compensation and lower bad debt. On a GAAP basis, Xerox lost $7.73 per share, including a $959 million goodwill impairment in Print and Other. Management tied that charge to lower long-term projections driven by macro uncertainty and sustained memory price increases. The writedown pushed shareholders' equity to a $683 million deficit. Free cash flow was just $7 million, compared with $88 million a year ago.
The operating story is genuinely mixed rather than simply weak. Equipment revenue grew 3%, the first organic growth since Q2 2023, following pro forma declines of 13% in Q2 and 2% in Q1. Entry revenue rose 21%, high-end rose 14%, installs increased 9%, and management believes Xerox gained share. Total revenue declines moderated from a 7% pro forma drop in Q2. The growth came in the wrong place, however. Mid-range revenue fell 15%, and management said entry devices are unprofitable at the hardware level, with a margin gap of more than 30 points. Equipment gross margin collapsed to 5.0% from 26.1%. IT Solutions also deteriorated: revenue fell 17%, billings fell 14% after rising 21% in Q1, and segment margin slid to 4.4%. Management cited a slow seller ramp and tighter supplier terms linked to Xerox's credit profile.
The guidance cut has identifiable drivers, and several look likely to persist:
- **Input costs:** Memory and oil are now a roughly $60 million 2026 headwind, an issue Q2 described as only a modest risk. Memory has risen from about 2% to 10% of machine cost and is expected to reach 15% in 2027. Management expects input costs to be a larger headwind next year.
- **Tariffs:** Tariff costs reached about $90 million, above forecast.
- **Market outlook:** IDC now projects roughly 1% second-half unit growth.
- **Tariff recovery:** The reduced profit guidance still includes a $105 million tariff recovery. Without it, the outlook would look materially worse.
Management's tone shifted from Q2's message of raising guidance to "not the outlook we wanted."
Management's response includes Q1 2027 pricing actions, tighter discipline on entry placements, and roughly $100 million of additional Lexmark synergies expected in 2027. It also outlined a remote-service model, with about half of service calls now resolved remotely against a 70% target. On the product side, Xerox announced three new production platforms and a packaging-and-labels partnership with Xeikon. Leverage is the harder constraint. The year-end target slipped to about 5.6x gross and 4.7x net, from below 5x and 4x. Full-year non-financing interest expense of about $365 million is guided against adjusted operating income near $460 million. The debt exchange cut principal by $53 million and reduced the 2028 notes to $382 million. However, it swapped 5.50% unsecured paper for 10.25% secured notes plus equity, trading a lower near-term maturity wall for a higher cost of capital.
Investors were already leaning bearish before the report. Earnings Whispers sentiment weakened from -0.15 to -0.35, a meaningful move further into negative territory. Shares closed at $2.79 ahead of the release, down 18.4% from the $3.42 open after the July report. They traded 26% below the $3.78 inter-earnings high, which was also a 52-week high set the day of the last report. The stock had rebounded 14% from its October 16 low of $2.44 and sat about 10% above its 200-day moving average of $2.54. That rebound means shares entered the guidance cut and dividend suspension with some recovery already priced in.
The bottom line is that Xerox delivered evidence that its print revenue decline is stabilizing, but that progress is being undone by margin-dilutive mix, rising memory costs, a faltering IT Solutions segment and a heavy interest burden. The beat against a loss estimate and the held revenue outlook matter less than the cuts to operating income, free cash flow and the deleveraging timeline. Bears have legitimate ammunition until pricing actions and 2027 synergies show they can outrun input-cost inflation.
Read our earnings preview for Xerox Holdings Corporation: https://www.earningswhispers.com/article/XRX/21157
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 8 hours | |
| 8 hours | |
| 12 hours | |
| 12 hours | |
| Oct-21 | |
| Oct-19 | |
| Oct-15 | |
| Oct-08 | |
| Sep-23 | |
| Sep-17 | |
| Sep-11 | |
| Sep-09 | |
| Sep-08 | |
| Sep-08 |
