Alignment Healthcare's Planned Third-Quarter Dip Meets A Stock That Has Lost Nearly Half Its Value
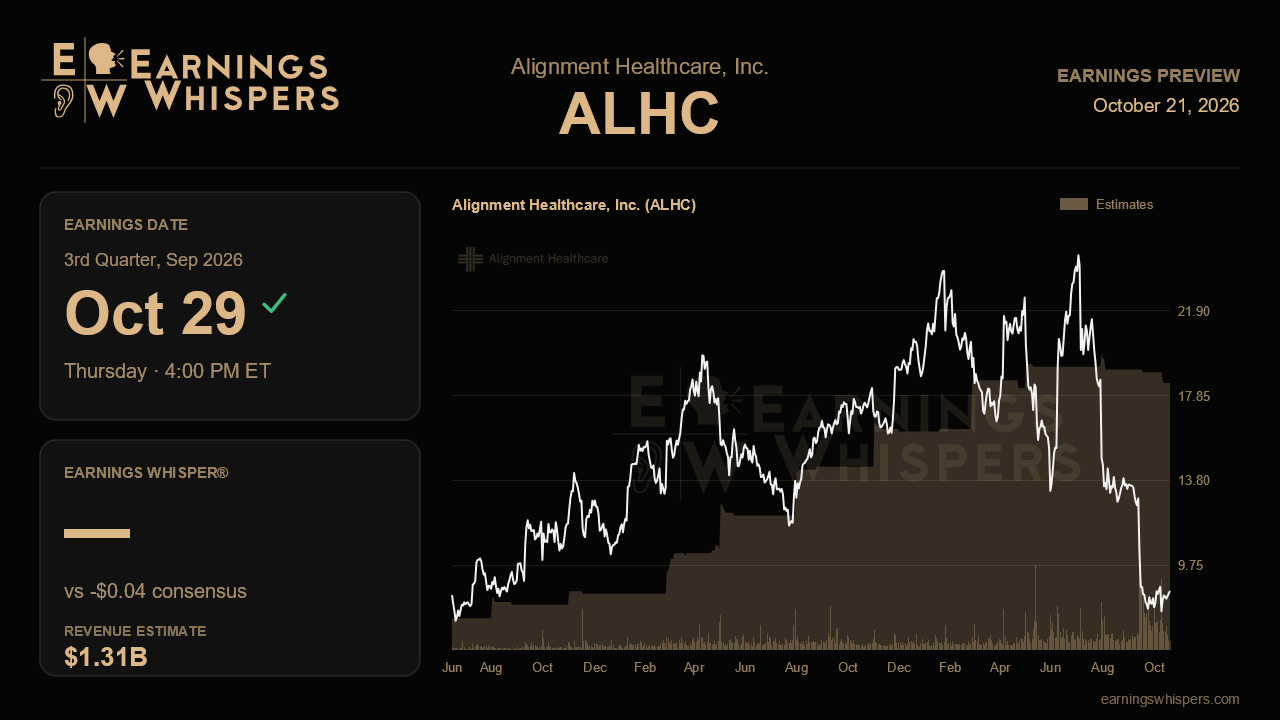
Alignment Healthcare enters its third-quarter report with an unusual setup: management told investors three months ago that this would be a soft quarter by design, and the stock has since fallen about 45% anyway. Shares have trailed the S&P 500 by more than 48 percentage points since the last report, even though that report brought a second straight guidance raise and the lowest medical benefit ratio in the company's history as a public company. The question now is less whether Alignment can beat a modest bar and more whether it can show that the planned slowdown really is planned.
Wall Street expects a loss of 4 cents a share on revenue of about $1.31 billion. That compares with a profit of 2 cents a year ago, so the earnings comparison looks ugly on paper. Revenue tells a different story, with growth of nearly 32%. The revenue consensus sits squarely at the midpoint of management's $1.30 billion to $1.32 billion quarterly range, and the full-year estimate of $5.19 billion lands just under the low end of the newly raised $5.195 billion to $5.225 billion outlook. In other words, analysts are not stretching. A top-line result in line with guidance should not surprise anyone. The more useful signal will be whether management nudges the annual range higher for a third time.
The heart of the report is profitability. On the last call, management guided third-quarter adjusted EBITDA to just $20 million to $30 million and said only about 30% of full-year EBITDA would come in the back half, down from roughly 40% last year. It pointed to three causes: deliberate double-digit-million spending on clinical hiring, its Care Anywhere program and AI tools ahead of 2027 launches; a flatter Part D cost curve; and a sicker mix of new members, with chronic and dual-eligible special needs plans making up about half of additions. A result inside that EBITDA range, alongside full-year adjusted EBITDA guidance of $145 million to $163 million held or lifted, would support the argument that margins are being reinvested rather than lost. A miss driven by medical costs rather than spending would be far more damaging, because it would suggest the higher-acuity members are costing more than the pricing assumed.
That makes the benefit ratio the number to study. Second-quarter adjusted MBR was 86.3%, and a seasonal rise is expected. What matters is the size of that rise and the explanation behind it. Reserve development deserves attention too, since the second quarter carried a $6 million unfavorable adjustment to prior-year claims. Another negative revision would raise questions about whether reserves are keeping pace with a fast-changing member base. Membership should track toward the 298,000 to 301,000 year-end target from 294,100 at midyear, and any early read on 2027 products and in-state market expansion will speak to the roughly 20% growth goal. Investors will have less visibility on coding intensity, since the company has stepped back from quarterly ADK disclosure.
Sentiment has swung from moderately bearish before the last report to moderately bullish now, which hints that some buyers see the collapse as overdone. The chart is less forgiving. At $8.51, the stock sits far below its 200-day moving average near $17.34 and much closer to its post-report low of $6.01 than its high of $16.49. Regulatory overhangs, including a pending 2028 Medicare Advantage rule and uncertainty around Star ratings, are not going away this quarter.
Ultimately, the report will be judged on whether third-quarter weakness stays inside the box management drew. If EBITDA lands in range, costs trace back to deliberate investment, and the full-year outlook holds or rises, the bull case of expanding embedded earnings remains intact. If medical costs rather than spending explain the shortfall, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 4 hours | |
| 10 hours | |
| Oct-20 | |
| Oct-19 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 | |
| Oct-09 | |
| Oct-09 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 |
