Alignment Healthcare Matches EPS Forecast, But A Medical-Cost Surge Forces A Steep Profit Reset Despite Accelerating Growth
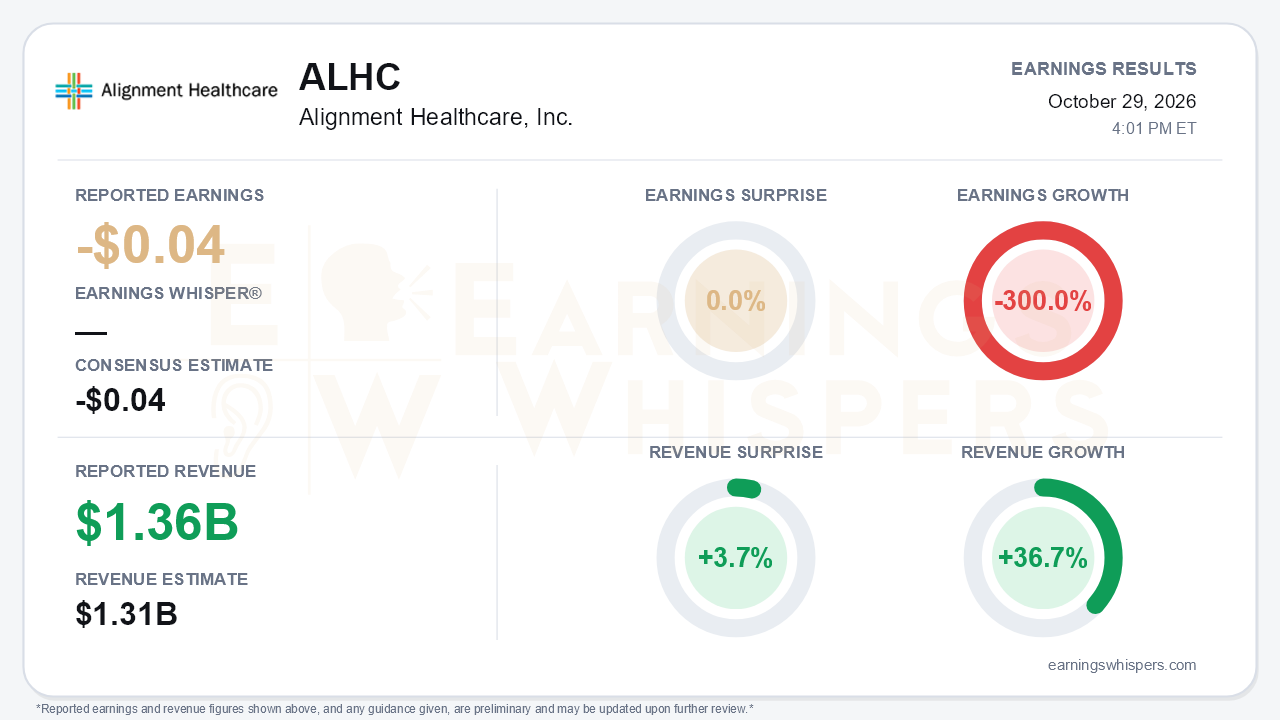
Alignment Healthcare (NASDAQ: ALHC) reported a third-quarter loss of $0.04 per share, exactly in line with the consensus estimate. Revenue of $1.358 billion beat expectations by 3.7% and grew 36.7% from a year ago. The headline, however, understates what changed. Earnings fell 300.0% year over year, a swing from a $0.02 profit to a $0.04 loss. Management then cut full-year adjusted EBITDA guidance by roughly a third. Growth is accelerating while profitability is going the other way, and that is the central tension. After three straight beat-and-raise quarters, this was a reset.
The quality of the quarter deserves scrutiny. Membership reached 301,200, up 31.2% and above the 295,500–297,500 guidance range. Revenue growth sped up from 32% in the second quarter. Those additional members cost far more than planned. The medical benefits ratio rose to 89.5%, up roughly 240 basis points from a year earlier and about 100 basis points worse than the guidance midpoint. That compares with 86.3% in Q2 and 88.2% in Q1. As a result, adjusted gross profit of $142.2 million rose only 11.6% and fell short of the company's $148–158 million guide. Adjusted EBITDA dropped 32.8% to $21.8 million, a 1.6% margin, though it stayed within the $20–30 million range. On a GAAP basis, operations swung to a $3.8 million loss. SG&A ran at 8.9% of revenue, about 90 basis points better than planned, but lower incentive-compensation accruals helped. That is not a structural efficiency gain.
The cost drivers point to self-inflicted operating friction as well as industry pressure. Management cited elevated provider appeals and disputes that surfaced after the company migrated to the FACETS claims system. It also flagged higher costs in catastrophic cases and longer skilled-nursing stays. Some of the ratio increase reflected expected Part D seasonality and the timing of clinical investments. The appeals problem connects to $6 million of unfavorable prior-period reserve development in Q2, which raises legitimate questions about reserving visibility. Management's tone changed sharply. Three months ago it was talking about its "lowest MBR as a public company" and $880 million of embedded earnings. On this call the vocabulary was "reset," "prudence" and a "wake-up call."
The guidance makes the damage explicit. Full-year revenue guidance rose to at least $5.245 billion, and year-end membership is now expected to be at least 305,000. Adjusted gross profit guidance fell to at least $575 million from $630–650 million. Adjusted EBITDA guidance fell to at least $100 million from $145–163 million. The fourth-quarter outlook implies a 92.1% MBR and an adjusted EBITDA loss of at least $28 million. CEO John Kao said the revised outlook assumes no benefit from corrective actions underway, which builds in some cushion. Earnings Whispers characterized the guidance as in line with expectations, suggesting forecasts had already moved down ahead of the report.
The second blow is structural. Alignment's California HMO contract, its largest, dropped to 3.5 Stars for payment year 2028. A year ago management touted 100% of members in 4-plus-star plans. This creates a meaningful revenue headwind tied to the company's most concentrated exposure. Management is pursuing Stars litigation and identified risk-adjustment improvements as a partial offset. It also reiterated a 2027 growth target of at least 20% and said the annual enrollment period is off to a strong start, with no broker fallout from the Stars miss.
Growth catalysts remain on the table:
- payment-integrity tools being built on the new claims platform;
- utilization management brought in-house, with de-delegation roughly 80% complete;
- new partnerships with Hoag and an expanded Astrana relationship;
- 2027 entry into San Antonio and Charlotte.
The balance sheet offers some room to execute. Cash and short-term investments total about $743 million, and nine-month operating cash flow reached $158 million. Bears still have ammunition. Leverage rose to 2.4x from 2.2x, and management itself warned that competitors could get more aggressive in 2027.
The stock had already priced in much of the damage before the report. Shares closed at $8.18 the day before the release, down 47.2% from the $15.50 opening after the July report and about 52% below the 200-day moving average. The stock hit a 52-week low of $6.01 on October 9 and had rebounded roughly 36% from that level heading into the print. Investor sentiment improved from -0.20 to -0.11, which is less pessimistic but still negative.
The bottom line is that Alignment's growth engine is running faster than ever, but the third quarter showed the company cannot yet price and manage the medical costs that come with it. A one-third EBITDA cut, a guided fourth-quarter loss and a Stars downgrade on its largest contract shift the burden of proof onto execution. With the stock already cut nearly in half, the next few quarters will hinge on whether claims-system fixes and utilization controls bring the MBR back toward first-half levels.
Read our earnings preview for Alignment Healthcare, Inc.: https://www.earningswhispers.com/article/ALHC/21162
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 | |
| Oct-09 |
