CareDx Faces First NavDx Quarter With Street Estimates Trailing Its Raised Outlook
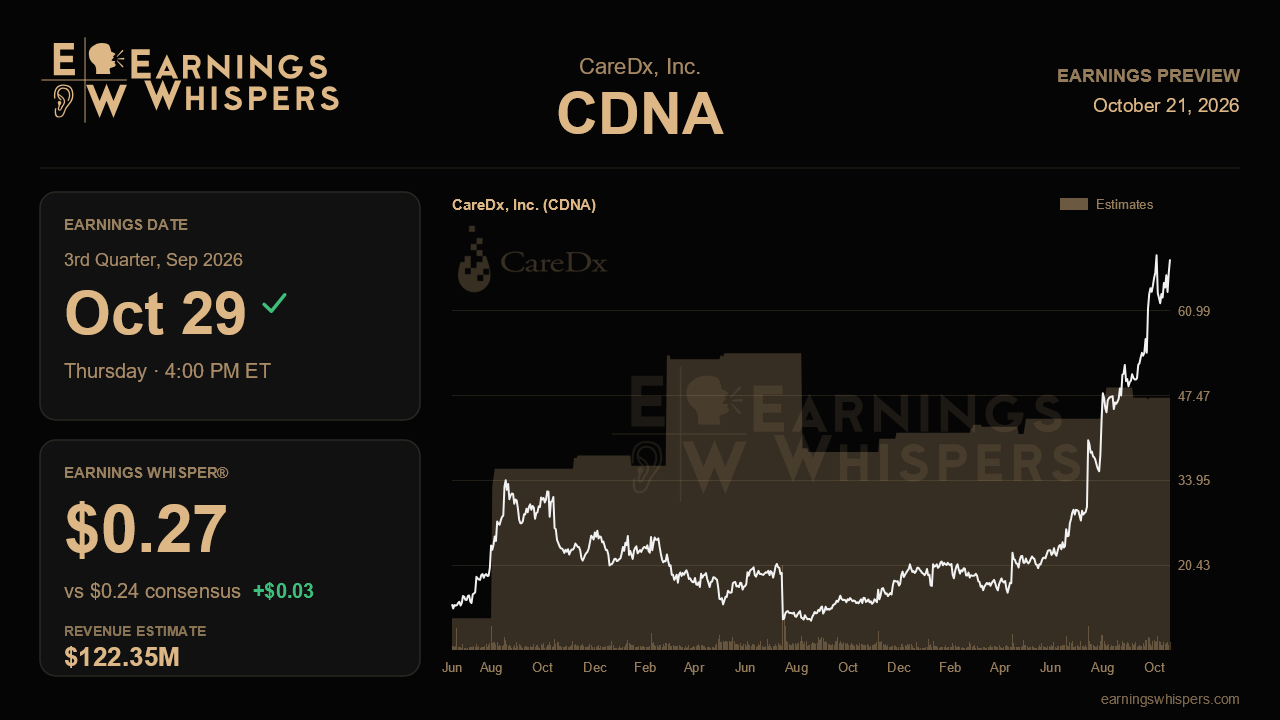
CareDx enters its third-quarter report with an unusual setup: management has raised its full-year revenue outlook three times, the stock has nearly doubled its trading range, and yet the published consensus still looks anchored to an older version of the story. The quarter, due after the close on October 29, is the first to include the newly acquired NavDx oncology business and the first without the divested lab products line. That makes it the cleanest look yet at what the reshaped company actually earns.
Analysts expect non-GAAP earnings of $0.24 a share on revenue of $122.4 million, which would be growth of about 22% from the $100.1 million posted a year ago. The whisper number sits at $0.27, a modest but meaningful step above consensus that suggests buy-side expectations lean toward another beat. Context helps here. Second-quarter revenue was $131.9 million, but that included the lab products business, which management said carried roughly $48 million of annual revenue, or about $12 million a quarter. NavDx is expected to contribute about $24 million across the second half, roughly the same amount. On that arithmetic, a revenue figure near $122 million would imply the core business stepped backward, which seems at odds with management raising its third-quarter transplant testing volume target to 58,000 from 56,600. The full-year picture reinforces the point: the company now guides to $490 million to $500 million, while the full-year consensus of $455 million sits below the bottom of that range. Either estimates have not caught up, or the Street doubts the guide.
The operating questions flow from the July call. Testing services revenue jumped 61% in the second quarter, driven by surveillance and for-cause adoption rather than growth in transplant procedures, which remain broadly flat. Confirmation that volumes hit or exceed the 58,000 target would show that the favorable Medicare coverage decision finalized in mid-July is translating into steady ordering, and that removing the roughly $7.5 million coverage headwind from guidance was justified. Progress on Epic Aura connectivity, live at 17 centers with a target of 30 to 40 by year-end, would offer a forward indicator of stickier demand.
Margins deserve close attention. Adjusted EBITDA climbed from $6.5 million in the fourth quarter to $19 million and then $25 million, with non-GAAP gross margin reaching 74%. Yet the raised full-year EBITDA guide of $66 million to $78 million implies only $22 million to $34 million across the entire second half, well below the second-quarter run rate. That gap likely reflects NavDx integration costs and a deliberately cautious oncology pricing assumption of $770 to $795 per test against an $1,800 Medicare rate. A quarterly EBITDA figure that holds closer to the $20 million range would signal the guide is conservative; a sharp drop would suggest oncology is diluting margins more than hoped.
Sentiment has swung from decidedly bearish before the last report to clearly bullish now, and the shares have rallied about 63% since then against a 3% gain in the S&P 500. At $69.20, the stock trades more than double its 200-day average and sits in the upper portion of its post-earnings range, about 5% below the $72.51 high. That move means the market has already rewarded the transformation narrative, raising the cost of any stumble.
The central issue is whether the core transplant franchise keeps compounding while NavDx is absorbed without margin erosion. Clear commentary on readiness for the fourth-quarter billing migration, which management flagged as the key step toward lifting oncology pricing toward $1,000 or more per test, will determine whether investors view the raised outlook as a floor or a ceiling.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-15 | |
| Sep-24 | |
| Aug-07 | |
| Aug-03 | |
| Jul-31 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-16 | |
| Jul-16 | |
| Jul-16 | |
| Jul-02 | |
| Jul-01 | |
| Jun-30 |
