CareDx Raises Guidance For A Third Straight Quarter As Transplant Volume Accelerates, But One-Time Items And A Softer Implied Q4 Temper The Beat
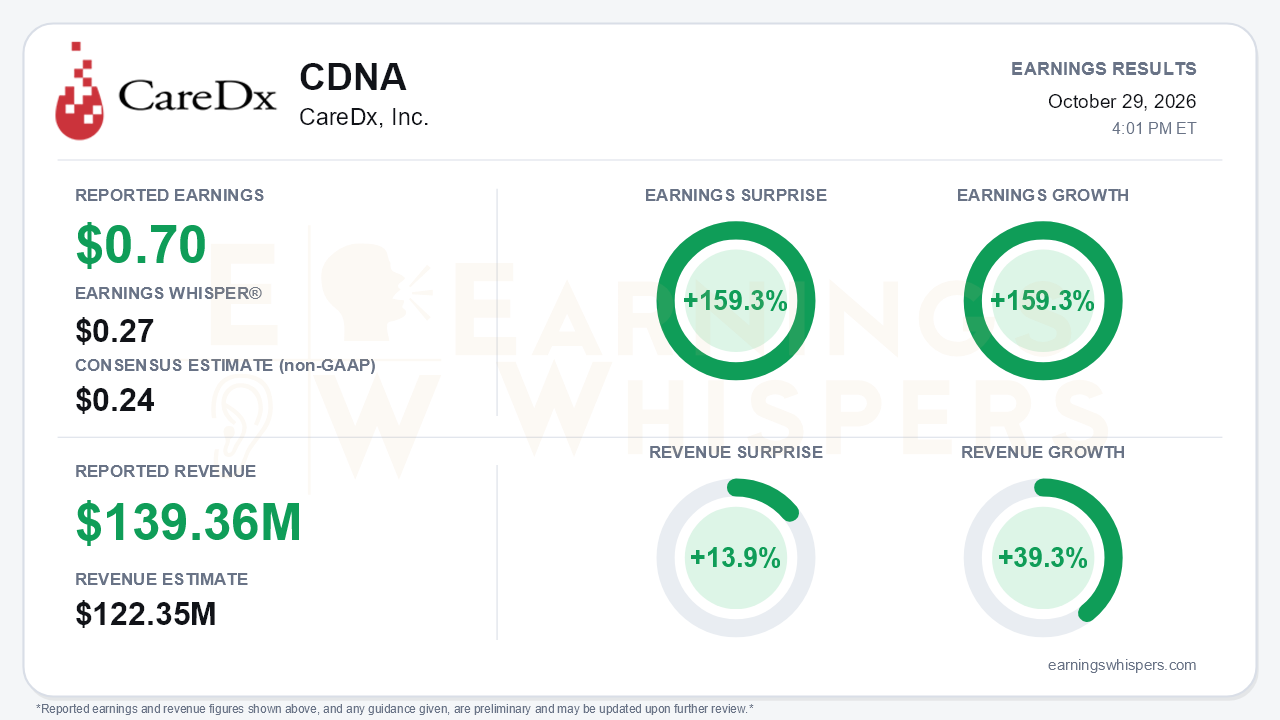
CareDx delivered a quarter that turnaround skeptics were not positioned for. Non-GAAP earnings of $0.70 per share beat the $0.24 consensus by 159.3% and cleared the $0.27 Earnings Whisper number. Revenue of $139.36 million topped the $122.35 million estimate by 13.9% and grew 39.3% year over year. Earnings also grew 159.3% from a year ago. Management then raised full-year 2026 guidance for the third straight quarter. Revenue guidance is now $520 million to $530 million, up from $490 million to $500 million. Adjusted EBITDA guidance is now $90 million to $100 million, up from $66 million to $78 million. A year ago, the initial targets were $420 million to $444 million in revenue and just $30 million to $45 million in EBITDA. The central tension is that the core business is genuinely accelerating, while several items flattered the headline beat and the implied fourth quarter steps down noticeably.
The quality of the beat deserves scrutiny. First, the company recorded an $8.6 million income tax benefit. That benefit carried through to non-GAAP results and accounts for roughly $0.16 of the $0.70. Second, Testing Services revenue included $15 million of prior-period collections, nearly double management's earlier $8 million estimate and well above the $6 million recorded a year ago. Excluding out-of-period revenue, total growth was about 32% rather than 39%. Third, the comparison is structurally messy. The quarter included about $12.5 million from NavDx, the Naveris acquisition closed July 1. It excluded the divested Lab Products business, which contributed $12.5 million a year earlier. Diluted GAAP EPS was $0.35. Cash flow from operations fell to $12.7 million from $37.4 million. Even so, the operating improvement is real. Adjusted EBITDA doubled to $30.5 million, a 22% margin versus 19% in the second quarter and 15% a year ago. Non-GAAP gross margin held at 74%.
The call made the strongest case for the underlying trend. Transplant test volume grew 21% to roughly 50,750, accelerating from 17% growth in each of the first two quarters. Analysts described it as the strongest volume quarter in four years. Transplant revenue per test, excluding out-of-period revenue, rose 15% to $1,514. NavDx also outperformed in its first consolidated quarter:
- Revenue grew 37% on a pro forma basis, at the top of its 30-40% target.
- Volume reached 15,150 tests against a 14,600 guide.
- Average selling price was $823, ahead of the $770-$775 forecast.
Management sees NavDx pricing moving toward $1,000 or more, against an $1,800 Medicare rate. It also said the final LCD overhang has cleared with no volume disruption.
The catalyst slate is unusually dense:
- A randomized Paris Transplant Group trial presented at ASN found AlloSure-based monitoring cut biopsies by 49% with similar outcomes. That evidence could support protocol adoption and payer coverage.
- Two Phase II radiation de-escalation studies and a 332-patient multicenter study broaden the contexts in which NavDx can be used.
- AlloHeme remains on track for a first-quarter 2027 launch, native on Epic Aura from day one.
- HistoMap is targeting broader availability in 2027.
- Epic Aura adoption grew to 21 live transplant centers, up from 17 in the second quarter and 9 in the first.
Bears still have legitimate ammunition. The guidance implies fourth-quarter gross margin of 71-72% and adjusted EBITDA of $16 million to $26 million, about a 15% margin. Operating expenses are expected to rise to roughly $79 million as the company builds its oncology field team and prepares the AlloHeme launch. Out-of-period revenue is expected to fall to about $8 million and then normalize near 2% of revenue, which creates tougher comparisons. Fourth-quarter transplant volume growth is guided back to 17% against a strong prior-year comparison. NavDx's October migration to the CareDx billing platform adds execution risk. Cash fell to $250 million from $374 million after the acquisition, although the company still carries no debt.
The market had largely anticipated a strong report. Investor sentiment swung from negative (-0.29) to positive (+0.24), a substantial shift in expectations. Shares rose 69.8% from the $42.49 open after the July report to $72.13. That close was just 1.8% below a 52-week high of $73.43 set the day before this release and 118.7% above the 200-day moving average. Most Earnings Whispers trend readings are positive, although sequential growth registers only neutral. With the stock sitting near the top of its range and sentiment now positive, the setup is more demanding than the size of the surprise implies.
The bottom line is that CareDx showed real operating momentum: accelerating transplant volume, better pricing, an early outperformance from NavDx and a third consecutive guidance raise. However, a tax benefit and elevated catch-up collections inflated the size of the beat. The implied fourth quarter also signals margin compression as investment ramps. After a nearly 70% run into the print, the fundamental story looks credible, but investors are no longer underestimating it.
Read our earnings preview for CareDx, Inc.: https://www.earningswhispers.com/article/CDNA/21171
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 3 hours | |
| 4 hours | |
| Oct-22 | |
| Oct-21 | |
| Oct-15 | |
| Sep-24 | |
| Aug-07 | |
| Aug-03 | |
| Jul-31 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-16 | |
| Jul-16 |
