DaVita's Volume Recovery Faces A Margin Test As Rate And Cost Pressures Build
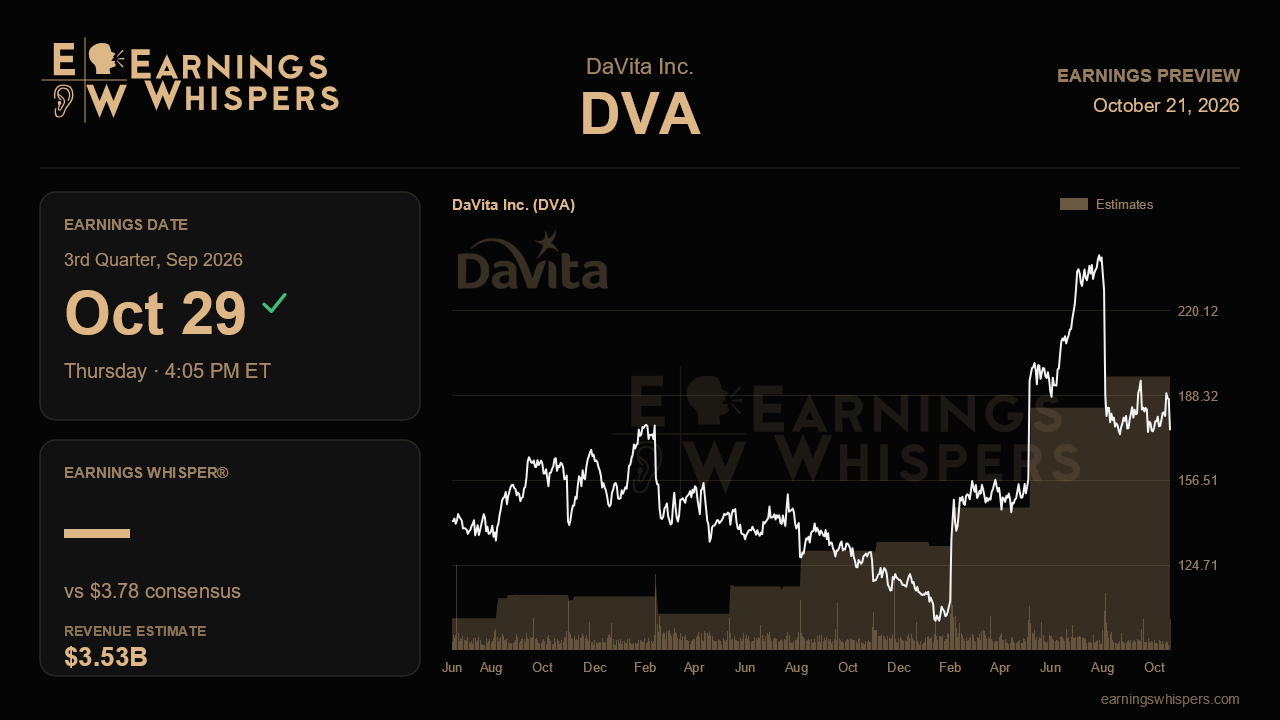
DaVita heads into its third-quarter report with an unusual split between its operating story and its stock chart. On the last call, management said patient volumes were firming faster than planned, thanks to a sustained drop in mortality, and introduced a promising new clinical tool. Yet the shares have fallen 14.6% since that report, trailing the S&P 500 by nearly 14 percentage points. The market appears focused on the other half of the message: revenue per treatment is turning into a headwind in the back half of the year, and costs are running hotter than planned.
Wall Street expects earnings of $3.78 per share on revenue of $3.53 billion. That would be a roughly 51% jump from the $2.51 earned a year ago, but the comparison is flattered by a weak base that included a $45 million cyber-related hit. Revenue growth of about 3.2% is a more honest read on the underlying pace. Sequentially, the forecast marks a step down from the $4.02 earned in the second quarter, which fits management's warning that second-half revenue per treatment would be slightly negative year over year. That warning came even though it had grown 3.6% through the first half.
The guidance math deserves attention. DaVita has reaffirmed its 2026 outlook of $14.10 to $15.20 per share for two straight quarters, with an adjusted midpoint of $14.65. The full-year consensus of $15.07 sits near the top of that range. So analysts are already assuming DaVita outperforms its own midpoint, even though management has declined to raise it. That leaves limited room for a quarter that merely lands on plan. A clean beat paired with at least a nudge toward the upper end of guidance would validate the Street's posture. Another flat reaffirmation could read as a quiet signal that the high end is out of reach.
Operationally, volume is the piece of the narrative most likely to hold up. Management's full-year treatment growth outlook has moved from flat in February, to 25 to 50 basis points in May, to near the top of that range in August, after second-quarter treatments rose 56 basis points. With the boost from Fresenius closed-clinic patients now finished and lighter than hoped, third-quarter growth has to come from organic admissions and lower mortality. Evidence that mortality gains are persisting would support the longer-term goal of returning to 2% or better volume growth by 2029. So would early progress rolling out the Expanded HD dialyzer, which management plans to deploy broadly across existing machines.
The risks sit on the margin line. Patient care costs per treatment rose more than 3% year to date, above the full-year target, and general and administrative expense climbed about 10% on technology spending. U.S. dialysis operating income was roughly flat even after lapping last year's cyber disruption. Commercial mix is also eroding as expired ACA subsidies push patients off exchange plans, a $40 million drag this year that grows to $70 million in 2027. Any update on the final 2027 Medicare rate and phosphate binder economics will shape how investors handicap next year. Integrated kidney care, which added $40 million of operating income last quarter, is a potential offset worth tracking.
Sentiment has improved to 40.1% bullish from 22.4% a quarter ago, even as the stock slid. Shares sit at $175.35, just above the 200-day moving average and near the bottom of a post-earnings range of roughly $171 to $209. The central question is whether volume momentum and cost discipline can outrun the pricing squeeze. If costs per treatment come back toward plan while volumes hold near the top of guidance, the high-end consensus looks defensible. If not, the recent selloff may prove to have been an early warning rather than an overreaction.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 56 min | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-15 | |
| Oct-08 | |
| Sep-24 | |
| Sep-17 | |
| Sep-14 | |
| Sep-08 | |
| Sep-02 | |
| Aug-26 | |
| Aug-25 | |
| Aug-25 | |
| Aug-14 |
