DaVita Edges Past Estimates, But Buybacks And A Back-Loaded IKC Forecast Carry More Weight Than Dialysis Momentum
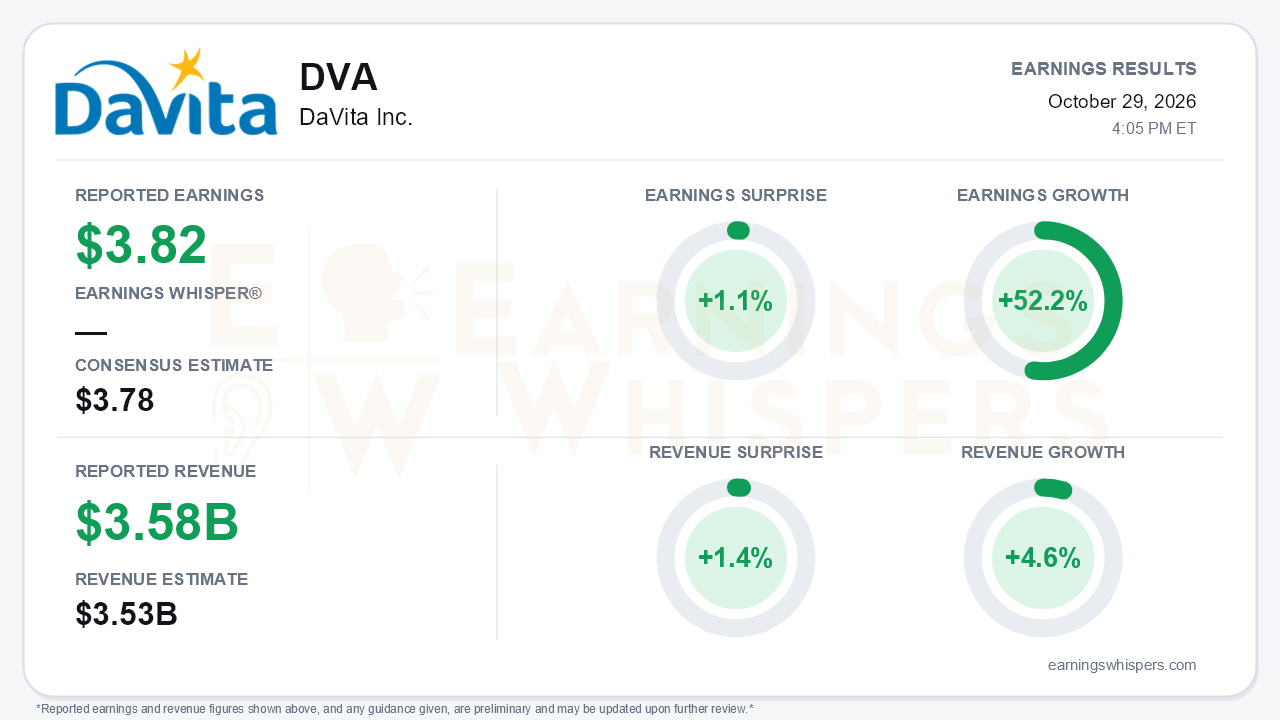
DaVita delivered a modest beat that says more about capital allocation than about acceleration in its core business. Adjusted earnings of $3.82 per share topped the $3.78 consensus by 1.1%, and revenue of $3.578 billion beat the $3.53 billion estimate by 1.4%. Year-over-year earnings growth of 52.2% looks spectacular against 4.6% revenue growth, and that gap is the central tension. Sequentially, the quarter went backward: adjusted EPS fell from $4.02 in the second quarter, adjusted operating income slipped to $561 million from $579 million, and adjusted operating margin compressed to 15.7% from 16.3%.
The quality of the year-over-year comparison deserves scrutiny. Diluted shares fell to 65.5 million from 73.8 million a year earlier, an 11% reduction that does much of the work behind the EPS growth. Net income attributable to noncontrolling interests also roughly halved, and the year-ago quarter carried a $41 million other loss compared with a $9 million gain this time. GAAP EPS of $3.40 included a $62 million goodwill and asset impairment tied to China, which cost DaVita $27 million after tax and minority-interest offsets. Consolidated operating income was essentially flat with the prior year at $499 million versus $506 million. Cash generation was softer. Free cash flow of $276 million compared with $604 million a year ago, and trailing-twelve-month free cash flow fell to $980 million from $1.31 billion last quarter. Buybacks slowed to $111 million from $348 million in the second quarter, and leverage held at 3.38x.
Beneath the headline, the operating picture was mixed but not deteriorating. U.S. dialysis operating income rose to $544 million from $538 million, and volume continued to improve. Treatments per day rose 1.2% year over year, and management cited normalized per-day growth of roughly 65 basis points, up from 56 in the second quarter and 40 in the first. Pricing, however, did not help. Revenue per treatment was essentially flat sequentially at $415.25, while patient care costs per treatment climbed $2.82 on medical supplies. The call added professional liability costs, a mistreatment rate about 20 basis points above plan, and technology spending growing more than 20%. The sequential decline in consolidated profit came mainly from integrated kidney care, where operating income dropped to $4 million from $40 million, and from higher corporate costs. International was a bright spot, with adjusted operating income of $46 million, up $20 million year over year.
Guidance captures the push and pull. Management raised the low ends of its adjusted operating income range to $2.175 billion and its adjusted EPS range to $14.30, while leaving the high ends at $2.25 billion and $15.20. Free cash flow guidance was unchanged. The call framed this as a $25 million lift to the integrated kidney care outlook, now at least $65 million for 2026, offset by higher U.S. dialysis costs. With only $24 million earned in that segment through nine months, the forecast implies a heavy fourth-quarter contribution from shared savings, an execution risk worth watching. The forward catalysts are more compelling. The final 2027 ESRD rule came in better than proposed, and management estimates a net 1.5% to 2% benefit. A national expanded-hemodialysis rollout begins in November after pilots showed more than 90% adoption among eligible patients. A Humana partnership extends upstream CKD care to about 10,000 patients. Management also expects 2027 volume growth to exceed 2026, with lower drug and binder costs. Bears still have legitimate ammunition. They can point to a roughly $70 million ACA-driven commercial mix headwind in 2027, quarterly TDAPA recalculation, and HHS scrutiny of charitable premium assistance.
Investor sentiment improved into the report, rising from 0.22 to 0.33, a meaningful but not dramatic shift toward optimism. Price action has been less generous. Shares closed at $183.93 before the release, 10.4% below the open following the August report and nearly 12% below the inter-earnings high of $208.53 set that same day. The stock bounced 7.5% off its October 20 low of $171.09 and sits 4.6% above its 200-day moving average. Most Earnings Whispers trend readings are neutral, though AVWAP remains positive. In short, the market has already given back the post-August optimism, and it is no longer pricing in perfection.
The bottom line is that DaVita's beat was narrow, sequentially weaker, and heavily flattered by a shrinking share count. Still, the call preserved a credible medium-term story built on improving volume, a better 2027 reimbursement rule, and new clinical and value-based catalysts. The near-term debate centers on cost discipline in U.S. dialysis and whether the back-loaded integrated kidney care forecast actually lands.
Read our earnings preview for DaVita Inc.: https://www.earningswhispers.com/article/DVA/21183
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-27 | |
| Oct-26 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-15 | |
| Oct-08 | |
| Sep-24 | |
| Sep-17 | |
| Sep-14 | |
| Sep-08 | |
| Sep-02 |
