Covista's First Fiscal 2027 Quarter Tests Chamberlain Momentum As Investment Spending Peaks
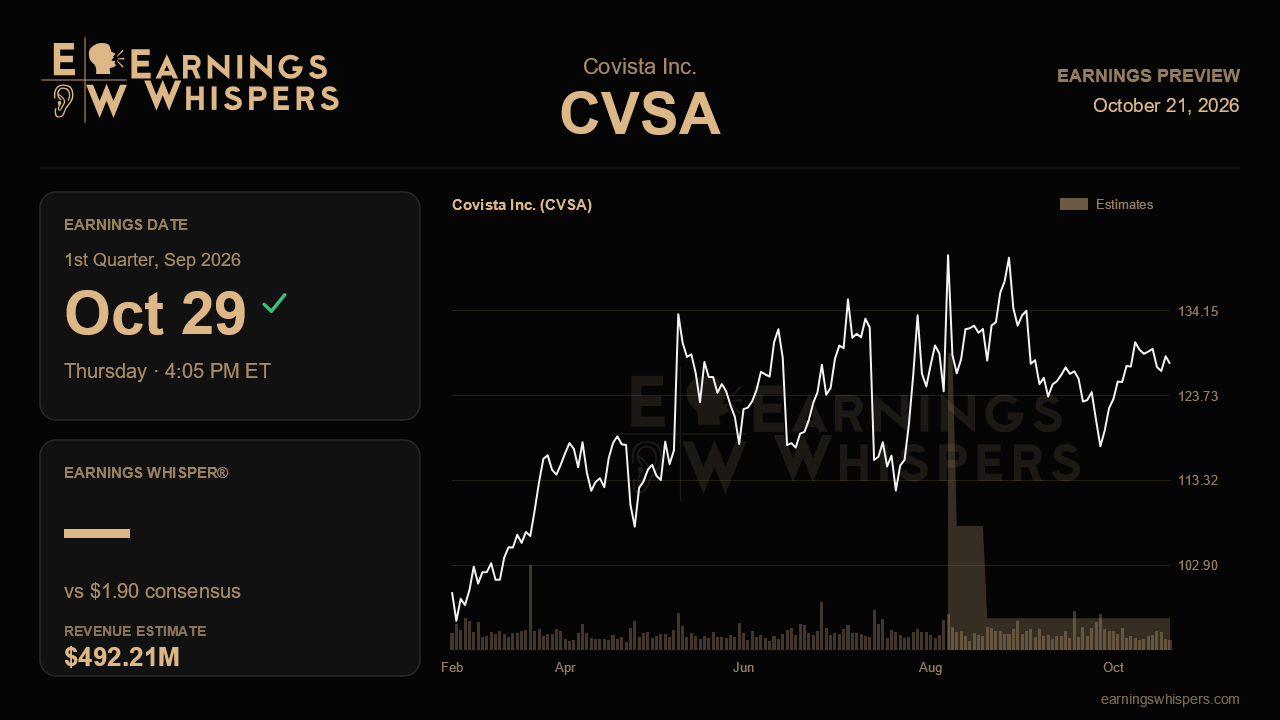
Covista enters its fiscal first-quarter report with an unusual gap between what management promised and what Wall Street is willing to believe. The company opened fiscal 2027 by guiding to adjusted earnings of $8.90 to $9.15 per share, yet the full-year consensus sits at $8.85, just below the bottom of that range. Revenue expectations of $2.07 billion land at the midpoint of the $2.05 billion to $2.09 billion outlook. Analysts are comfortable with the top line but doubt how much of it reaches the bottom line. The September quarter, when management said campus and technology spending would weigh most heavily, is the first real chance to settle that argument.
For the quarter itself, the Street expects earnings of $1.90 per share on revenue of $492.2 million, a step down from the $2.09 and $501.4 million posted in the fiscal fourth quarter. Some sequential softness is built into the business calendar, and management flagged a front-half-loaded investment cycle, with six campuses in development at roughly $9 million to $12 million apiece. FY27 margin expansion was guided to only about zero to 50 basis points, compared with roughly 100 basis points in fiscal 2026. A quarter that lands near consensus on earnings while holding revenue on plan would suggest the spending is tracking budget. A clear earnings beat would strengthen the case that consensus is too conservative relative to guidance.
The most important operating signal is Chamberlain. After a stretch of remediation, total enrollment growth improved from 0.5% in the third quarter to 1.6% in the fourth, and management declared the issues fully addressed while saying it expected further acceleration in the first quarter. That is a specific, checkable claim. Growth above the fourth-quarter pace would validate the recovery narrative. A stall would raise questions about whether conversion rates have truly normalized. The new Advocate Health partnership, whose first cohort began in September, and the raised SSM enrollment targets in St. Louis give management fresh employer-channel evidence to point to, even if their financial contribution remains small for now.
Walden faces a tougher test. It closed fiscal 2026 with a record of roughly 55,000 students, up 14%, and undergraduate enrollment rose more than 20%. Those are demanding comparisons, and management already cited tougher Walden and MedVet comps as reasons for the slower 5% to 7% revenue guide. MedVet carries an added wrinkle: some fourth-quarter enrollment was pulled forward by changes to student loan rules. A soft MedVet start this quarter would be explainable as timing. Persistent weakness would be harder to dismiss. Management also raised a longer-term worry that AI-driven answer engines could erode search-based lead generation, so any commentary on marketing efficiency and inquiry volumes deserves attention.
The market's posture is cautious but not hostile. Sentiment has edged further into bearish territory, from 5.5% bearish before the last report to 9.0% now, and the stock has gained just 0.4% since then, roughly in line with a flat S&P 500. Shares at $127.64 sit comfortably above the 200-day moving average of $111.54 but about 10% below the post-earnings high of $142.13. That suggests early enthusiasm for the fiscal 2026 beat faded as investors digested the slower growth outlook.
The central question is whether Covista can absorb its heaviest investment quarter without bending the earnings trajectory it laid out. If Chamberlain accelerates as promised, Walden holds up against record comparisons, and management reaffirms or nudges up its full-year range, the skeptics sitting below guidance will have little ground left. If spending runs hot or enrollment momentum cools, the Street's caution will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-21 | |
| Oct-13 | |
| Oct-01 | |
| Sep-29 | |
| Sep-28 | |
| Sep-15 | |
| Sep-14 | |
| Sep-09 | |
| Sep-08 | |
| Sep-06 | |
| Aug-20 | |
| Aug-07 | |
| Aug-06 | |
| Aug-05 |
