Covista Beats By 15% But Raises Only Modestly As Chamberlain And MedVet Enrollment Cool
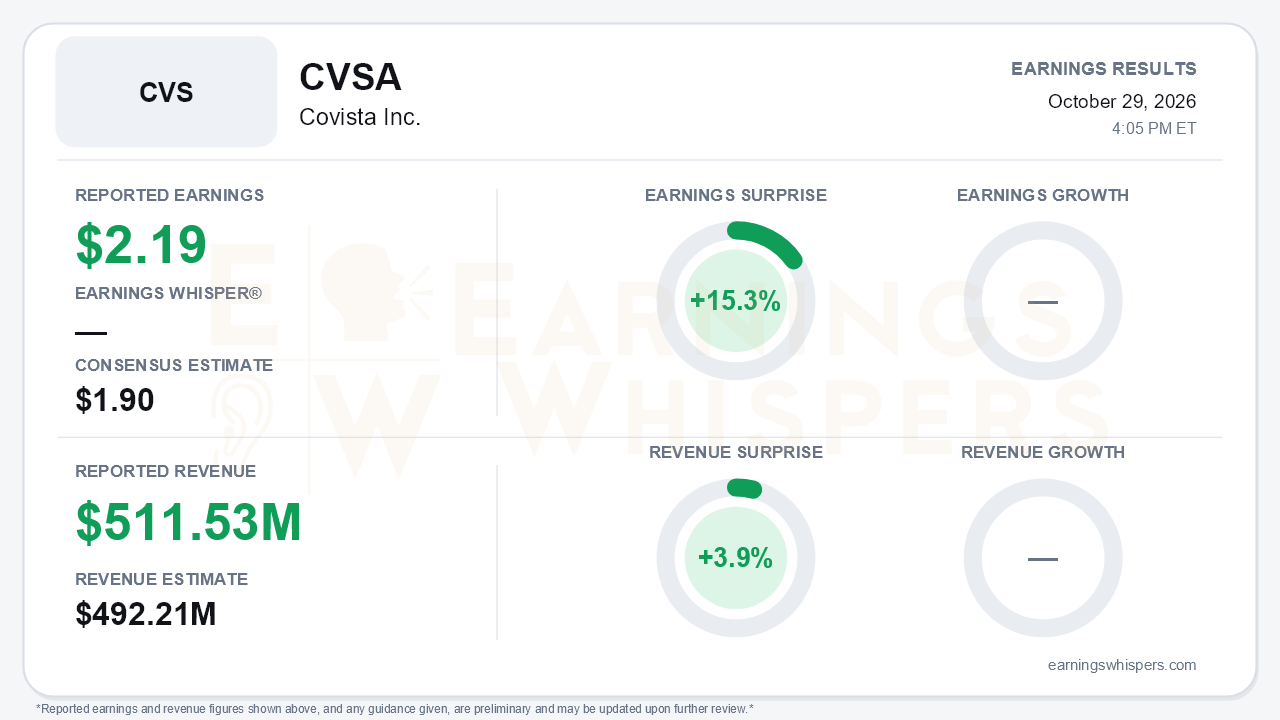
Covista delivered a clean top- and bottom-line beat for its fiscal first quarter. Adjusted earnings of $2.19 per share topped the $1.90 consensus by 15.3%, and revenue of $511.53 million beat the $492.21 million estimate by 3.9%. Revenue grew 10.7% year over year, an acceleration from 9.7% in the fourth quarter and 4.5% in the third. The company reported adjusted EPS growth of 25.1%, roughly in line with the 25.9% pace of the prior quarter. Management raised fiscal 2027 guidance, but the raise is small relative to the beat. That is the central tension: the quarter was strong, yet the forward outlook and parts of the enrollment base imply a business that is not compounding as fast as Q1 suggests.
The quality of the beat holds up better than most, though it deserves some scrutiny. GAAP diluted EPS rose to $1.95 from $1.67, and EPS from continuing operations was $2.07. The gap to the adjusted figure comes mainly from $0.18 of strategic advisory costs and $0.12 of discontinued-operations losses tied to legacy litigation. A $0.06 foreign-derived-income tax benefit was excluded, which partly offsets those add-backs. Operating leverage was real. Adjusted EBITDA rose 17.1% to $131.2 million, and margin expanded 140 basis points to 25.6%, faster than the 120-basis-point gain in Q4. Buybacks also did meaningful work. Diluted shares fell to 34.6 million from 37.1 million, which is why adjusted net income grew about 17% while adjusted EPS grew 25%. Less flattering details sit lower in the statements. The provision for credit losses jumped to $22.4 million from $14.9 million. Operating cash flow fell to $114 million from $131 million, and capex more than doubled to $37.6 million. Trailing free cash flow of $355 million is below the $393 million posted for fiscal 2026.
Segment results show a growth engine that is increasingly concentrated in Walden. Walden revenue rose 14.1% on 12.8% enrollment growth to a record of nearly 59,000 students. That marks its 10th straight double-digit quarter, though growth eased from 14% in Q4 on tougher comparisons. Medical and Veterinary posted the sharpest margin improvement: adjusted operating margin reached 21.7%, up from 18.0%. However, its enrollment growth slowed to 3.5% from 7.3% in Q4. Management attributed the slowdown to lingering hesitancy over loan caps after earlier pull-forward. Chamberlain is the weak spot. Total enrollment grew just 1.3%, down from 1.6% in Q4, even though management had guided to acceleration. Management called the result "incrementally short," citing fewer returning students and soft RN-to-BSN demand. Chamberlain's operating margin also slipped to 13.9% from 14.3%. Pre-licensure BSN enrollment, up 13.2% for a 17th straight quarter of growth, remains the bright spot within the segment.
The catalyst list is substantive. The Advocate Health nursing collaboration went live in Wisconsin and is expanding to Chamberlain's three Chicago-area campuses. SSM Health enrollment targets were raised again. Cincinnati and Salt Lake City opened, with Nashville slated for January, and a second physician assistant program opened in Phoenix at full capacity. The company also repriced its $510 million term loan 25 basis points lower, lifted buybacks to $84 million with $578 million of authorization remaining, and holds net leverage of just 0.5x. Against that, the full-year margin expansion target stayed at 0 to 50 basis points, well below Q1's 140. Management described the remaining quarters as "prudent" and cited several pressures: new-campus startup costs, a higher tax rate, and a Walden calendar shift that will push second-quarter growth and margins well below the full-year rate. CFO Robert Phelan's planned retirement adds a transition variable.
Investor sentiment moved decisively the wrong way. It fell from roughly neutral at -0.06 to -0.40 heading into and through the report, a meaningful shift toward skepticism. Price action has been far less dramatic. Shares at $128.76 are up just 1.2% from the open following the August report, but they sit 14.8% above the 200-day moving average of $112.20, and the AVWAP trend reading is positive. Investors appear to be giving Covista credit for its execution while questioning how much more upside the guidance leaves on the table.
The bottom line is that Covista posted an accelerating, high-quality beat powered by Walden, margin expansion and aggressive buybacks, but the guidance raise captures only a fraction of the outperformance. Meanwhile, Chamberlain and Medical and Veterinary enrollment both decelerated. Management's conservatism around Q2 and margins may set up further beats. Bears, however, have legitimate ammunition in the slowing enrollment outside Walden, rising credit-loss provisions, heavier capex and a CFO transition, and souring sentiment suggests investors are weighing those risks seriously.
Read our earnings preview for Covista Inc.: https://www.earningswhispers.com/article/CVSA/21181
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-29 | |
| Oct-29 | |
| Oct-27 | |
| Oct-22 | |
| Oct-21 | |
| Oct-13 | |
| Oct-01 | |
| Sep-29 | |
| Sep-28 | |
| Sep-15 | |
| Sep-14 | |
| Sep-09 | |
| Sep-08 | |
| Sep-06 |
