Exponent Must Prove AI Device Demand Can Outrun A Shrinking Mega-Study
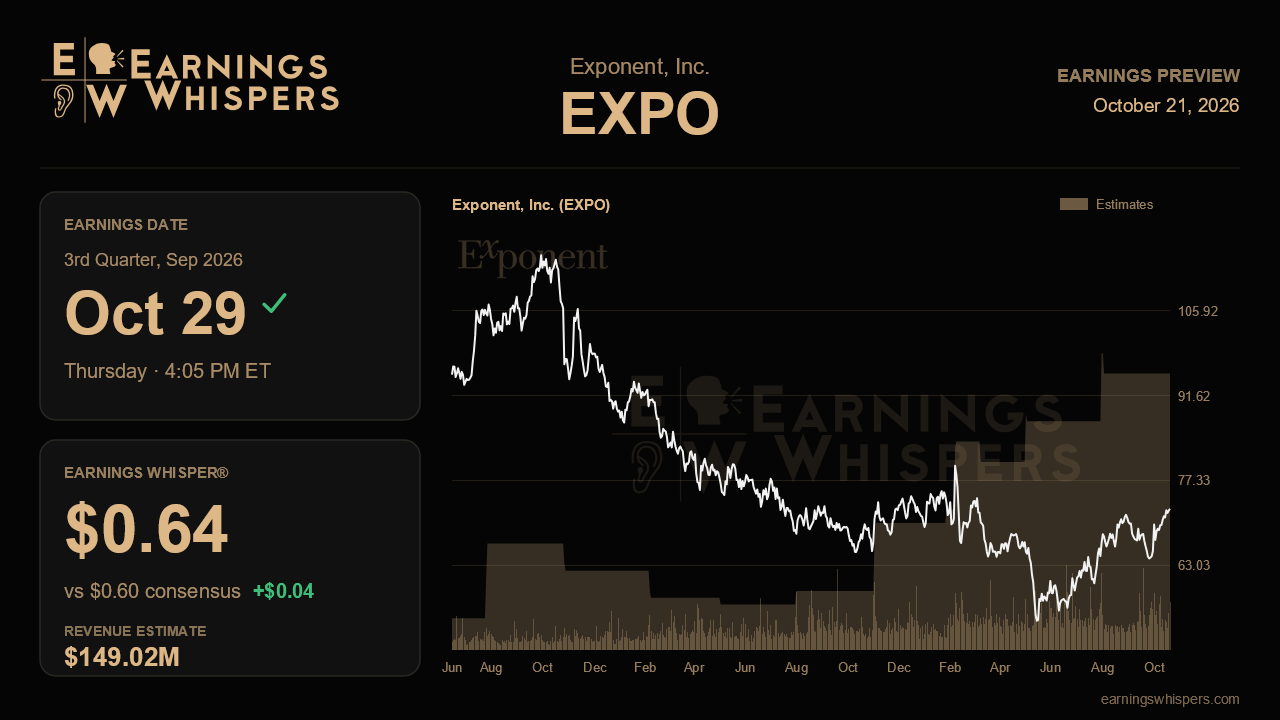
Exponent heads into its third-quarter report with a problem most consulting firms would envy: its best recent tailwind is getting smaller by design. A single large user research study ballooned to roughly 4% of net revenues last quarter, double what management had planned, and is now expected to settle back near a 2% run rate. The question for the report after the close on October 29 is whether the broader wave of AI-enabled hardware work, plus strong failure-analysis demand, can fill that gap without the growth rate visibly stalling.
The Street is looking for earnings of $0.60 a share, up about 9% from a year ago, on revenue of roughly $149.0 million, which would be growth of just 1.3%. That revenue figure sits well below management's own third-quarter range of $158.9 million to $161.8 million, and the 1.3% growth estimate is hard to square with the company's guide for net revenue growth of 8% to 10%. Some of the gap may come down to how pass-through reimbursable expenses are counted, since those inflated total revenue to $171.6 million last quarter against net revenues of $148.9 million. Either way, the published consensus does not look demanding relative to what the company has said. The Earnings Whisper of $0.64 is a more telling signal, sitting about 7% above consensus and suggesting the informal bar is closer to a repeat of the strong second quarter than a modest step up from last year's $0.55.
That second quarter set a high watermark. Net revenues rose 12%, EPS climbed 15%, utilization reached 74% versus 72% a year earlier, and management lifted full-year net revenue growth to 9% to 10% from high single digits, while nudging the EBITDA margin floor up to 27.8%. It also raised its realized rate outlook to 3.5% to 4%. A credible quarter now means net revenue growth landing inside, or ideally above, the 8% to 10% band even as the big study shrinks. The more convincing evidence would be breadth: new user research work across smart glasses, immersive devices and health wearables, early traction in FDA-regulated wearable studies, and continued reactive demand in data center cooling and power systems, ADAS and driver monitoring, chemicals and consumer products.
The softer points from last quarter remain the swing factors. Realized rate growth has cooled from 5% to 6% in the back half of 2025 toward about 4% as heavier hiring dilutes the mix, and management deliberately guided second-half utilization conservatively. If utilization holds near 74% while headcount grows, that conservatism will look like sandbagging and margins should benefit. If utilization slips and rate growth fades further, the raised margin floor gets harder to defend. Below the operating line, lower interest income from a cash balance drawn down by buybacks and a slightly higher tax rate of 28.5% shave a bit off EPS, which makes the whisper number more dependent on operating execution.
The market has already leaned toward the optimistic reading. Shares are up about 10.6% since the last report, beating the S&P 500 by more than 7 points, and at $72.55 the stock trades well above its 200-day average of $66.44 and within 2% of its post-earnings high of $73.83, effectively testing a breakout. The entire trading range has shifted higher from last quarter. Sentiment, meanwhile, is mildly bearish and essentially unchanged from the prior report, so the rally has not been accompanied by a surge in enthusiasm.
The narrative hinges on whether management can reaffirm, or lift again, its 9% to 10% full-year net revenue target once the outsized study contribution has normalized. Doing so would show the AI-in-physical-products story is a durable multi-year driver rather than one client's spending spike. A trim, or a fourth-quarter outlook that implies sharp deceleration, would leave a stock sitting near its highs with little cushion.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 52 min | |
| Oct-08 | |
| Sep-29 | |
| Sep-18 | |
| Jul-31 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-09 | |
| Jun-17 | |
| Jun-05 | |
| May-01 | |
| Apr-30 | |
| Apr-30 |
