Exponent Hits The Whisper And Raises Guidance Again, But Record Utilization Is Doing The Heavy Lifting
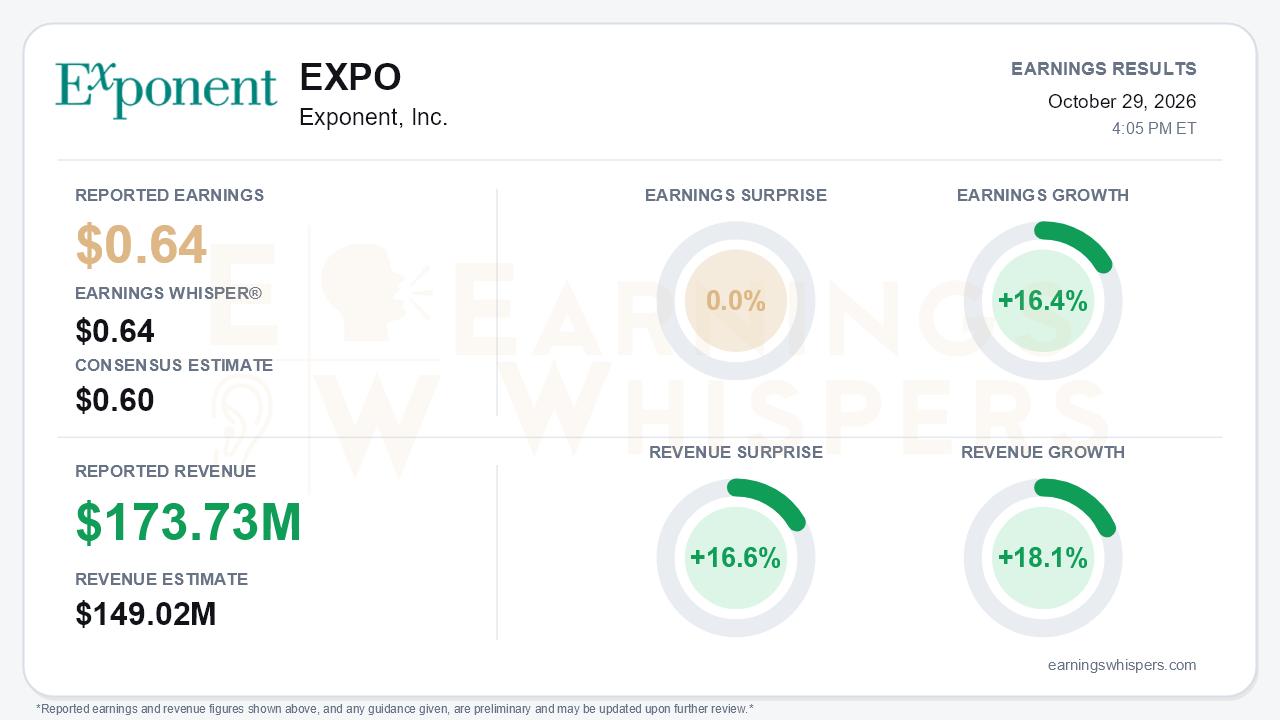
Exponent (NASDAQ: EXPO) earned $0.64 per diluted share in the third quarter. That was ahead of the $0.60 consensus but exactly matched the $0.64 Earnings Whisper number, so the result was in line with the expectations that mattered. Earnings grew 16.4% year over year. Total revenue of $173.73 million beat consensus by 16.6% and grew 18.1%. Management also raised full-year revenue and margin guidance again. The central takeaway is that Exponent is extracting more profit from a nearly fixed bench of consultants, with utilization reaching a multi-year high of 76.7%. That improves margins now, but it leaves less operating slack heading into a guided fourth-quarter slowdown.
The headline revenue figures need context. Reimbursements, which are pass-through costs, roughly doubled to $20.7 million from $10.0 million. That inflates total revenue and the size of the revenue beat. The better gauge is revenue before reimbursements, which rose 12% to $153.1 million. That still exceeded management's own 8-10% guide and ran ahead of the 11% year-to-date pace.
Operating results were strong:
- Operating income jumped to $41.9 million from $29.0 million.
- Compensation expense rose less than 3% while net revenue grew 12%, a direct result of the utilization gains.
- EBITDA rose to $45.0 million, and the 29.4% margin topped the 28.0-28.5% guide and improved from 28.7% in Q2 and 28.4% in Q1.
Below the operating line, the picture was weaker. Other income fell to $1.1 million from $9.6 million, as interest income shrank after heavy buybacks and miscellaneous income dropped sharply. Pretax income grew only about 11%. A diluted share count more than 5% lower closed the gap to 16% EPS growth.
The call supported the bullish operating narrative:
- **Demand mix:** Proactive work grew in the high teens. Reactive work grew in the high single digits against a tough comparison, with disputes spread across chemicals, consumer products and ADAS-related transportation.
- **Guidance:** Full-year net revenue growth guidance has now moved from high single digits to 9-10% to 10-11%. EBITDA margin guidance rose to 28.0-28.3%, utilization to 73.5-74%, and realized rate increases to 3.7-4%.
- **Costs:** G&A and capex guidance were trimmed.
- **AI exposure:** Management now puts AI as a direct element of roughly 15-20% of the business, up from about mid-teens earlier in the fiscal year. Executives described emerging reactive work in areas such as AI explainability, data center fires and wearable medical devices.
The tone was noticeably more confident, reinforced by the company's first Investor Day.
Bears still have legitimate ammunition:
- **Q4 slowdown:** Fourth-quarter guidance calls for net revenue growth of only 8-10% and an EBITDA margin of 26.3-26.8%, a clear deceleration and seasonal compression.
- **Large study ending:** A large user research study that contributed 4% of revenue in Q2 and 2.5% in Q3 falls below 1% in Q4.
- **Environmental & Health:** The segment slowed to 3% growth from 9% in Q2.
- **Headcount:** Average technical FTE growth slowed to 4% from 6%.
The headcount trend is the structural issue. Growth is being carried by utilization rather than capacity, and 76.7% leaves limited room to push further. Management says it has turned up recruiting dials, but 2027 pricing and headcount plans are still pending. The company also repurchased no stock in Q3 after spending $146.1 million on buybacks in the first half, which helped cut cash to $114.7 million from $221.9 million at the start of the year. That pause removes some of the per-share tailwind that flattered EPS growth.
The market setup is more demanding than the beat implies. Shares rallied 23% off a September 28 low of $62.55. Ahead of the report they traded at $77.11, up 17.6% since the open following the July report and about 15.9% above the 200-day moving average. They were just 1.7% below the inter-earnings high of $78.43 set three days earlier. In other words, the stock came into the print priced for a clean result, and the EPS figure landed precisely on the whisper rather than above it. Investor sentiment moved the other way. It remained negative and weakened modestly from -0.19 to -0.27, suggesting some investors were skeptical of the run despite the improving guidance trajectory. Earnings Whispers trend readings on price, momentum and AVWAP are positive, while the sequential-growth reading is only neutral, consistent with a business that is strong year over year but about to slow quarter to quarter.
The bottom line is that Exponent delivered a high-quality operating quarter and a credible growth story built on AI-related testing and diversified dispute work. However, the beat leaned on utilization gains, pass-through reimbursements and a shrinking share count, and the guide points to a softer fourth quarter. With the stock near the top of its range and the EPS result only matching the whisper, upside likely depends on whether hiring can restore capacity growth before peak utilization caps margin expansion.
Read our earnings preview for Exponent, Inc.: https://www.earningswhispers.com/article/EXPO/21190
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| Oct-21 | |
| Oct-08 | |
| Sep-29 | |
| Sep-18 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-09 | |
| Jun-17 | |
| Jun-05 |
