Medallion Financial Must Show Its Record Loan Growth Can Outrun The Provisioning Drag
Medallion Financial heads into its September-quarter report with an awkward but interesting problem: the faster it grows, the worse its near-term earnings look. Last quarter delivered one of the strongest origination periods in the company's history, a higher dividend and a stepped-up buyback, yet reported profit fell sharply because accounting rules force lenders to book expected losses the day a loan is made. The question for the report after the close on October 29 is whether that growth engine is still running hard, and whether investors are starting to see the earnings power behind it.
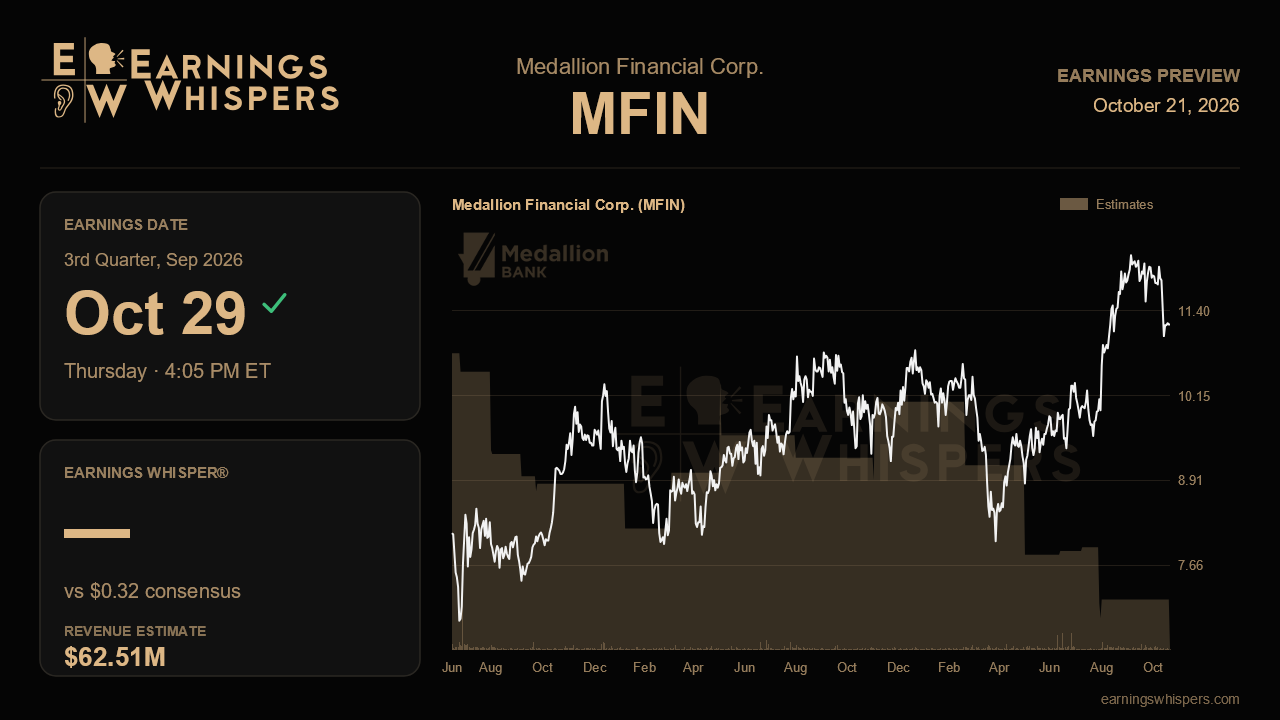
The Street is not asking for much on the bottom line. Consensus calls for earnings of $0.32 a share, roughly 30% below the $0.46 earned a year ago and barely above last quarter's $0.31. Revenue is pegged at $62.5 million, about 25% below the year-ago figure. That headline contraction looks harsh, but the more useful yardstick is net interest income, which climbed to $57.2 million last quarter from $54.1 million the quarter before. A flat-looking EPS estimate effectively assumes growth costs keep eating most of the incremental lending income.
That assumption deserves scrutiny. Management estimated that roughly $6.5 million of day-one provisioning shaved about $0.18 off last quarter's results, up from around $2.5 million in the prior period. Strip that out and the underlying run rate looked closer to the year-ago level. The September quarter has historically been a strong one for recreation lending, so another heavy origination quarter would likely mean another sizable provisioning charge. The swing factor is the new recreation loan-sale channel, which moved about $50 million of loans for a $1.3 million gain last quarter and was described as recurring. If that outlet repeats at similar scale, it can partly offset the provisioning hit while freeing capital for the buyback.
The narrative from the last call holds up if loan growth stays on pace with management's reaffirmed target of mid-teens growth and roughly 10% asset growth toward a $5 billion goal, if home improvement originations keep benefiting from a contractor network that expanded from 700 to 800, and if home improvement charge-offs stay near last quarter's improved 1.37%. It weakens if recreation charge-offs, already elevated at 3.14%, drift higher, since management has been deliberately pricing those loans more competitively. That pricing choice has pushed the net interest margin down for several straight quarters, to 7.94% from 8.21% a year earlier. Another modest slip would be consistent with the plan; a sharper decline, especially with deposit costs near 4%, would raise doubts about whether the company is buying growth too cheaply. Operating costs, which jumped to $25 million as new home improvement talent arrived, also need to show signs of leveling off.
The market has already leaned toward the optimistic reading. Shares have gained about 13% since the last report, nearly nine points ahead of the S&P 500, and trade comfortably above the 200-day moving average. The post-earnings range of $9.81 to $12.26 sits entirely above the prior quarter's band, though at $11.20 the stock is well off its recent high rather than pressing a breakout. Sentiment has improved modestly, to 20% bullish from 14.5%. Notably, the stock still trades below tangible book value of $12.17 a share, which helps explain management's appetite for repurchases with only about $6 million left on the current authorization.
Ultimately, this report hinges on quality of growth rather than the EPS print itself. If originations remain robust, credit holds steady and the loan-sale channel proves repeatable, a soft headline number can be read as an investment in future earnings. If credit or margins crack while provisioning stays heavy, the patience the market has shown will be harder to justify.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-19 | |
| Oct-15 | |
| Sep-30 | |
| Sep-23 | |
| Sep-22 | |
| Sep-22 | |
| Jul-30 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-08 | |
| Jun-12 | |
| Jun-10 |
