Medallion Financial's Growth Engine Runs Hot As Provisions And NIM Compression Crush EPS To $0.10, Far Below Its $0.14 Dividend
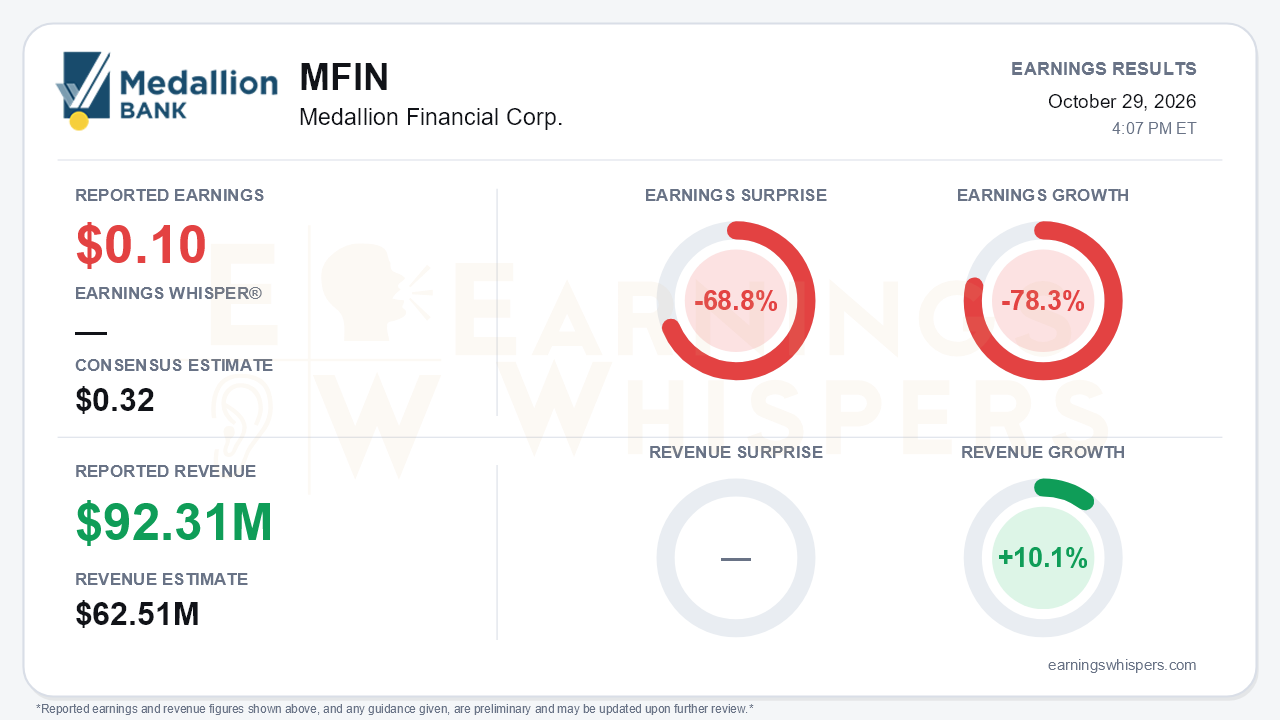
Medallion Financial delivered a quarter in which almost everything grew except earnings. The specialty lender reported third-quarter EPS of $0.10, missing the $0.32 consensus by 68.8%, and earnings fell 78.3% from a year ago. Revenue of $92.31 million grew 10.1% and topped the $62.51 million consensus by 47.7%. That revenue beat deserves context. The reported figure reflects gross interest and other income, while net interest income, the line that matters more for a lender, grew only 5% to $58.4 million. The central tension is clear. Management is buying balance-sheet growth with current earnings, and in the third quarter the price of that growth rose sharply.
The quality of the miss is mostly a story about provisioning and margin. Credit loss provision jumped to $30.8 million from $18.6 million a year earlier and $22.3 million in the second quarter. Roughly $5.6 million of that was day-one reserving on new loans, which management has repeatedly framed as the accounting cost of growth. That explanation only covers part of the increase. According to the call, another $4.7 million came from raising coverage ratios: recreation reserves rose to 5.30% and home improvement to 2.59%. Consumer net charge-offs also climbed to 2.84% from 2.55%. Recreation loans 90 days or more past due increased to 0.66% from 0.57%. These are not alarming levels for a subprime-leaning recreation book, but they are moving the wrong way. Pretax income fell to $7.1 million from $19.5 million, and other expenses rose about 16% year over year, partly on higher loan servicing fees.
Margin pressure compounds the credit story. Net interest margin fell to 7.34%, down from 7.94% in the second quarter, 8.00% in the first and 8.21% a year ago. Average loan yield slipped 52 basis points to 11.87%. The home improvement new-origination coupon slid to 9.14% from 10% in the first quarter. Meanwhile, cost of interest-bearing liabilities rose to 4.45% from 4.32% in the prior quarter, and excess cash from a notes offering diluted returns. Management said NIM may decline a little further before planned fourth-quarter rate increases take hold.
The growth side of the ledger is genuinely strong. Originations rose 41% to $603.9 million, and home improvement volume surged 145% to $146.3 million. The total loan book grew 15% to $2.936 billion, ahead of the roughly 10% growth discussed earlier in the year. Medallion added rFinance, the finance affiliate of Renewal by Andersen, as its sixth strategic partner and its first captive finance relationship. It also completed its first home improvement loan sale in years, about $40 million at a roughly 3% gain. Funding diversification also improved:
- Non-brokered time deposits rose to $117.5 million from $27.2 million.
- High-yield savings grew to $101 million from $2.5 million.
On capital, the company raised $55 million of bank preferred stock and retired $15 million of trust preferred at a discount, which will produce a fourth-quarter gain. The board also authorized a fresh $40 million buyback after Medallion exhausted the prior one.
The forward framing turned more guarded. Management described the environment as different from six months ago and characterized 2027 growth as economy-dependent, a shift from the second quarter's language about sustainable volumes. Pipelines are off their peak, the fourth-quarter rate hikes are expected to slow originations, and no loan sale is scheduled for the fourth quarter. Bears have legitimate ammunition on the dividend as well. EPS of $0.10 now sits well below the $0.14 quarterly payout, and management signaled that growth takes priority over near-term coverage.
The market setup is more complicated than the miss implies. Shares have risen 18.1% since the open following the July report, to $11.68, and trade about 13.7% above the 200-day moving average of $10.27. The stock still sits below book value of $17.73 per share and only modestly above tangible book of $12.17. That gap helps explain the aggressive buyback at an average cost of $11.48. Investor sentiment remained positive but softened slightly, slipping from 0.145 to 0.116, a modest cooling rather than a capitulation. Price trend readings are neutral, while AVWAP remains positive, suggesting buyers have not abandoned the stock.
The bottom line is that Medallion's third quarter exposed the cost of its growth strategy more starkly than before. Day-one provisions alone do not explain the earnings collapse. Higher reserve coverage, rising charge-offs and a 60-basis-point sequential NIM drop all contributed. The franchise continues to expand its book, partnerships and funding base, and the fourth quarter should benefit from the trust preferred gain and repricing. Investors will now need evidence that margins stabilize and credit costs plateau before the volume story translates back into dividend-covering earnings.
Read our earnings preview for Medallion Financial Corp.: https://www.earningswhispers.com/article/MFIN/21216
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-21 | |
| Oct-19 | |
| Oct-15 | |
| Sep-30 | |
| Sep-23 | |
| Sep-22 | |
| Sep-22 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 |
