Ingram Micro's Raised Outlook Faces Skeptical Market As Margin Mix And Cash Flow Loom
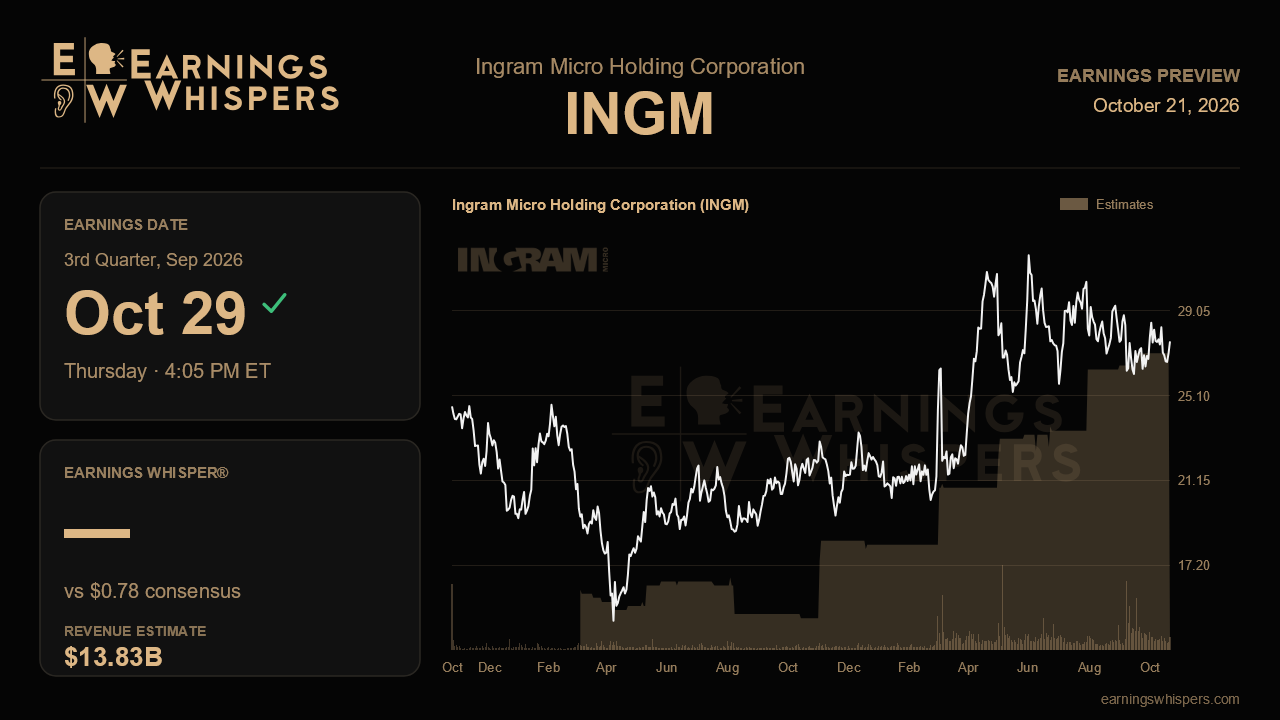
Ingram Micro enters its third-quarter report with an unusual disconnect. Three months ago, management delivered record second-quarter results above its own guidance, raised every forecast metric and described the outlook as its strongest quarterly guidance yet. Since then, the stock has fallen 8.4% while the S&P 500 gained 3.3%, and sentiment has swung from mildly bullish to clearly bearish. The October 29 release, due after the close, has to show whether that skepticism reflects something real in the business or simply impatience with a distributor whose growth story still comes with thin margins and lumpy cash flow.
The Street is looking for earnings of $0.78 per share on revenue of $13.83 billion, which would be growth of roughly 8% and 10%, respectively. Both figures sit slightly above the midpoints of management's guidance of $0.72 to $0.82 per share and $13.55 billion to $13.95 billion in revenue, so analysts are leaning modestly toward the upper half of the range rather than demanding a blowout. The slower earnings growth deserves context. Second-quarter EPS jumped 34%, but the year-ago third quarter was a tougher comparison at $0.72, so a high single-digit gain is less a sign of fading momentum than a reflection of the base. Still, after a quarter that cleared the top of guidance, a print merely at consensus could feel underwhelming.
The most important test is whether last quarter's breadth holds up. Management highlighted double-digit growth across every line of business, every region and every customer category, with Asia-Pacific up 28%. It also said visibility and predictability had improved, a notable softening from earlier caveats about price elasticity and deferred projects. Confirmation would look like continued broad-based growth rather than a quarter carried by one region or by AI infrastructure deals. A challenge would emerge if the earlier warning signs resurfaced, particularly advanced-solution deals slipping because of supply constraints or small and midsize customers splitting large projects into smaller phases.
Margins are the swing factor. The gross profit guide of $910 million to $955 million implies roughly a 6.8% gross margin, even as GPU-heavy AI deals diluted gross margin by about 30 basis points last quarter and lower-margin Asia-Pacific grows faster. Ingram's bull case rests on operating leverage, which pushed adjusted operating income up 40% last quarter, offsetting that mix drag. If gross profit lands near the low end while revenue beats, the market may conclude growth is getting more expensive. Evidence that the Xvantage platform is lifting efficiency would help: its intelligent digital assistant generated about $1 billion, or 7% of revenue, last quarter against a double-digit year-end target, and progress toward that goal is worth checking.
The newer catalysts also need early proof. HPE named Ingram one of two global distribution partners, the Google Cloud relationship expanded, and the AI enablement programs reported sharp gains in customer engagement. It is too soon for these to transform results, but commentary showing they are converting into orders would support the idea that the guidance raises were built on durable share gains. Cash flow remains the other overhang after outflows of $962 million and $527 million in the first two quarters, with management pointing to a strong fourth quarter similar to last year's $1.6 billion inflow. Any sign of that turn beginning would ease a key worry.
Technically, the stock at $27.07 sits above its 200-day moving average of $26.10 but in the lower half of its post-earnings range of $25.68 to $29.81, well short of a breakout. With sentiment soured, the bar for a relief move may be lower than the operating story suggests. Ultimately, the report hinges on whether Ingram can keep growing near double digits while holding gross margin steady enough for operating leverage to do its work. If it can, last quarter's confident narrative stays intact; if mix pressure starts eating the gains, the market's doubts will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-19 | |
| Oct-12 | |
| Sep-15 | |
| Sep-15 | |
| Sep-15 | |
| Sep-08 | |
| Sep-08 | |
| Sep-01 | |
| Aug-24 | |
| Aug-03 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-16 |
