Healthcare Realty's Steady Execution Meets A Skeptical Market As Shares Slide 18%
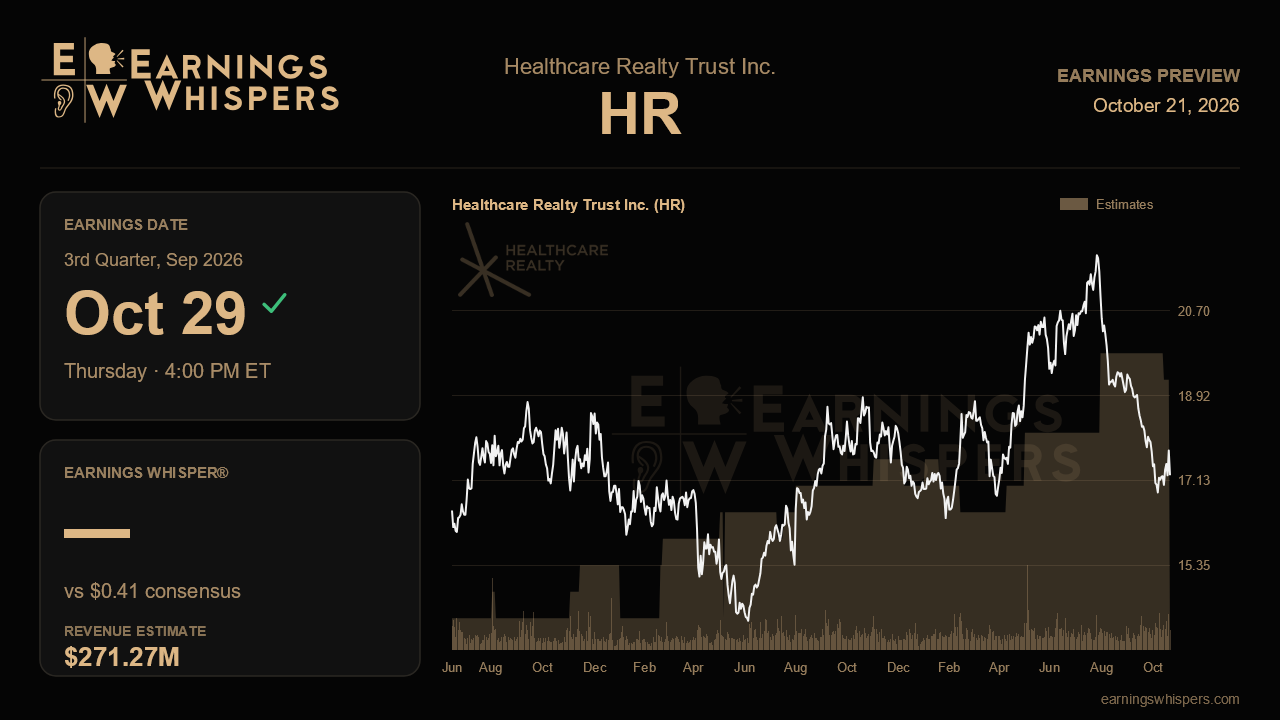
Healthcare Realty Trust has spent four straight quarters raising its outlook, refinancing debt on better terms than planned and finding accretive ways to redeploy capital. The stock has responded since the last report by falling nearly 18% while the S&P 500 gained about 3%. That gap is the central tension heading into the third-quarter release after the close on October 29. The operating story has not visibly cracked. The market, however, is acting as if it might, or as if higher interest rates will eventually make the improvement irrelevant.
The Street expects funds from operations of $0.41 per share, matching both the prior quarter and the year-ago period. Revenue is projected at $271.3 million, down 8.9% from a year earlier and below the $281.8 million reported last quarter. The revenue decline should not be mistaken for operating weakness. It largely reflects the company's deliberate shrinking through asset sales and contributions to its joint venture with KKR, which move income off the consolidated top line. Flat per-share earnings on a smaller revenue base is roughly what a capital-recycling plan looks like midstream. Full-year consensus FFO of $1.63 sits just below the midpoint of management's raised $1.62 to $1.66 range. Analysts, in other words, have not fully followed the guidance higher, which leaves room for a modest upside surprise if the quarter lands on plan.
The most important operating number is same-store cash NOI growth. It slowed from 6.9% in the first quarter to 5.1% in the second, and management attributed the cooling to fading occupancy comparisons rather than softer demand. It framed a stabilized run rate near 4%. The full-year target of 4.25% to 5.0% implies the back half runs below the first-half pace, so a third-quarter print in the 4% area would validate the story rather than undermine it. A drop meaningfully below that would raise the question of whether the slowdown is more than arithmetic. Occupancy, which crept up to about 92.7%, should benefit from roughly 460,000 square feet of signed-but-not-yet-occupied leases, worth about 140 basis points. Continued progress there, plus leasing volume that holds up after the second quarter's dip from a record first quarter, would support management's view that internal growth is normalizing, not rolling over.
Capital allocation is the second test. Last quarter, KKR joint venture activity jumped to about $200 million closed or under contract at roughly a 7.5% cash yield. Redevelopment reached 67% leased at yields near 10%, and the health-system deals with Ascension St. Thomas, CommonSpirit and WellStar came with specific spreads and pricing. This quarter should show whether that pipeline keeps expanding or stalls. Management itself flagged that the recent back-up in rates could eventually pressure transaction cap rates. Any sign that buyers or sellers are repricing, or that JV deal flow is slowing, would hit the part of the story the market seems most worried about.
The share price adds a twist. At $17.76 the stock trades below its 200-day moving average of $18.79 and sits closer to its post-earnings low of $16.83 than its $21.66 high. It is also now below the roughly $18.50 average price the company paid for $175 million of buybacks. Management had steered capital away from repurchases after the stock re-rated, so its posture on buybacks at these levels will be telling. Sentiment has swung from mildly bullish before the last report to clearly bearish now, which lowers the emotional bar even as the operational bar remains elevated after repeated raises.
Ultimately, the report needs to show that the deceleration in same-store growth is settling near 4% and that accretive deal flow is surviving higher rates. If both hold, along with another nudge to guidance or a firm reaffirmation, the gap between execution and the stock price becomes hard to justify. If either slips, the market's skepticism will look prescient.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-12 | |
| Oct-05 | |
| Jul-31 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-07 | |
| May-05 | |
| May-04 | |
| May-02 | |
| May-01 | |
| Apr-30 | |
| Apr-30 | |
| Apr-08 |
