Healthcare Realty's Third Guidance Raise And Record Leasing Spreads Collide With A 16% Slide And Souring Sentiment
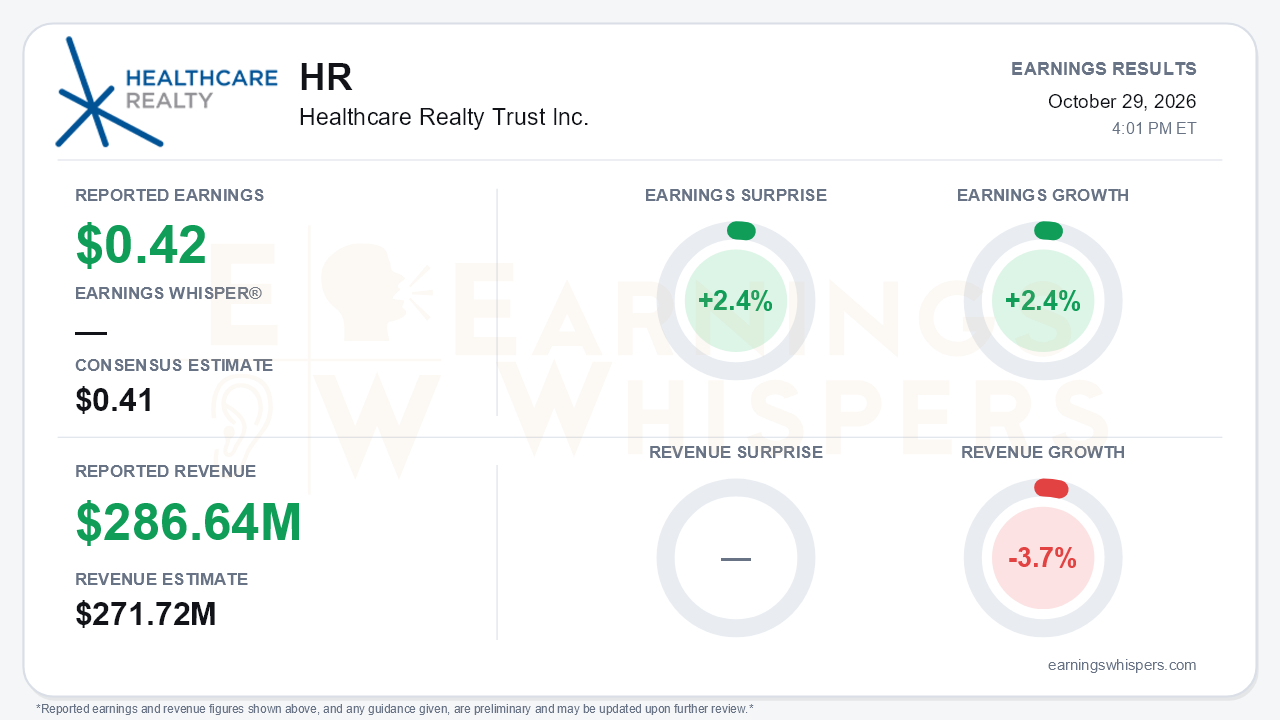
Healthcare Realty Trust (NYSE: HR) reported third-quarter normalized FFO of $0.42 per share. That beat the $0.41 consensus by 2.4% and was 2.4% above the year-ago quarter. Revenue of $286.64 million topped expectations by 5.5% but fell 3.7% year over year as the company kept shrinking its portfolio through dispositions. Management raised 2026 normalized FFO guidance for the third time this year, to $1.65-$1.67, and lifted same-store cash NOI guidance to 5.00%-5.25%. Property fundamentals are clearly firming. The stock, however, has fallen 16% since the last report, and that disconnect is the central tension.
The quality of the beat deserves scrutiny. Normalized FFO dollars were essentially flat at $145.9 million versus $145.3 million a year ago. Per-share growth came largely from a diluted share count that fell to 345.6 million from 354.7 million, helped by $250 million of year-to-date buybacks. Rental income declined to $277.6 million from $287.4 million as assets were sold. Lower interest expense and leaner G&A did much of the work beneath the line. On a GAAP basis, the net loss narrowed to $(0.05) per share from $(0.17), mainly because impairments dropped to $16 million from $104 million. Cash flow is the softer spot. FAD slipped to $110.2 million from $116.9 million and has been stuck at $0.32 per share for several quarters. Straight-line rent adjustments nearly doubled to $12.3 million, and maintenance capital rose. The 76% payout ratio leaves dividend coverage intact but not expanding.
The operating story is stronger than the headline growth rate suggests. Cash leasing spreads jumped to 8.6%, the highest in nearly a decade, up from 3.7% in Q4 2025, 4.2% in Q1 and 4.8% in Q2. Management noted spreads were still above 6% excluding the Ascension deal. Same-store occupancy climbed to 93.1% from 92.3% in Q1, and retention held at 88%. New leasing rose to 430,000 square feet from 350,000 in Q2. The Ascension St. Thomas letter of intent flagged last quarter became signed leases on 203,000 square feet in Nashville. Those leases come alongside a $35 million West Campus redevelopment tied to Ascension's $120 million hospital investment. Redevelopment leasing nearly doubled, lifting that portfolio to 72% leased from 67%. Management's tone was notably confident. It described outpatient migration as accelerating, with escalators now at a 3% floor and some deals approaching 4%.
Bears still have legitimate ammunition. Same-store cash NOI growth of 5.1% matched Q2 but trailed Q1's 6.9%. The guidance also implies a Q4 slowdown on lower forecast absorption and a tough comparison. Total leasing volume of 1.5 million square feet was flat with Q2 and below Q1's 2 million. Tenant improvement costs ticked up on redevelopment leases, and 3.1 million square feet expires in 2027. Management cautioned that higher rates may slow transaction volumes and that cap rates are widening for weaker assets, though core assets are holding at 5.5%-6%. Phoenix and parts of Texas remain soft. The remaining NOI recapture is weighted toward 2027-28, which asks investors for patience. On the capital side, the KKR joint venture is buying at mid-7% yields. Disposition guidance rose by $85 million, more than $100 million of additional sales are under contract or LOI, and management signaled interest in adding JV partners.
The market has not been rewarding the improving fundamentals. Shares have fallen to $18.13 from $21.58 at the open after the July report and sit 3.7% below the 200-day moving average of $18.82. Investor sentiment swung decisively, from a modestly positive 0.19 to a negative -0.30. That is a meaningful shift and suggests rate pressure on REITs has overwhelmed the company-specific progress. The Earnings Whispers price and AVWAP trend readings are both negative, consistent with that pressure. Notably, management has been repurchasing stock at an average of $17.74, close to where shares now trade, and renewed a $500 million authorization.
The guidance raise itself was described as in line with estimates. The improvement was largely anticipated by analysts, even as investors grew more pessimistic. That leaves HR with a fundamentals-versus-macro standoff rather than an earnings problem.
The bottom line is that Healthcare Realty delivered a quarter of steadily improving property-level economics, led by record leasing spreads, rising occupancy and a third guidance increase. Headline growth, however, remains modest because dispositions are shrinking revenue and buybacks are carrying per-share gains. The flat FAD trend, the implied Q4 same-store slowdown and back-end-weighted recapture give skeptics reasons to wait. A shift in rates or proof that leasing spreads can turn into cash-flow growth will likely matter more for the shares than this quarter's beat.
Read our earnings preview for Healthcare Realty Trust Inc.: https://www.earningswhispers.com/article/HR/21203
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-21 | |
| Oct-12 | |
| Oct-05 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-07 | |
| May-05 | |
| May-04 | |
| May-02 | |
| Apr-30 | |
| Apr-30 |
