ResMed's 18% Rally Meets A Thin Quarter As Astral And Margin Pressure Weigh
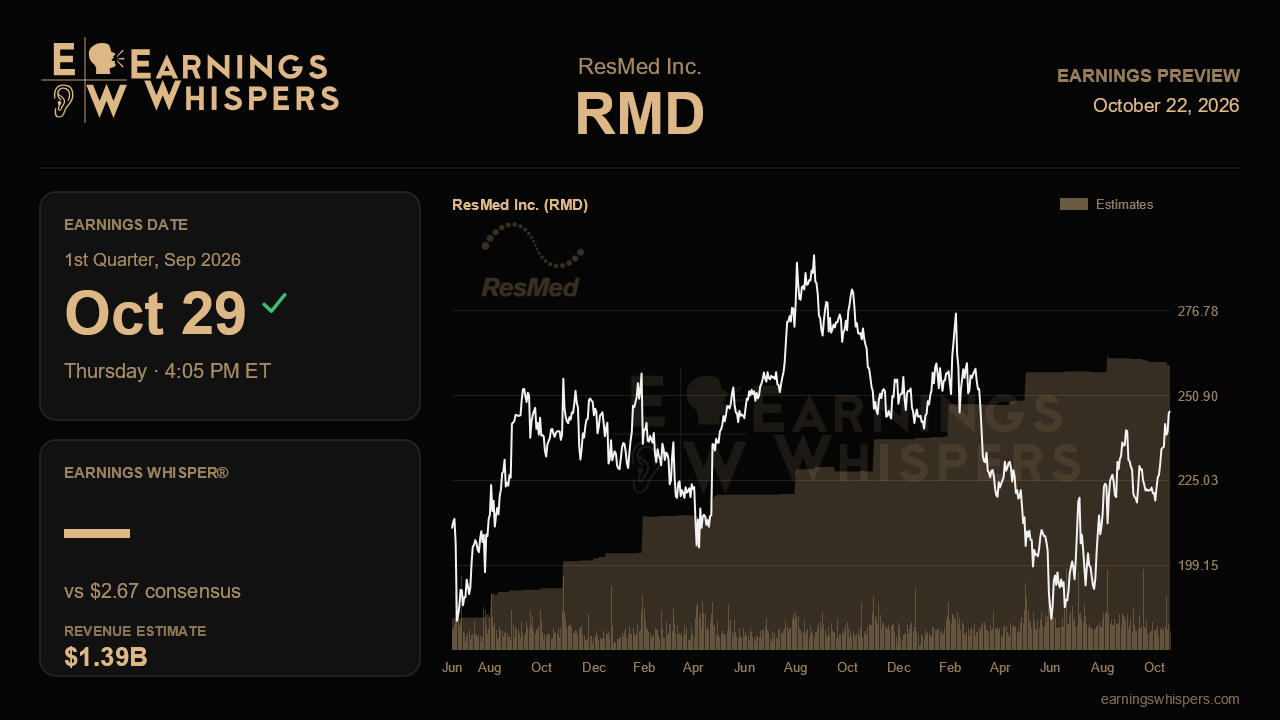
ResMed heads into its fiscal first-quarter report with a stock that has already moved on. Shares have climbed nearly 19% since the last report while the S&P 500 barely budged, even though management used that call to reset expectations lower. The company issued its first formal outlook for fiscal 2027 at 5% to 7% core constant-currency growth, below the high-single-digit language it had repeated for years. It also warned that gross margin would dip slightly year over year this quarter. The market chose to look through the noise. This report will show whether that patience was justified.
The Street is not asking for much. Consensus calls for earnings of $2.67 per share on revenue of about $1.39 billion. That works out to growth of roughly 4.7% and 4.1% from the year-ago $2.55 and $1.34 billion. It is also a clear step down from the $2.95 and $1.46 billion posted last quarter. Modest growth is the expected outcome, not a red flag. Three headwinds explain the gap:
- The Astral ventilator suspension, which management pegged at about $75 million of revenue and $0.15 of EPS for the year.
- Combined dilution of about $0.50 from the MatrixCare divestiture and the Noctrix acquisition.
- Rising costs for electronic components and freight, which management said now outpace productivity gains.
Revenue growth in the low single digits fits the reported math. The tougher test is whether core sleep growth still looks consistent with a 5% to 7% year once Astral and the portfolio changes are stripped out.
That makes the sleep franchise the heart of the report. Last quarter, sleep devices grew 8% in the Americas and 13% in the rest of the world, with masks up 10% to 12%. Both beat the mid-to-high-single-digit market growth management cites. Several things would confirm the narrative:
- Similar device and mask growth this quarter.
- An update on the GLP-1 patient cohort, which grew to 2.5 million with an 11% higher rate of starting PAP therapy.
- Early evidence that wearable partnerships are bringing in new patients. The Aura ring is the first test, since about three quarters of assessed users had never been diagnosed.
If instead sleep devices slide toward market-rate growth, the lower guidance starts to look like a real slowdown rather than a temporary hit the company caused itself.
Margins are the second swing factor. Gross margin was 62.3% last quarter, and operating margin slipped to 35.2% from 36.7% in the March quarter. Management has already conceded a slight year-over-year gross margin decline. A dip that is merely slight, with operating expenses held in check, would support the claim that core EPS can grow 12% to 14% excluding Astral. A deeper drop would raise doubts about whether component inflation is truly contained. This is also the first full quarter under new CFO Aaron Bloomer, so any comments on the pending capital structure review deserve attention. The company has promised more than $1.85 billion of capital returns this year, including a $450 million accelerated share repurchase. Progress on that plan matters given the weaker fourth-quarter free cash flow of $404 million.
Sentiment has warmed but remains cautious. Earnings Whispers readings sit at 29.1% bearish, versus 41.9% bearish before the last report. Technically, the stock trades well above its 200-day moving average of about $225. At $246.20, it is pressing against its post-earnings high of $248.60. The whole trading range has moved about $20 above the prior quarter's band. A stock testing a breakout into a seasonally soft, guided-down quarter leaves little room for surprises on margins or Astral.
The question is simple. Does underlying sleep demand remain strong enough to make fiscal 2027's softer headline numbers look like a pause rather than a downshift? Healthy device and mask growth, contained margin erosion and no new Astral surprises would validate the rally. Any sign that demand is cooling alongside cost pressure would challenge the idea that this year's weaker growth is only temporary.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 10 hours | |
| Oct-19 | |
| Oct-01 | |
| Sep-28 | |
| Sep-28 | |
| Sep-15 | |
| Sep-15 | |
| Aug-27 | |
| Aug-25 | |
| Aug-19 | |
| Aug-17 | |
| Aug-10 | |
| Aug-07 | |
| Aug-07 | |
| Aug-06 |
