ResMed Beats On Margin And Buybacks, But Unchanged Guidance Signals A Steady Rather Than Accelerating Year
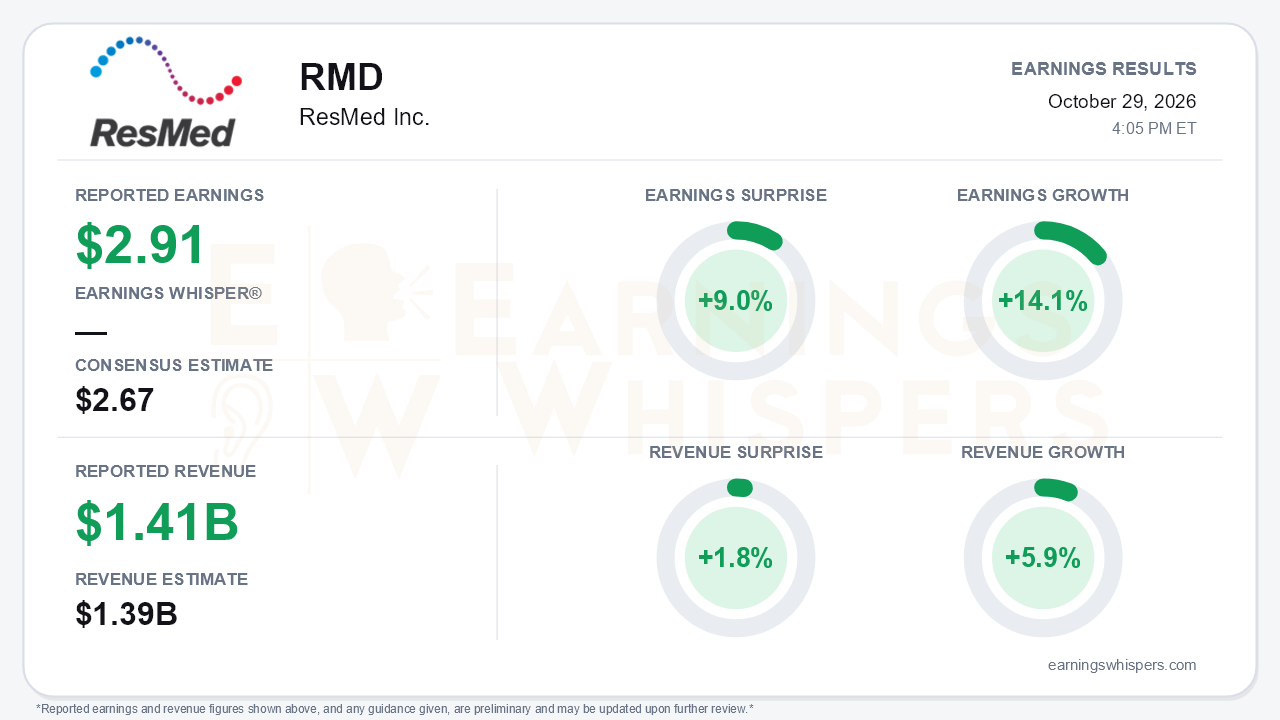
ResMed opened fiscal 2027 with a clean beat on the numbers that matter most to the Street. Non-GAAP EPS of $2.91 topped the $2.67 consensus by 9.0% and grew 14.1% year over year, while revenue of $1.415 billion beat the $1.39 billion estimate by 1.8% and grew 5.9%. The central tension is that management did not raise anything. Revenue guidance of 5% to 7% core constant-currency growth and non-GAAP EPS guidance of $12.00 to $12.25 were simply reiterated. Management also said the midpoint remains the most likely outcome. That makes this a strong quarter inside an unchanged year, not a reset higher.
The quality of the beat deserves scrutiny. Non-GAAP gross margin rose 50 basis points to 62.5%, which was better than the slight year-over-year contraction management had guided for the quarter. The company credited productivity gains and the timing of Indiana expansion costs. That margin did not carry through to operating profit. Non-GAAP R&D rose 16%, and non-GAAP operating margin slipped 30 basis points to 35.8%. Non-GAAP operating income grew only 5%. The gap between that 5% and 14% EPS growth was closed below the operating line:
- Net interest income roughly doubled to $16 million.
- Diluted shares fell about 2.4% to 143.4 million.
GAAP EPS of $2.92 was flattered by a $0.38 gain on the MatrixCare divestiture. Restructuring, amortization and deal costs largely offset that gain. Growth also cooled modestly. Core constant-currency revenue growth of 7% compares with 8% in the year-ago quarter, and reported growth slowed to 6% from 9%.
Beneath the consolidated figures, the core sleep franchise remains healthy. Total sleep revenue grew 9% in core constant currency. Masks rose 10% in the Americas and 11% in the rest of the world, while rest-of-world devices jumped 13%. Residential Care Software excluding MatrixCare grew 8%, consistent with the high-single-digit target. The weaker data point is in the most important market. Americas sleep device growth slowed to 6% from 8% in the fourth quarter. Rest-of-world strength was partly driven by a fleet renewal in France, which management expects to become a second-half headwind. Life support revenue has nearly vanished, down 94% in the Americas. Astral is now permanently discontinued rather than merely suspended for the year.
The call did preserve a credible growth story built around patient funnels and adherence:
- **Referrals:** Oura referrals more than doubled sequentially to roughly 28,000.
- **Consumer partnerships:** A new Eight Sleep partnership adds to the funnel.
- **Digital engagement:** The Dawn GenAI coach handled 2.1 million inquiries, up 40% quarter over quarter.
- **GLP-1 data:** The GLP-1 claims cohort expanded to 3.3 million patients. The three-year resupply uplift improved to more than 7% from more than 6%.
- **Products:** Fabric masks and SmartComfort AI showed measurable compliance gains, which matters for resupply economics.
Management also conceded that its marketing programs have not yet contributed materially. These are leading indicators, not yet revenue drivers.
The forward risk list is longer than the beat implies:
- Management guided second-quarter gross margin down roughly 30 basis points sequentially as the Indiana costs arrive.
- Electronic component inflation is expected to build through the year.
- The assumed FX headwind to revenue widened to about 60 basis points from about 50.
- Free cash flow fell 10% to $374 million on an inventory build and cash tax prepayments.
- Competitive pressure is a watch item, given potential Philips re-entry and React Health in U.S. devices.
- Management acknowledged that oral GLP-1 patients may show different adherence or efficacy.
On the other side, capital return was exceptional. More than $1 billion went back to shareholders, including $936 million of buybacks funded partly by MatrixCare proceeds. Management also flagged a stranded-cost and transformation program, with benefits to be detailed in coming quarters.
The market setup is more complicated than the surprise implies. Shares have climbed 22% since the open after the August report, to $252.83, and sit about 12% above the 200-day moving average. Price and AVWAP trend readings are positive. Yet Earnings Whispers investor sentiment remains negative, improving only modestly from -0.42 to -0.37. Investors have bid the stock up without fully embracing the story. A report that beats but reiterates guidance may not do much to change that ambivalence.
The bottom line is that ResMed delivered a high-quality top line and a gross-margin surprise. The EPS beat, however, leaned heavily on interest income, a lower share count and favorable cost timing rather than operating leverage. Bulls get steady 7% core growth, expanding patient funnels and aggressive buybacks. Bears have legitimate ammunition in the Americas device slowdown, the coming France and margin headwinds, and management's decision to hold guidance rather than raise it after a strong rally.
Read our earnings preview for ResMed Inc.: https://www.earningswhispers.com/article/RMD/21238
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-29 | |
| Oct-29 | |
| Oct-22 | |
| Oct-19 | |
| Oct-01 | |
| Sep-28 | |
| Sep-28 | |
| Sep-15 | |
| Sep-15 | |
| Aug-27 | |
| Aug-25 | |
| Aug-19 | |
| Aug-17 | |
| Aug-10 |
