NVE's Q2 Slump Follows A Q1 Pull-Forward, And A Rare Flat Second-Half Outlook Now Carries The Story
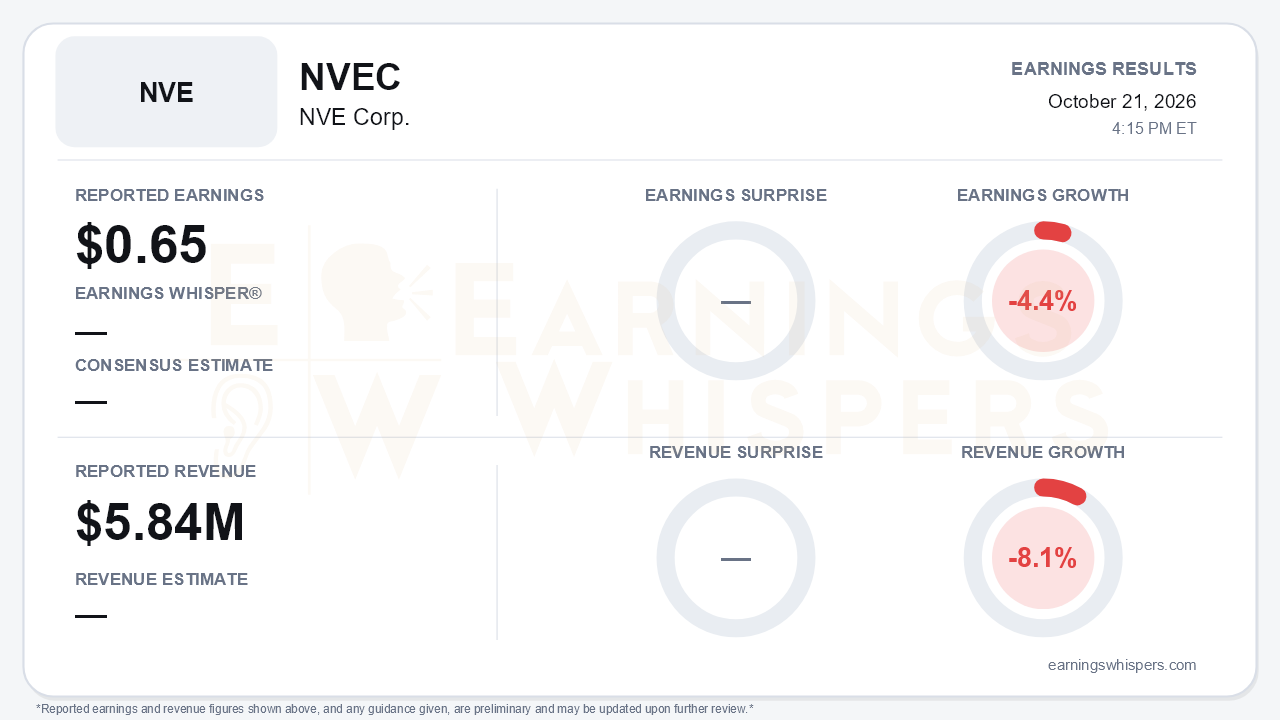
NVE Corp. (NASDAQ: NVEC) gave back much of its blowout first quarter in the September period. EPS was $0.65 on revenue of $5.84 million. Earnings fell 4.4% year over year and revenue fell 8.1%. That is a sharp reversal from Q1 FY27, when revenue was $11.0 million (+81%) and EPS was $1.32. No consensus figures were available, so the quarter has to be judged on its own trajectory. The central question is whether Q1 marked a new, higher plateau for a company that historically ran at $6-7 million a quarter, or whether it was mostly pulled-forward demand. The answer looks like some of both. Management's unusually explicit outlook calls for second-half revenue consistent with the first half's $16.9 million. That implies roughly $8.4 million per quarter: well above Q2, but clearly below Q1.
The quality of the quarter deserves scrutiny, because the bottom line looked better than the operations.
- Operating income fell to $3.21 million from $3.66 million a year earlier, and pretax income fell about 11%.
- Net income declined only 4%, because the tax provision dropped to roughly 14% of pretax income from about 20%, which management credited to favorable tax law changes.
- Gross margin slipped to 78% from 81.3% in Q1, as the mix shifted toward lower-margin distributor sales.
- SG&A jumped 44% year over year to $630,000 on director option grant costs.
- A 17% cut in R&D expense, attributed to staff redeployment, partly offset that increase.
Operating margin compressed to 55% from 66% in Q1 and 62% in Q4 FY26. Those are still exceptional levels, but the direction is unmistakably down. The first half remains strong: revenue rose 36%, net income rose 39% to $1.97 per diluted share, and operating cash flow reached $11.1 million versus $8.0 million a year earlier.
The call explained the shortfall in two parts. First, a large medical device customer pulled orders into Q1 from Q2 and is working through a short-term inventory adjustment. Second, and more troubling, defense product sales collapsed 95% year over year. On the Q4 FY26 call, management had expected defense sales to rise significantly this fiscal year, so that is a credibility hit on a forecast the company itself put forward.
The offset was genuinely encouraging. Distributor sales rose 67% year over year in Q2, accelerating from about 40% for the first half, and management tied that to strengthening industry conditions. Contract R&D revenue rose 25%. Those trends suggest the broader commercial and semiconductor base is improving even as NVE's concentrated customers turn lumpy.
The forward catalysts lean toward robotics. NVE launched its smallest product yet, a 0.55mm-square wafer-level chip-scale analog sensor, along with a family of seven gear sensors aimed at encoders and servos in industrial and humanoid robots. Wafer-level design wins are moving from samples toward low-thousand quantities, and expansion capacity is starting to shift from R&D to production. Investors should keep the scale in perspective. Management sized humanoid content at tens of sensors per robot at $1-2 apiece, and production timing remains uncertain. This is option value, not a near-term revenue driver.
The bear case is equally concrete. Customer concentration persists, defense visibility proved poor, and the distributor-led mix is diluting gross margin. The completed CEO transition, with Peter Eames as CEO and Dan Baker as chairman, plus a board expanded from five to seven directors, adds governance continuity, though those expanded board grants are part of the SG&A step-up.
Capital return is also near a ceiling. The $1.00 quarterly dividend matched first-half EPS of $1.97 almost exactly, and retained earnings dipped slightly from March. Payout capacity rests on continued strong cash generation and a $44.4 million cash and securities balance, up from $43.9 million in Q1.
Market context is thin this cycle, with no current price or sentiment reading available. The shares opened at $107.36 after the July report, well above the 200-day moving average of $90.01. That reflects how much enthusiasm Q1 had generated. A Q2 that falls back toward the old run rate tests that enthusiasm, and second-half guidance now does most of the work in defending it.
The bottom line is that NVE's second quarter was weaker than its EPS suggests, with a tax-rate cushion masking double-digit declines in operating and pretax income and clear margin compression. The pull-forward narrative is plausible, and accelerating distributor demand supports a recovery thesis. However, the defense miss and the gap between implied H2 run rates and Q1's peak argue for tempered expectations. Delivering roughly $8.4 million per quarter in the second half is now the bar that matters.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 10 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-14 | |
| Aug-03 | |
| Jul-23 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-15 | |
| Jun-22 | |
| May-07 | |
| May-06 | |
| May-06 |
