Starz Heads Into A Guided Profit Trough With Its Streaming Turnaround Under Scrutiny
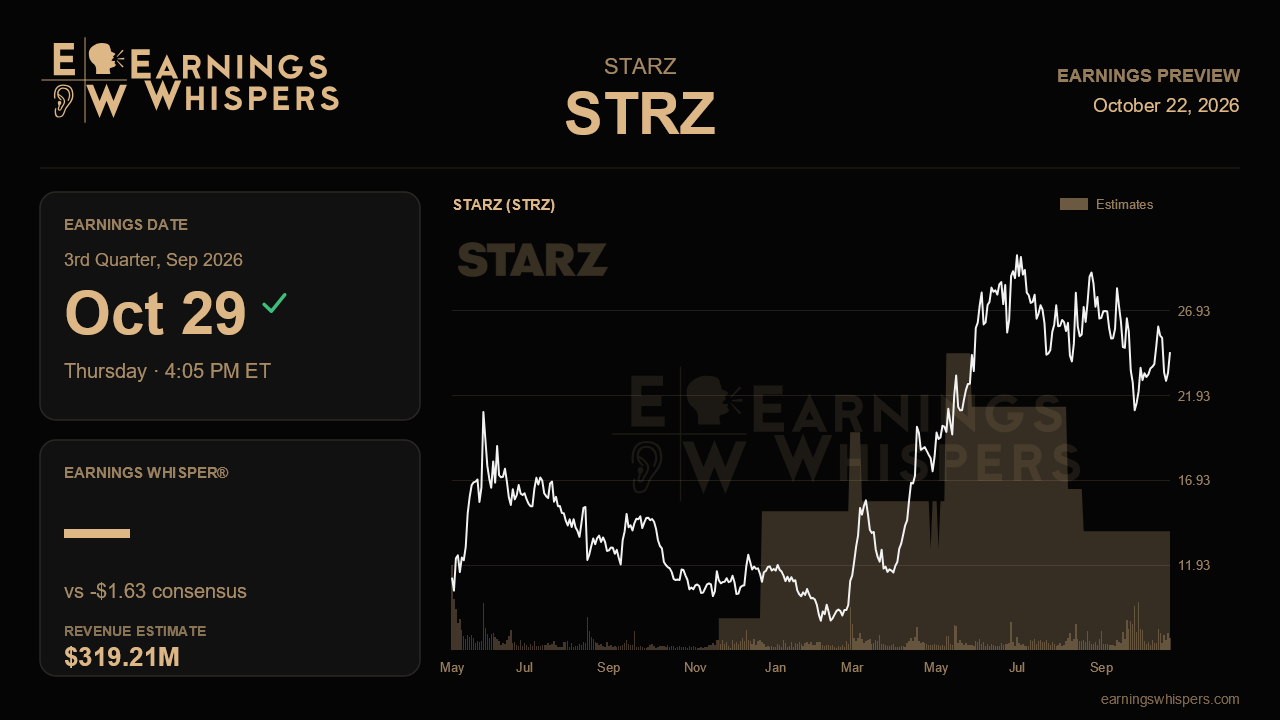
Starz enters its third-quarter report in an unusual position: management has already told investors this will be the weakest quarter of the year for profitability, yet the stock's direction likely hinges on whether the streaming turnaround that emerged last quarter keeps building underneath that trough. On the second-quarter call, the company said adjusted OIBDA would bottom in the mid-$30 million range as programming amortization bunches up, down sharply from the $60 million it just delivered. That makes the headline profit number less of a surprise risk than usual. The real test is whether the operating story holds while margins dip.
Wall Street expects a loss of $1.63 per share on revenue of roughly $319.2 million. Revenue would be essentially flat, down about 0.5% from the $320.9 million posted a year ago, while the loss would narrow considerably from the $2.85 per share recorded in the same quarter last year and from the $2.27 loss last quarter, which was weighed down by a $147 million charge tied to exiting the Universal Pay-2 arrangement. Flat sales, then, is the bar, and that is meaningful in context. Linear and other revenue, which came in at $87 million last quarter, continues to erode, so holding the top line steady requires the streaming business to do the heavy lifting.
That is where last quarter's inflection comes in. OTT revenue reached $221 million and grew year over year for the first time since late 2024, up about 1.4% on a pro forma basis excluding Canada. Management paired that with a more confident tone, describing 2026 as a bigger inflection year than first expected, raising full-year adjusted OIBDA growth guidance from low single digits to mid single digits, and steering unlevered free cash flow toward the mid-to-upper end of its $80 million to $120 million range. Validation this quarter would look like a second consecutive period of OTT growth, ideally faster than 1.4%, as new distribution deals begin contributing. The Peacock add-on, which opens access to about 48 million subscribers, the Crunchyroll bundle on Prime Video, a long-term renewal with a major partner and two new distributors were all fresh catalysts last quarter. Early evidence that they are adding subscribers and revenue, rather than simply expanding theoretical reach, would matter more than the OIBDA print itself.
Content is the other swing factor. Fightland was the second-best new-IP launch in the company's history and acquired subscribers at roughly double historical efficiency, and the Michael biopic premiered on the platform in August as an expected tentpole. Commentary on how those titles drove engagement, which management said had risen for four straight quarters, will help determine whether OTT growth is durable. Reaffirming full-year guidance despite the trough, along with content spending under $600 million and progress toward a 20% margin target now pulled forward to the back half of 2027, would keep the narrative intact. Any softening in the free cash flow outlook, especially with year-end leverage already expected near 2.7x after the facility upsize, would challenge it.
The market has not fully bought the turnaround. Shares have slipped 3.1% since the last report, lagging the S&P 500 by about 3 percentage points, and bullish sentiment has cooled from 13.8% to 9.4%. At $24.50 the stock sits comfortably above its 200-day moving average of $20.21 but well off its post-earnings high of $29.79, roughly in the middle of a volatile range. That suggests expectations have reset modestly lower, leaving room for a positive reaction if fundamentals cooperate.
Ultimately, this report comes down to one question: can OTT growth accelerate enough to offset linear decline while profits sit at their guided low point? If streaming revenue keeps climbing and management reiterates its raised full-year targets, the trough becomes a nonevent. If OTT growth stalls, last quarter's inflection may start to look like a one-off.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 12 hours | |
| Oct-20 | |
| Oct-01 | |
| Oct-01 | |
| Oct-01 | |
| Sep-30 | |
| Aug-08 | |
| Aug-07 | |
| Aug-07 | |
| Jul-01 | |
| May-08 | |
| May-07 | |
| Apr-30 | |
| Apr-07 | |
| Mar-10 |
