STARZ Misses EPS Consensus, But OTT Growth Accelerates And Adjusted OIBDA Doubles As Q4 Profit Is Reinvested In P-Valley
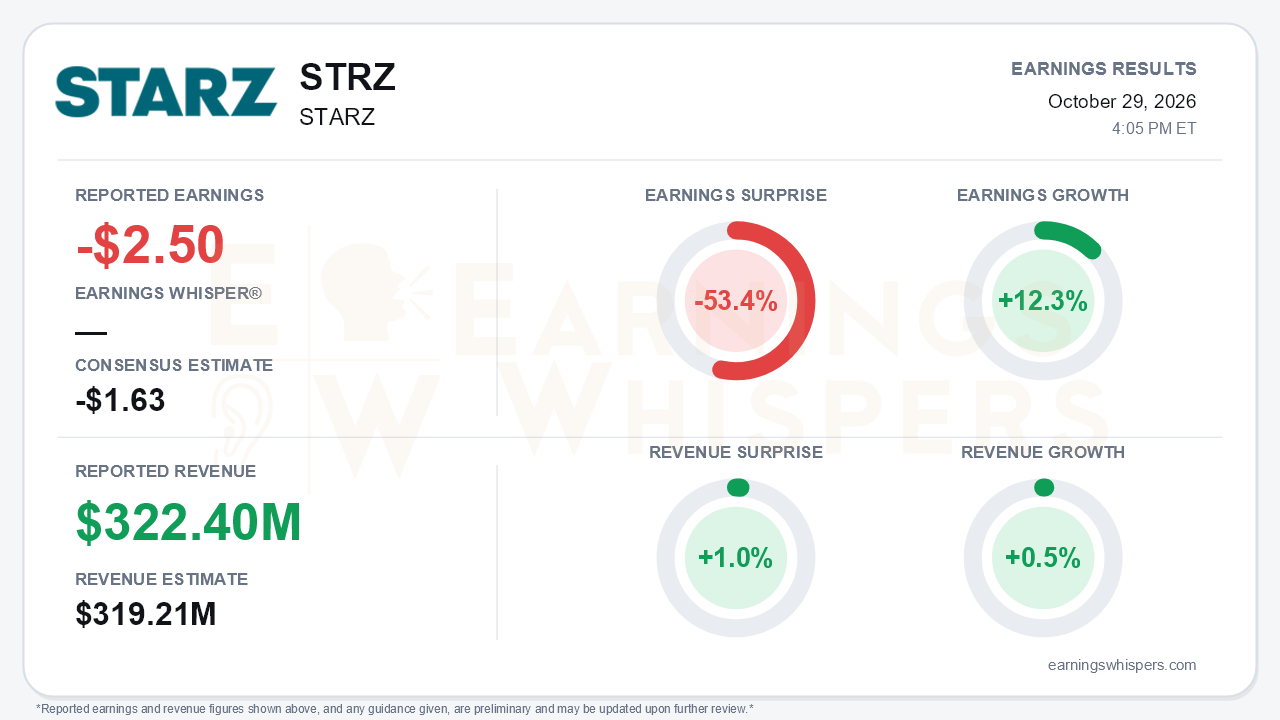
STARZ (NASDAQ: STRZ) posted a third-quarter loss of $2.50 per share on Earnings Whispers' normalized basis, missing the consensus estimate of a $1.63 loss by 53.4%. Revenue of $322.4 million beat the $319.21 million consensus by 1.0% and grew 0.5% year over year. Earnings improved 12.3% from a year ago. The headline miss sits awkwardly against an operating quarter that was better than management had guided. Adjusted OIBDA more than doubled to $44.2 million from $21.8 million and cleared the mid-$30 million target set on the second-quarter call. OTT revenue also accelerated for a second straight quarter. That is the central tension. The per-share line still reflects a heavily loss-making, highly amortized balance sheet, while the operating story is gradually improving.
The quality of the GAAP result deserves scrutiny in both directions. The release shows a GAAP net loss of $2.02 per share, narrower than the $3.15 loss a year earlier and different from the normalized figure above. That GAAP loss was flattered by an $8.3 million restructuring credit. The credit came mostly from an $11.1 million reversal of previously accrued film-output termination fees, tied to revised box-office assumptions, plus a $3.6 million content recovery. Working against the result, depreciation and amortization jumped to $67.4 million from $47.9 million. Programming amortization fell to $141.5 million from $156.8 million, consistent with the content right-sizing of the past year. Sequentially, adjusted OIBDA actually fell from $59.9 million in the second quarter, so the year-over-year doubling partly reflects a weak comparison.
The call preserved a credible, if slow-moving, growth story. OTT revenue reached $226.6 million, up 1.7% year over year and 3.2% pro forma, accelerating from the first pro forma growth of 1.4% in the second quarter. Management said churn is at historic lows, long-tenured app subscribers are at record levels, and ARPU continues to climb. Linear and other revenue fell year over year to $95.8 million but rose sequentially from $87 million. That sequential lift was helped by the first international distribution revenue from owned content, a Sky co-commission on Fightland. Fightland also ran roughly $3 million per hour cheaper to produce, and management pointed to $6-9 million per season per show in licensing upside. That is the clearest evidence yet for the ownership thesis. Investors should also recognize that this distribution revenue will be lumpy, recognized on delivery and window openings rather than steadily.
Guidance is where the setup becomes more complicated. Management reaffirmed every 2026 target:
- mid-single-digit adjusted OIBDA growth;
- $100-120 million of unlevered free cash flow;
- roughly 2.7x leverage exiting the year;
- a 20% adjusted OIBDA margin in the second half of 2027.
It did not raise any of them after lifting outlooks in the second quarter. More importantly, the third-quarter outperformance is being redeployed into marketing for the final season of P-Valley, which returns December 4. As a result, implied fourth-quarter adjusted OIBDA now falls below the mid-$60 million cadence discussed last quarter. Year-to-date unlevered free cash flow of $85 million leaves a manageable bar for the range. However, net corporate debt rose to $600.7 million from $565.5 million after the term-loan add-on. Leverage still improved to 2.8x only because trailing OIBDA grew.
The catalyst list is longer than the risk list, but bears have legitimate ammunition.
On the positive side:
- a new Verizon Fios agreement and several other distribution deals;
- Michael becoming the best-performing pay-one title in Starz history;
- early retention gains from the five-service super-bundle;
- a 2027 slate featuring an 18-episode Power Origins and the Hunger Games pay-one window.
On the other side:
- P-Valley is ending;
- linear continues its secular decline;
- the Fios deal followed a blackout;
- management floated AVOD diversification through a build or buy, which could add leverage or execution risk if it leads to acquisition activity;
- AI-driven subscription-management bots raise new churn questions, though management argued its 70% wholesale mix insulates it.
The market has treated the stock harshly since the last report. Shares opened at $25.27 after the August release, spiked to $29.79 within a week, then slid to a $19.70 low on October 26. They entered this report at $22.50, down 11.0% from the prior post-earnings open but 14.2% off that low and about 9.9% above the 200-day moving average. Investor sentiment edged up from 0.1377 to 0.1526, remaining modestly positive with no meaningful shift in expectations. Earnings Whispers trend readings are mixed, with momentum positive but AVWAP still negative.
The bottom line is that STARZ delivered a fundamentally better quarter than the EPS miss implies: revenue growth is back, OTT is accelerating, and owned content is starting to monetize. Even so, the reaffirm-only guidance, the pulled-forward Q4 marketing spend, rising net debt, and a GAAP result aided by accrual reversals keep this a show-me story rather than a clean inflection.
Read our earnings preview for STARZ: https://www.earningswhispers.com/article/STRZ/21249
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-22 | |
| Oct-20 | |
| Oct-01 | |
| Oct-01 | |
| Oct-01 | |
| Sep-30 | |
| Aug-07 | |
| Aug-07 | |
| Jul-01 | |
| May-07 | |
| Apr-30 | |
| Apr-07 |
