Veralto Faces A Higher Bar As Street Bets Above Its Own Third-Quarter Guidance
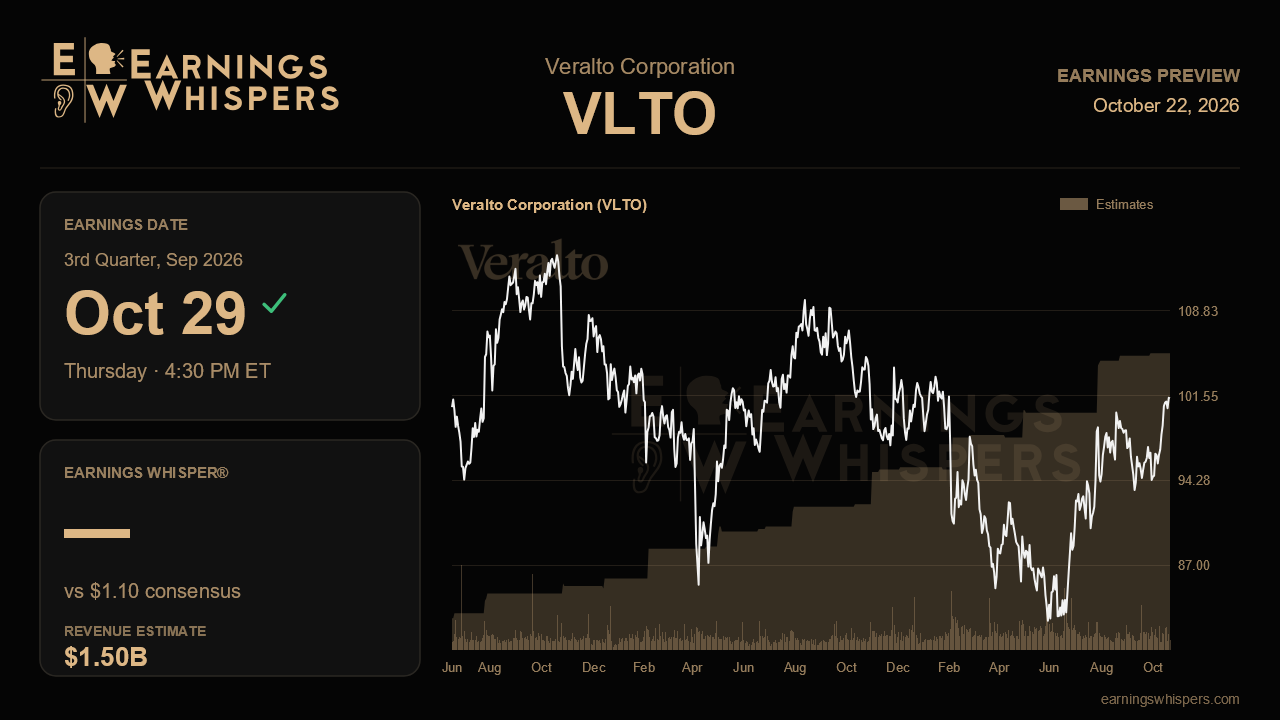
Veralto has spent 2026 steadily raising the bar on itself, and now Wall Street has jumped over it. After lifting its full-year earnings outlook twice, management guided third-quarter adjusted earnings to $1.06 to $1.09 per share. Analysts have since pushed consensus to $1.10, a penny above the top of that range. That gap is small, but the message is clear. The Street now expects the water and product-quality company to beat its own guidance, and to do it without the one-time help that flattered last quarter.
The consensus implies third-quarter earnings growth of about 11% from $0.99 a year ago, on revenue of roughly $1.50 billion, up 6.8%. That is solid but not spectacular growth, and it fits the trajectory management described in July: core sales growth of 4.2% in the second quarter, accelerating to roughly 5% to 6% in the back half, led by volume rather than price. The full-year outlook of $4.35 to $4.43, up from $4.20 to $4.28 in the spring and $4.10 to $4.20 at the start of the year, frames the stakes. A third straight raise would confirm the company is under-promising. A mere reaffirmation, after the Street has already moved ahead of the quarterly guide, could feel like a pause.
The trickiest comparison is the second quarter itself. Veralto earned $1.11 per share then, but about 110 basis points of margin came from tariff refunds that management said will not recur. Analysts are effectively asking for nearly the same earnings this quarter on a cleaner base. Getting there requires genuine operating leverage from higher volumes, especially in water quality, where core growth hit 5.7% last quarter. Industrial water, which accounts for about half of water revenue, and Chemtreat's strong double-digit growth tied to data-center demand are the engines to watch. Evidence that the new Dow partnership for data-center liquid cooling is generating early interest would add weight to that story. On the product quality side, which grew only 2%, management expects a recovery that drives fourth-quarter margin expansion above 50 basis points. Any sign that improvement is starting now would strengthen confidence in the year-end ramp.
The risks are familiar but unresolved. High-growth markets were flat last quarter, with China water shrinking and Latin American sales delayed by project timing even as orders held up. If those orders convert, it supports the acceleration thesis. If timing slips again, it becomes harder to dismiss. Pricing is also set to moderate as prior-year increases lap, which places more pressure on volume, while Chemtreat must keep absorbing volatile oil and chemical input costs. Digital workflow bookings across ESCO, TraceGains and Global Vision offer a quieter test of whether the recurring-revenue software pieces are gaining traction.
The market has been slow to reward the improving narrative. Shares are essentially flat since the last report, trailing the S&P 500 by nearly five percentage points, even though sentiment has swung from notably bearish heading into the prior quarter to modestly positive now. The stock sits comfortably above its 200-day moving average near $93 and is within about 3% of its post-earnings high of $104, so a convincing report could push it toward a breakout from that range.
Ultimately, this quarter is about quality. Veralto has told investors the second half will be powered by volume and margin expansion rather than price and one-time gains. If core growth lands in that 5% to 6% zone and earnings clear $1.10 without the tariff tailwind, the raise-and-beat pattern stays intact. If not, the Street's leap ahead of guidance will look premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 9 hours | |
| Oct-12 | |
| Sep-23 | |
| Sep-17 | |
| Aug-19 | |
| Jul-29 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-21 | |
| Jul-13 | |
| Jun-12 | |
| Jun-08 | |
| Jun-04 | |
| May-27 |
