Veralto Beats And Raises For A Third Straight Quarter As Core Growth Accelerates, But Q4 Margins Flatten Under Acquisition Dilution
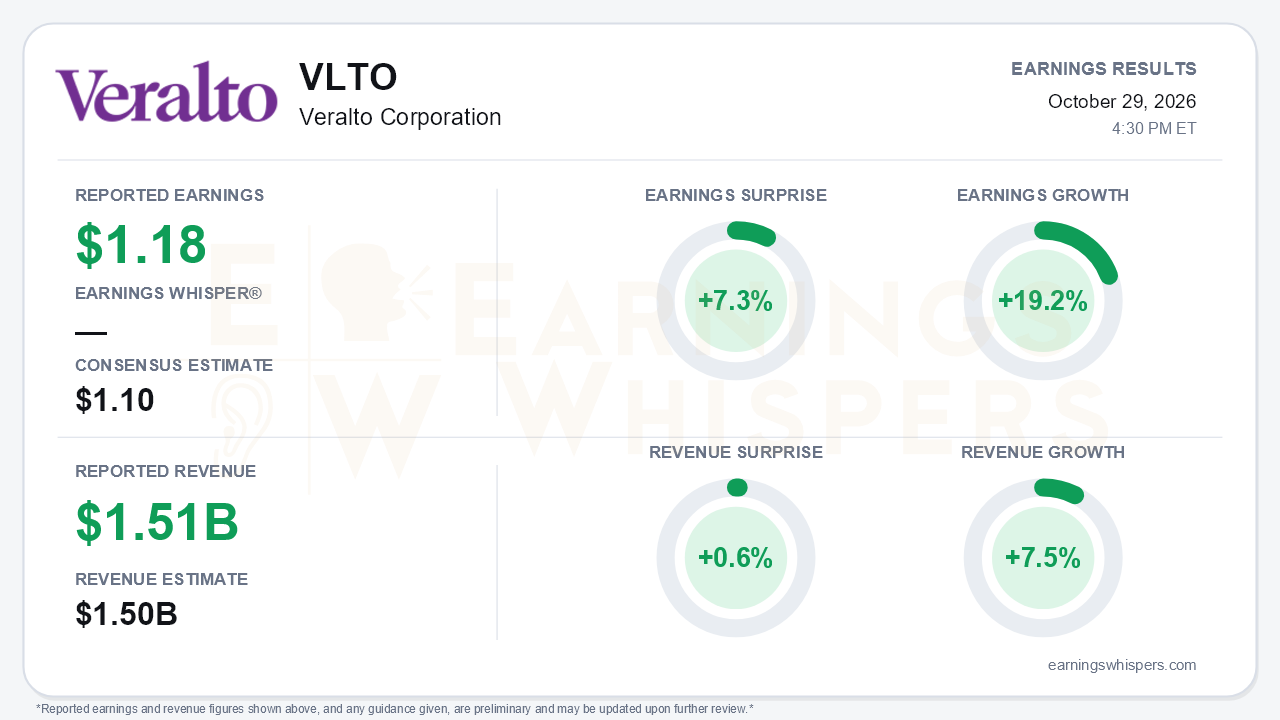
Veralto delivered the kind of quarter that steadily rebuilds a growth narrative. Adjusted earnings of $1.18 per share beat the $1.10 consensus by 7.3% and grew 19.2% year over year. Revenue of $1.509 billion edged past the $1.50 billion estimate by 0.6% and rose 7.5%. The more important development sits beneath the beat. Core sales growth accelerated to 5.1% from 4.2% in the second quarter, with both segments improving. Management also raised full-year adjusted EPS guidance for the third consecutive quarter, to $4.49-$4.52. That range now implies 15% to 16% growth, against an initial framing of mid-to-high single digits. The central tension is that the profit story is strongest right now, while the fourth-quarter guide shows margin expansion pausing as acquisitions and non-recurring benefits roll through.
The quality of the beat deserves some scrutiny on two fronts. First, GAAP and adjusted results diverged sharply. GAAP operating profit fell to $298 million from $326 million, and GAAP operating margin dropped to 19.7% from 23.2%. The decline reflects $22 million of restructuring charges, $17 million of amortization, $10 million of strategic-initiative costs, and a $39 million reduction of a Danaher-era tax indemnification asset. That indemnification charge was offset by a matching reduction in tax liabilities, which explains why income taxes were only $20 million on $273 million of pretax earnings. GAAP EPS still rose to $1.03 from $0.95. Second, adjusted operating margin expanded 170 basis points to 25.6%, but the call made clear that a tariff refund helped the third quarter and will not repeat. Free cash flow was strong at $304 million, up about 18% year over year, though below the second quarter's $328 million.
Operationally, the acceleration looks broad rather than comp-driven, at least in the third quarter. Water Quality core sales rose 6.4%, up from 5.7%, and water treatment grew double digits on North American industrial demand, water reuse, and digital infrastructure. Data center revenue doubled, and Veralto is extending into direct-to-chip liquid cooling fluids through a Dow glycol partnership. Product Quality and Innovation improved to 3.2% core growth from 2.0%. High-growth markets in that segment rose 4.7% after declining in the first quarter, and color measurement equipment is recovering after roughly four quarters of decline. The cost optimization program is also arriving early. Expected 2026 savings went from none assumed in the first quarter, to a few million in the second, to $10-$15 million now, with a run rate of about $35 million targeted by 2028.
The forward picture is credible but not frictionless. Fourth-quarter core growth is guided to 5.5%-6.5%, the top of the second-half range set in the second quarter, and total sales growth is expected at 10%-11% including roughly 5% from M&A. Adjusted operating margin, however, is guided to about 24.5%, broadly flat year over year and down sequentially. Management said roughly 70 basis points of fall-through and cost savings will be absorbed by dilution from the newly closed Cleanwater1 acquisition. The CFO also cautioned that part of the expected PQI acceleration reflects easy color-measurement comparisons. Bears have additional ammunition:
- China water remains weak.
- Latin America water is down modestly on election-related delays.
- Western European marking and coding is flat.
- Packaging and color hardware projects have slipped, although management reported no cancellations.
- Memory and transportation cost inflation is emerging.
- The tariff refund will not recur in 2027.
Capital deployment is now a meaningful part of the earnings algorithm. The release cites $1.1 billion spent on four bolt-ons: In-Situ, GlobalVision, Alfaa UV and Cleanwater1. It also cites $550 million of buybacks, equal to 2.4% of shares outstanding. The call's figure of more than $1.65 billion appears to combine the two. Diluted share count fell to 245.3 million from 250.6 million, a modest but real tailwind to per-share growth. Management reported that In-Situ synergies are running ahead of underwriting.
Investor sentiment improved meaningfully, moving from -0.19 before the prior report to roughly neutral at +0.02. Investors are no longer leaning skeptical, but they are hardly euphoric. Shares have gained only 2.5% since opening at $101.52 after the July report, yet at $104.06 they sit about 11.9% above the 200-day moving average. Price and AVWAP trend readings are positive. The setup is a stock that has held up well without pricing in the full extent of the guidance raises.
The bottom line is that Veralto turned in a clean operational quarter, with accelerating core growth in both segments, early cost savings and a third consecutive guidance raise. Those strengths outweigh the noise in GAAP results. The next debate is margins. With fourth-quarter profitability flattening on acquisition dilution and several 2027 headwinds already flagged, the story increasingly depends on whether volume growth and acquisition integration can carry earnings once one-time benefits fade.
Read our earnings preview for Veralto Corporation: https://www.earningswhispers.com/article/VLTO/21256
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-22 | |
| Oct-12 | |
| Sep-23 | |
| Sep-17 | |
| Aug-19 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-21 | |
| Jul-13 | |
| Jun-12 |
