Amarin's Leaner Model Faces A Proof Test As Europe Must Offset US Erosion
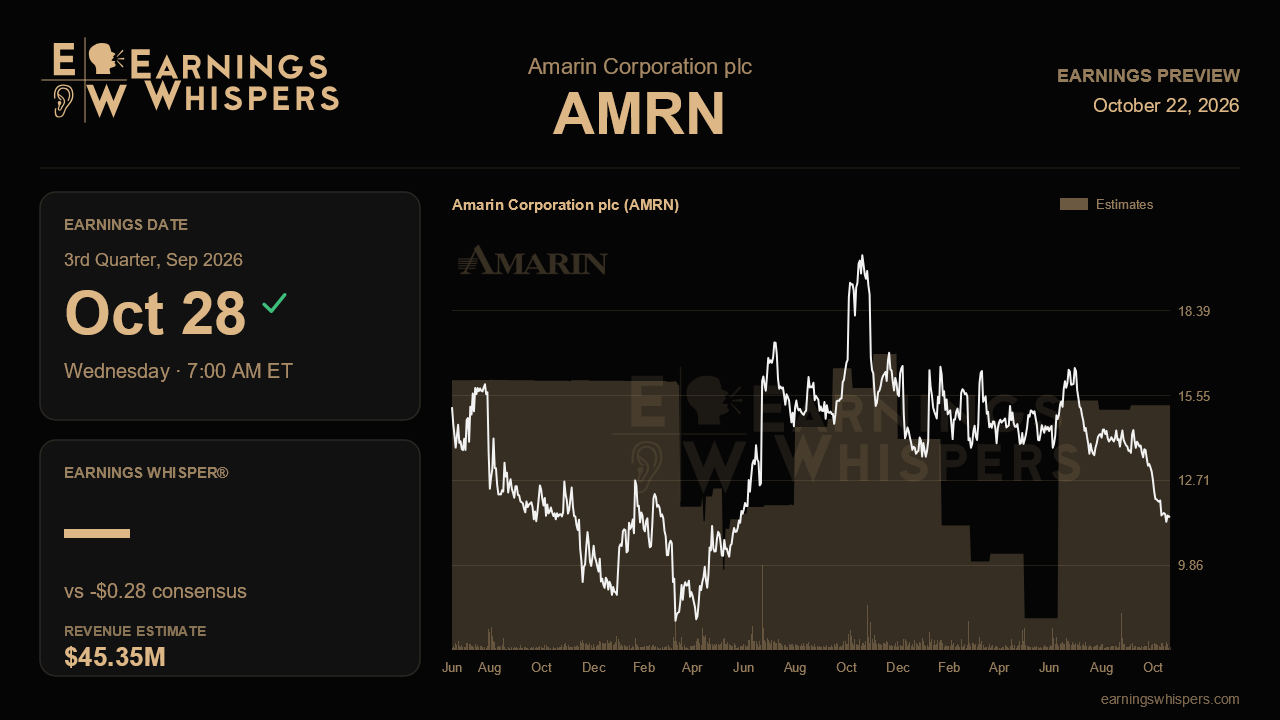
Amarin enters its third-quarter report with a story that sounds better than it looks on the income statement. Last quarter management called the period an inflection point. Restructuring was finished, cash flow was positive for a third straight quarter, and European demand was surging. Yet total revenue has fallen for four consecutive quarters, and the stock has dropped sharply since that upbeat call. The October 28 release, due before the open, needs to show whether international growth and a smaller cost base can finally outweigh steady erosion in the US business.
The Street expects revenue of about $45.4 million, down 8.7% from $49.7 million a year ago but up from the $42.2 million posted last quarter. That would be the first sequential increase in a year. Consensus calls for a loss of $0.28 per share, far wider than the $0.07 loss last quarter and breakeven a year ago. The gap is large given that the full roughly $70 million cost-savings baseline should now be in the run rate, so the estimate deserves some caution. Still, it sets a low bar on the bottom line. Management introduced a FY2026 outlook for certain key metrics for the first time last quarter but gave no hard revenue guidance. Cash generation and operating expenses are therefore the cleaner yardsticks.
The biggest question is whether international momentum can keep growing fast enough to matter. Partner in-market demand rose 59% year over year last quarter, and European demand climbed 69%. European product revenue has grown sequentially two quarters running, and Recordati royalties rose to $1.4 million. A sequential revenue rebound toward consensus, driven by Europe and royalties rather than a one-off partner shipment, would support the claim that the dual model is working as designed. Because partner supply shipments are lumpy, though, a soft international number would not by itself disprove the story. The trend in royalties and in-market demand matters more than one quarter's shipments.
The US side remains the drag. US product revenue fell to $32.2 million from $36.5 million on generic pricing pressure, even as Vascepa's share rose to 48% and branded scripts grew 14%. Holding share near that level while pricing stabilizes would be encouraging. Any update on contracting beyond 2026, when current exclusives are only assured, could matter more than the quarter itself, since that is the stock's main overhang. Gross margin also needs watching. Cost of goods rose 22% last quarter as the mix shifted toward lower-margin partner supply, so growth abroad can thin margins even as it lifts revenue.
The market has not given management much benefit of the doubt. Shares have fallen 17.7% since the last report, trailing the S&P 500 by more than 22 percentage points. At $11.51, the stock is well below its 200-day moving average of $14.41 and just above the post-earnings low of $11.25. The whole trading range has shifted lower than in the prior quarter. Sentiment has cooled slightly, from 25.5% bullish to 22.5%. That combination suggests skepticism is already priced in, but it also means the shares lack technical support if the report disappoints.
Capital allocation could change the tone quickly. Barclays is running a strategic review, and a buyback authorization is in place. With $314.6 million in cash and no debt, Amarin has room to act. Progress on that review, or concrete steps to return capital, could reframe the discussion more than any revenue figure.
Ultimately, the narrative stays intact if Amarin pairs sequential revenue growth with continued positive operating cash flow and stable opex. That would show the leaner, royalty-driven model can offset US pricing pressure. If revenue slips again and cash flow turns negative, the inflection-point claim will look premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 11 hours | |
| Oct-21 | |
| Sep-11 | |
| Aug-31 | |
| Aug-28 | |
| Aug-24 | |
| Aug-24 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-15 | |
| Jun-30 | |
| Jun-05 | |
| May-27 |
