Amarin Posts First Profit In Two Years On Cost Cuts, But Shrinking Revenue Undercuts The Beat
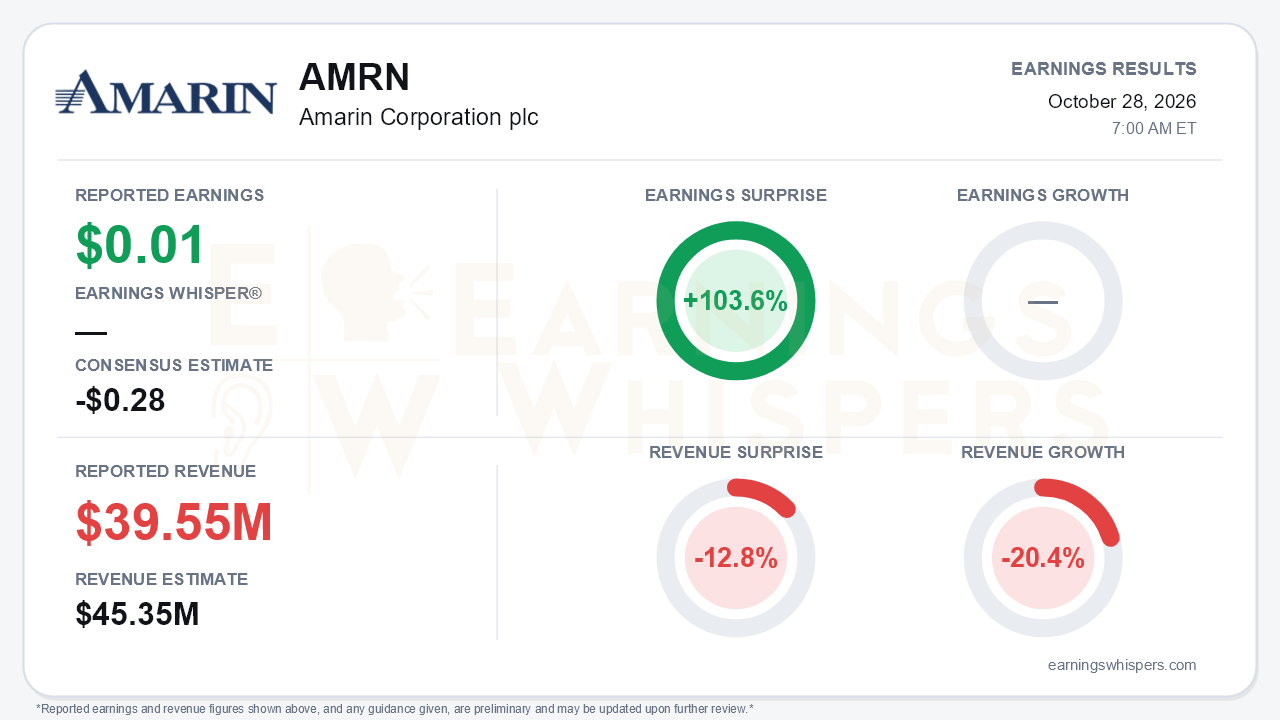
Amarin (NASDAQ: AMRN) reported third-quarter earnings of $0.01 per share. Consensus had expected a loss of $0.28, so the result beat estimates by 103.6%. The top line told a different story. Revenue of $39.55 million missed the $45.35 million consensus by 12.8% and fell 20.4% from a year ago. GAAP net income was $245,000, compared with a $7.7 million loss in the prior-year quarter. It was the company's first profitable quarter in more than two years. That is the central tension of the report: the cost restructuring is working, but the revenue base it supports keeps shrinking, and the profit is thinner than the headline swing suggests.
The quality of the beat deserves scrutiny. Amarin still lost $2.4 million at the operating line. The company reached a pretax profit only because $2.4 million of net interest income on its cash pile offset that loss. Most of the year-over-year improvement came from the expense line, not from the business:
- Total operating expenses fell 44% to $18.5 million.
- SG&A dropped 27%.
- Last year's quarter carried $9.4 million of restructuring charges, and this quarter had none.
Gross profit actually fell to $16.2 million from $22.2 million. On management's preferred non-GAAP basis, net income declined to $1.6 million ($0.08 per ADS) from $4.0 million ($0.19 per ADS) a year earlier. In other words, the GAAP swing to profit reflects the absence of charges, while adjusted profitability went backward.
The revenue trajectory is the bigger concern. Total revenue has now declined three quarters running, from $45.1 million in Q1 to $42.2 million in Q2 to $39.6 million in Q3. U.S. product revenue fell to $28.5 million, down from $32.2 million sequentially and $40.9 million a year ago, as generic competition and customer mix eroded net pricing. The volume picture also softened in several ways:
- Earlier this year, management cited branded script growth of 17% in Q1 and 14% in Q2. This quarter it described U.S. volume only as flat, and the script metric disappeared from the release.
- U.S. IPE market share slipped to 47% from 48%.
- On the call, management said pricing pressure should persist into 2027, and payer exclusives beyond 2026 are not yet confirmed.
Bears have legitimate ammunition here: the U.S. business is the bulk of revenue, and both price and momentum are deteriorating.
The international partner model offers the bull case, but it has not yet shown up consistently in reported sales. European in-market demand rose an estimated 68%, with Recordati driving growth in Spain, the UK and Italy. Partner-network demand overall rose 55%. Yet Europe product revenue fell to $3.7 million from $5.4 million in Q2, because Amarin's revenue depends on partner ordering and inventory patterns. Management shifted toward trailing-12-month framing to smooth that lumpiness. Elsewhere, results were stronger:
- Rest-of-world product revenue jumped to $4.7 million from $1.4 million in Q2.
- Licensing and royalty revenue more than doubled year over year to $2.7 million.
- Renegotiated API contracts lifted gross margin roughly 2.3 points sequentially, excluding write-offs. Management expects that benefit to grow with volume.
The balance sheet is where the story is strongest. Cash and investments rose to $323.4 million, with no debt, and management targets about $330 million by year-end. Operating cash flow of $9.2 million was the best of the year, and the company posted its fourth straight quarter of positive free cash flow. On the call, management more explicitly tied the Barclays strategic review to the timing and scale of a potential share repurchase. That makes capital return a tangible catalyst.
The EMT2 colorectal cancer trial adds optionality rather than near-term value. VASCEPA missed the trial's primary endpoint of progression-free survival. It did show a statistically significant 32% lower hazard of death on overall survival. Other incremental positives were the Poland launch and inclusion in new ESC/ERA guidelines.
Investor sentiment improved modestly, rising to 0.33 from 0.25, which suggests expectations remained positive into the print. The stock has not reflected that optimism:
- Shares entered the report at $11.95, down 14.5% since the open after the July report.
- The price sat 16.8% below the 200-day moving average of $14.36.
- The stock was about 6% above a 52-week low of $11.25 set on October 16, well off the $15.25 inter-quarter high from late August.
The Earnings Whispers trend signals are mixed. Price and AVWAP readings are negative, while momentum is positive.
The bottom line is that Amarin delivered on cost discipline and cash generation, but not on growth. The profit beat came largely from the absence of restructuring charges and from interest income, while revenue missed badly and the U.S. franchise showed fresh signs of fatigue. Until partner demand turns into steadier reported revenue, the investment case rests heavily on the cash balance and on what the Barclays review ultimately delivers.
Read our earnings preview for Amarin Corporation plc: https://www.earningswhispers.com/article/AMRN/21260
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-25 | |
| Oct-22 | |
| Oct-21 | |
| Sep-11 | |
| Aug-31 | |
| Aug-28 | |
| Aug-24 | |
| Aug-24 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 |
