OFS Capital Must Show Redeployment Can Rebuild Income Behind An Uncovered $0.17 Payout
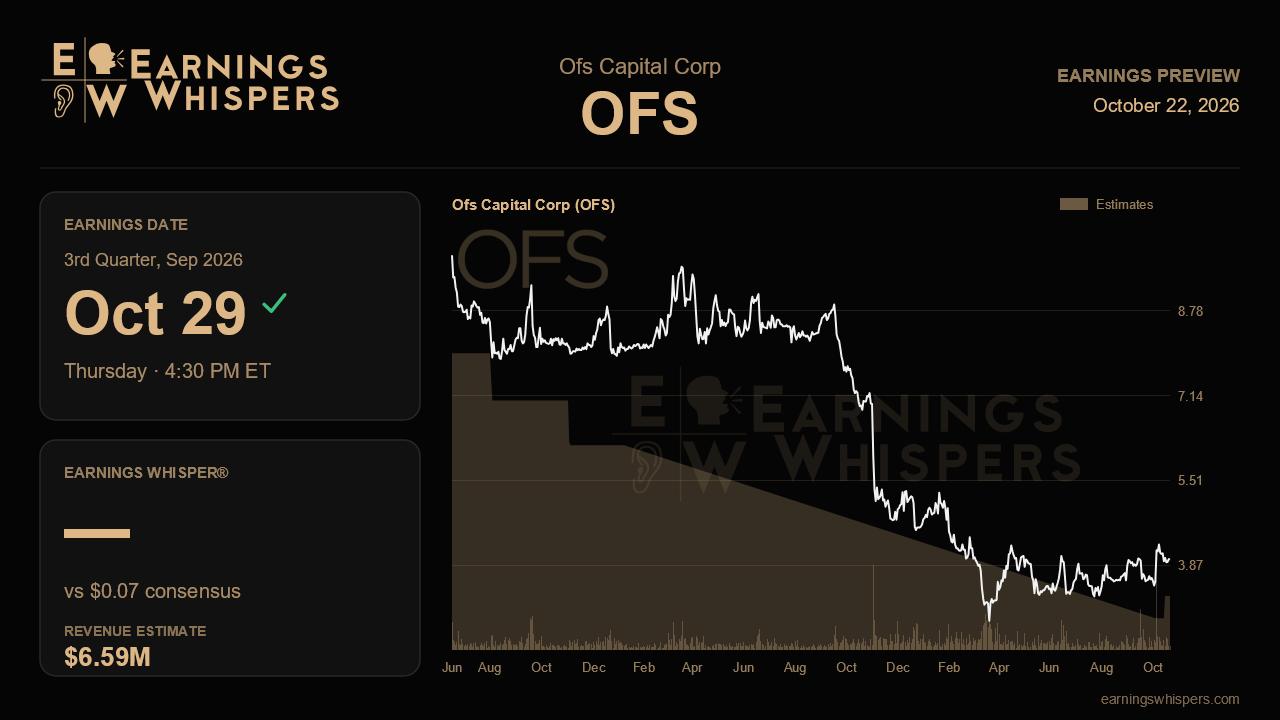
OFS Capital enters its September-quarter report with a split personality. Its balance sheet has rarely looked sturdier, yet its core earning power has rarely looked weaker. Last quarter management declared the deleveraging phase finished and said the priority now is putting capital back to work. Thursday's release, due after the close on October 29, is the first real chance to see whether that shift from defense to offense shows up in the income statement or remains a talking point.
The Street is not asking for much. Consensus calls for net investment income of $0.07 per share on roughly $6.6 million of total investment income. That would be a 68% drop in per-share earnings from the $0.22 earned a year ago and a 37.5% decline in revenue from $10.6 million. Measured against the prior quarter's $0.08 and $6.8 million, the forecast implies a slight further step down rather than a stabilization. Management did not issue formal guidance, so the bar has been set by analysts digesting a quarter in which NII was cut in half from $0.18. Several forces hit at once in that quarter. Debt paydown shrank the interest-earning base, a one-time dividend from Fansteel rolled off, a new loan went on non-accrual, and the weighted-average performing yield slid to 12.1% from 13.5% two quarters earlier.
The most useful number in this report may be portfolio size, not EPS. The portfolio shrank from $370 million across 57 issuers a year ago to under $298 million across 51. If redeployment has truly begun, new originations should at least halt that shrinkage, and ideally lift the issuer count. Two things would validate management's narrative: net portfolio growth and stable yields despite a soft middle-market M&A backdrop. A further decline in assets would challenge it. So would another round of yield compression, which would suggest the company cannot find attractive loans to replace what it sold or repaid. With asset coverage improved to 161% and maturities pushed out to 2028 through 2031, OFS has room to add leverage. The question is whether it is using it.
Credit is the second test. The loan added to non-accrual last quarter was marked at 79% of par and accounts for about 3.5% of the portfolio. Any further slippage there, or new problem names, would eat into an already thin income stream. CLO equity remains a recurring drag. Credit-portfolio losses were $6.5 million last quarter after $9.1 million of CLO depreciation the quarter before, and another sizable hit would offset gains elsewhere in net asset value.
Those gains have largely come from Fansteel. Its fair value has climbed to $94.6 million, about 32% of the portfolio and roughly 23 times its cost, and that markup drove NAV per share up 3% to $8.41. A monetization could reset NII meaningfully higher by recycling that capital into income-producing loans. Until then, it is also a concentration risk, and NAV now leans heavily on a single private valuation.
The market has been generous anyway. Shares have climbed about 20% since the last report, outpacing the S&P 500 by more than 16 points. At $3.98 they sit above the 200-day moving average of $3.84 and in the upper part of the post-earnings range of $3.23 to $4.30. Sentiment tells a different story, with readings leaning about 56% bearish. That mix suggests the rally reflects NAV and the Fansteel optionality more than confidence in earnings. It also leaves the stock exposed if the dividend conversation sours.
That conversation is the crux. The $0.17 distribution is covering itself barely halfway at current NII levels. For the recovery story to hold, this quarter needs evidence of reinvestment: a growing portfolio, steady yields and contained credit. Concrete progress toward a Fansteel exit would strengthen the case further. Without that evidence, the pressure on the payout becomes the dominant story.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 15 hours | |
| Oct-21 | |
| Oct-06 | |
| Sep-18 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-22 | |
| May-02 | |
| May-01 | |
| Apr-30 | |
| Apr-30 | |
| Apr-22 | |
| Mar-03 | |
| Mar-03 |
