OSI Systems Must Prove Deferred Middle East Deliveries Were Timing, Not Trouble
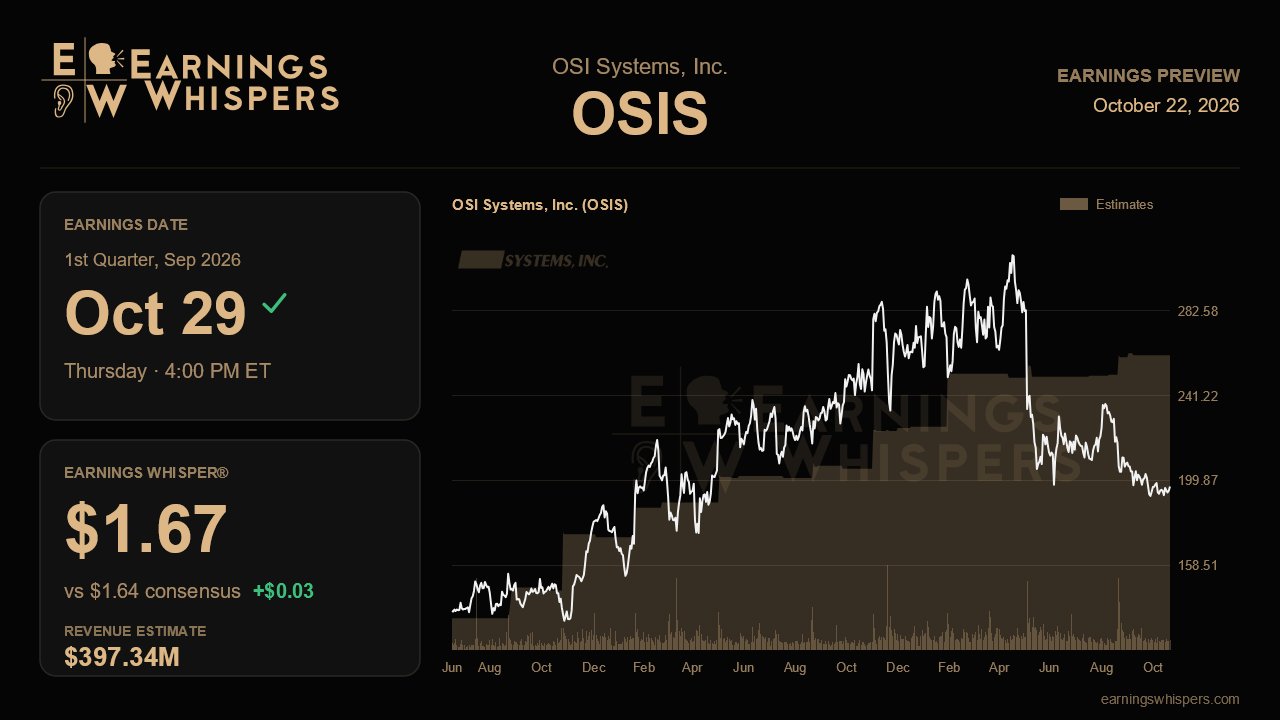
OSI Systems heads into its fiscal first-quarter report with a credibility question layered on top of a very good balance sheet story. Last quarter the company posted record margins, record cash flow and a record backlog near $1.9 billion, yet it still missed its own full-year revenue range after raising guidance twice, blaming roughly $50 million of Middle East security deliveries that slipped past year-end. Management framed that shortfall as a timing issue. The September quarter is the first real chance to see whether those shipments actually show up.
The Street is looking for earnings of $1.64 a share on revenue of $397.3 million, which would mean EPS growth of about 15.5% on sales growth of just 3.3%. That gap matters. It implies analysts expect the margin gains from the fourth quarter, when adjusted operating margin climbed 200 basis points to 17.7%, to carry forward even without much help from the top line. The Earnings Whisper sits at $1.67, only a few cents above consensus, so the bar is a touch higher than the published number but not dramatically so.
The full-year picture is where expectations look stretched. Management guided fiscal 2027 revenue to $1.875 billion to $1.93 billion and EPS to $11.13 to $11.49. Consensus of $1.93 billion in revenue sits at the very top of that range, and the $11.42 EPS estimate is near the upper end. That is an ambitious posture given that management explicitly described the year as back-half weighted, warned that most revenue from the new Customs and Border Protection contracts lands in fiscal 2028 and beyond, and guided earnings growth slightly below revenue growth because of added operating spending. A soft first quarter would not break the guidance, but it could pressure estimates that already assume the high end.
Several operating threads deserve close attention. First, bookings: book-to-bill slipped just below 1.0 in the fourth quarter after 1.3 in the third, and some expected Middle East orders were also pushed out. A rebound above parity, helped by the $21 million CBP task order and the two sole-source CBP awards with ceilings of roughly $200 million and $85 million, would support the multi-year growth thesis. Second, healthcare margins jumped to 10% last quarter after hovering near zero for most of the year, and investors will want evidence that this was durable rather than a one-quarter mix benefit. Third, service revenue was roughly flat in the fourth quarter after growing 23% in the first, so a return to growth would ease concerns about the recurring part of the security business. Finally, further collections from the Mexico customer, whose receivables fell to $190 million, would reinforce the cash flow story. Updates on radar demand, which management called the strongest it has seen, offer upside commentary but are unlikely to move this quarter's numbers.
The market has not been generous. The stock is up about 0.5% since the last report, trailing the S&P 500 slightly, but that flat line follows a punishing prior quarter in which shares slid from nearly $277 to below $200. At $196.93, the stock trades well below its 200-day moving average of $240.63 and sits in the lower half of its post-earnings range of $186.50 to $213. Sentiment has flipped from modestly bullish ahead of the last report to modestly bearish now, suggesting investors are approaching this print with more skepticism than enthusiasm.
That skepticism sets up a clear test. If OSI shows that the deferred Middle East revenue is converting, bookings are recovering and margins are holding near fourth-quarter levels, the miss will look like the timing hiccup management described, and the depressed valuation could become the story. If deliveries slip again or margins retreat, the Street's high-end full-year assumptions will look exposed, and the narrative of a record backlog waiting to convert will need more time than investors have patience for.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 13 hours | |
| Oct-21 | |
| Sep-30 | |
| Sep-28 | |
| Sep-17 | |
| Sep-16 | |
| Aug-21 | |
| Aug-21 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-19 |
