OSI Systems Builds A Record $2.1 Billion Backlog, But Thinner Margins And A Buyback-Driven Guidance Raise Temper The Quarter
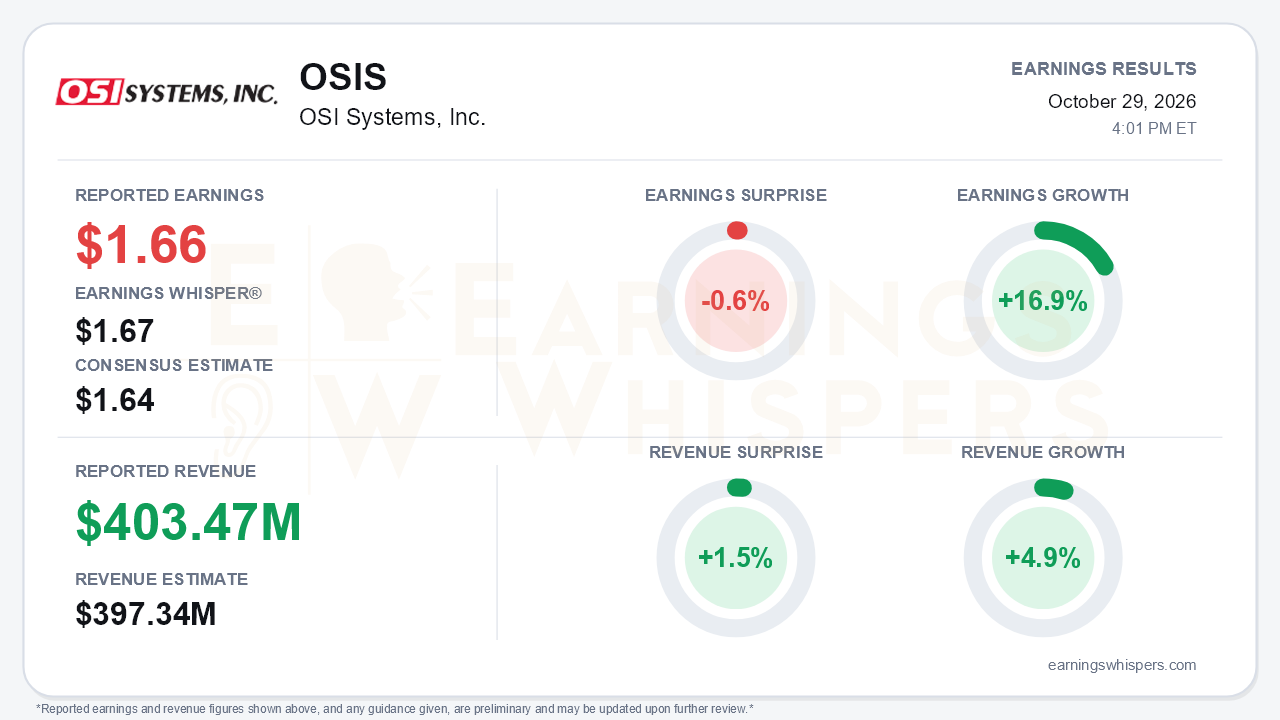
OSI Systems (NASDAQ: OSIS) opened fiscal 2027 with what looks like a clean quarter on the surface. Non-GAAP EPS of $1.66 rose 16.9% year over year. Revenue of $403.47 million grew 4.9% and topped the $397.34 million consensus by 1.5%. EPS edged past the $1.64 consensus but fell a penny short of the $1.67 Earnings Whisper number, a 0.6% miss against the expectation that mattered most to engaged investors. The more important story sits beneath the headline. Bookings of $583 million produced a 1.4 book-to-bill and lifted backlog to a record $2.1 billion from $1.9 billion in June. Profitability moved the other way, and the guidance raise owes more to financial engineering than to operations. That is the central tension.
The quality of the earnings growth deserves scrutiny. Non-GAAP operating income actually fell to $38.3 million from $39.8 million, and adjusted operating margin compressed to 9.5% from 10.3%. Gross margin slid to 30.7% from 32.0% a year ago and from 34.7% in the fourth quarter of fiscal 2026. The 17% non-GAAP EPS gain, and the 28% jump in GAAP EPS to $1.51, came largely below the operating line. Interest and other expense dropped to $3.3 million from $7.4 million, diluted shares fell 7% to 16.3 million after $62 million of repurchases, and a slightly larger discrete tax benefit helped. Those are real dollars to shareholders, but they are not evidence of an improving core.
The segment picture explains the margin slippage. Security revenue grew roughly 4% to $264 million, but its adjusted margin fell to 12.6% from 13.5%, which management attributed to a less favorable revenue mix. Optoelectronics and Manufacturing was the standout. Third-party sales rose 16%, adjusted margin expanded to 12.1%, and backlog hit a record. Healthcare was the clear weak spot. Revenue fell 14% and the segment swung to a -1.8% adjusted operating margin from 6.0% a year ago, a sharp reversal from the prior quarter's 5% growth and roughly 10% margin. Management promised a return to growth this year but offered little to show the turn has started.
The forward picture leans heavily on the second half. The call did preserve a credible demand story. The RF business booked about $90 million of new orders while executing on the roughly $235 million Over-the-Horizon radar contract, and a second RF facility now has capacity for more awards. CBP has placed about $21 million of firm orders under the $200 million and $85 million sole-award IDIQs, and the LA28 Olympics screening role offers a large-venue showcase. The near-term setup is softer, however. Services grew only about 4-5%, well short of the 'strong double-digit' full-year target. Management said it has good visibility for service growth to roughly double or more in the second quarter and keep accelerating in the second half. The fiscal second quarter is guided modestly down year over year because of a tough Middle East comparison and an $11 million Mexico headwind. Only about $8 million of roughly $50 million in deferred Middle East revenue shipped, with the rest slipping into late fiscal 2027 and fiscal 2028.
Guidance reflects the same imbalance. Full-year non-GAAP EPS guidance rose to $11.28-$11.64 from $11.13-$11.49, and management acknowledged on the call that the increase stems mainly from buybacks. Revenue guidance of $1.875-$1.93 billion was only reaffirmed despite the backlog build. The balance sheet also absorbed the repurchases. Cash and investments fell to about $302 million from $360 million, net leverage rose to roughly 2.3x from 2.1x, and inventory climbed $48 million to $463 million. Operating cash flow did more than double to $37 million, and customer advances rose to $64 million, both of which support the backlog's credibility. Even so, cash conversion now depends on second-half deliveries and Mexico collections.
Investor sentiment shifted noticeably. It slipped from modestly positive (0.12) to modestly negative (-0.12) heading into the report. The stock has gained 6.2% since opening at $196 after the August report, trading near the roughly $204 average price the company paid for its own shares. It still sits 12.7% below its 200-day moving average of $238.37. The market has been treating OSIS as a stock in repair rather than one priced for its record backlog, though the AVWAP trend reading has turned positive.
The bottom line is that OSI Systems delivered demand evidence bulls can point to: record bookings, a strong Opto business, and expanding defense and CBP opportunities. Bears have legitimate ammunition, though. Margins contracted, Healthcare deteriorated, services lagged, and the EPS raise was essentially mechanical. Until backlog converts into revenue and margin recovery in the back half, the record order book remains a promise rather than a result.
Read our earnings preview for OSI Systems, Inc.: https://www.earningswhispers.com/article/OSIS/21267
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-29 | |
| Oct-29 | |
| Oct-22 | |
| Oct-21 | |
| Sep-30 | |
| Sep-28 | |
| Sep-17 | |
| Sep-16 | |
| Aug-21 | |
| Aug-21 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 |
