Magna's Raised Margin Outlook Faces A Seasonal Test As Shares Lag The Market
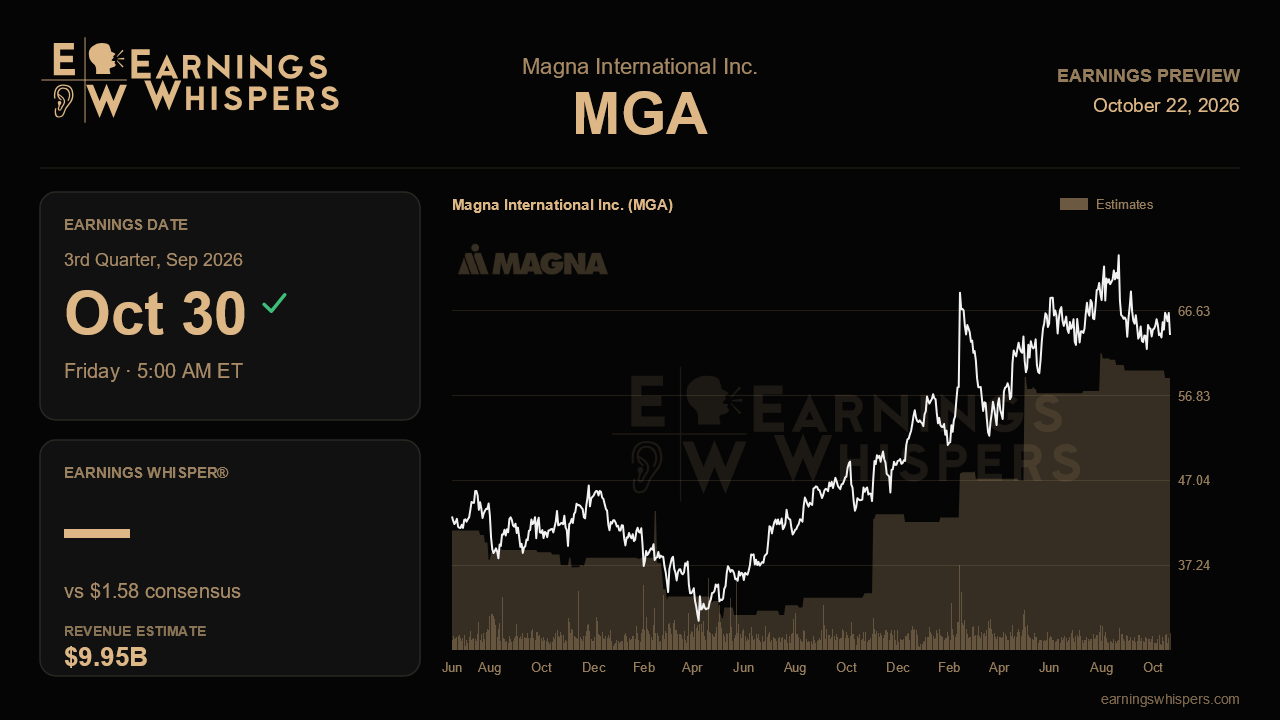
Three months ago Magna International delivered something it had held back for most of a year: a clean, multi-line guidance raise built on operational execution rather than vehicle volume. The market has since shrugged. Shares are down about 7% since that report while the S&P 500 gained nearly 4%, so the third-quarter release on October 30 arrives with a pointed question. Was the second quarter's margin step-up structural, as management argued, or did it mark a high-water mark for the year?
The Street expects adjusted earnings of $1.58 a share on revenue of roughly $9.95 billion. That would be an 18.8% gain in profit from $1.33 a year ago on sales that slip about 1%. In other words, analysts are again betting on margin expansion rather than growth. The sequential drop from the second quarter's record $1.86 and $10.98 billion is normal for a quarter shaped by summer production shutdowns. The real test is whether profit still grows sharply year over year without help from the top line.
The guidance math frames that test. Management now expects 2026 earnings of $6.70 to $7.30 a share, up from $6.25 to $7.25, with the adjusted EBIT margin range lifted to 6.3% to 6.6%. Consensus of $6.82 sits in the lower part of that range, so analysts have not fully embraced the raise. On revenue, the Street's $42.53 billion actually edges above the top of the reduced $41.3 billion to $42.5 billion outlook. Management attributed the sales cut to a stronger dollar and earlier-than-planned divestiture closings rather than weaker demand. The combination of cautious earnings estimates and generous sales estimates means profit conversion matters most. A quarter that shows margins holding near the second quarter's 6.2% on lower sales would support the upper half of guidance. Margin slippage driven by volume would suggest the operational gains were more cyclical than claimed.
Several swing factors flagged last quarter deserve attention. Management said growth over market, excluding complete vehicles, would soften in the second half toward 1% to 3%. It pointed to end-of-production on the Ford Escape, Toyota Supra and BMW Z4, along with lower full-size truck and German OEM volumes. China is a second pressure point. Magna cut its regional production estimate by 800,000 units, and its China business leans heavily on domestic automakers at a time when Western and Japanese brands are losing share there. Memory chip pricing is a newer risk, with a modest unrecovered cost already assumed for the back half. Any sign that the hit is growing would land directly on margins. On the positive side, tariffs were recast as roughly neutral for the year, and Power & Vision had just returned to growth with strong incremental margins. Continued momentum in that segment would be the cleanest evidence that operational improvements are taking hold.
Free cash flow is the other proof point. The second quarter's $617 million more than doubled the prior-year figure, and the full-year target rose to a $1.8 billion midpoint. Steady conversion would also sustain the buyback pace that helped lift per-share results.
Sentiment has cooled noticeably, slipping from moderately bullish before the last report to barely positive now. The stock sits near the bottom of its post-earnings range of $61.72 to $73.22 and just above its 200-day moving average. That suggests investors are bracing for the second-half slowdown rather than paying up for the raise. With an Investor Day in November, management has every incentive to reaffirm its targets confidently. The verdict will turn on one issue: whether Magna can grow earnings strongly on flat sales, demonstrating that its margin gains come from operations rather than volume.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-08 | |
| Sep-18 | |
| Sep-15 | |
| Sep-08 | |
| Sep-01 | |
| Aug-07 | |
| Jul-31 | |
| Jul-31 | |
| Jul-31 | |
| Jul-28 | |
| Jun-22 | |
| Jun-03 | |
| May-19 | |
| May-09 |
