Magna Beats On Margins And Buybacks, But A Shrinking Top Line And Held EPS Midpoint Temper The Quarter
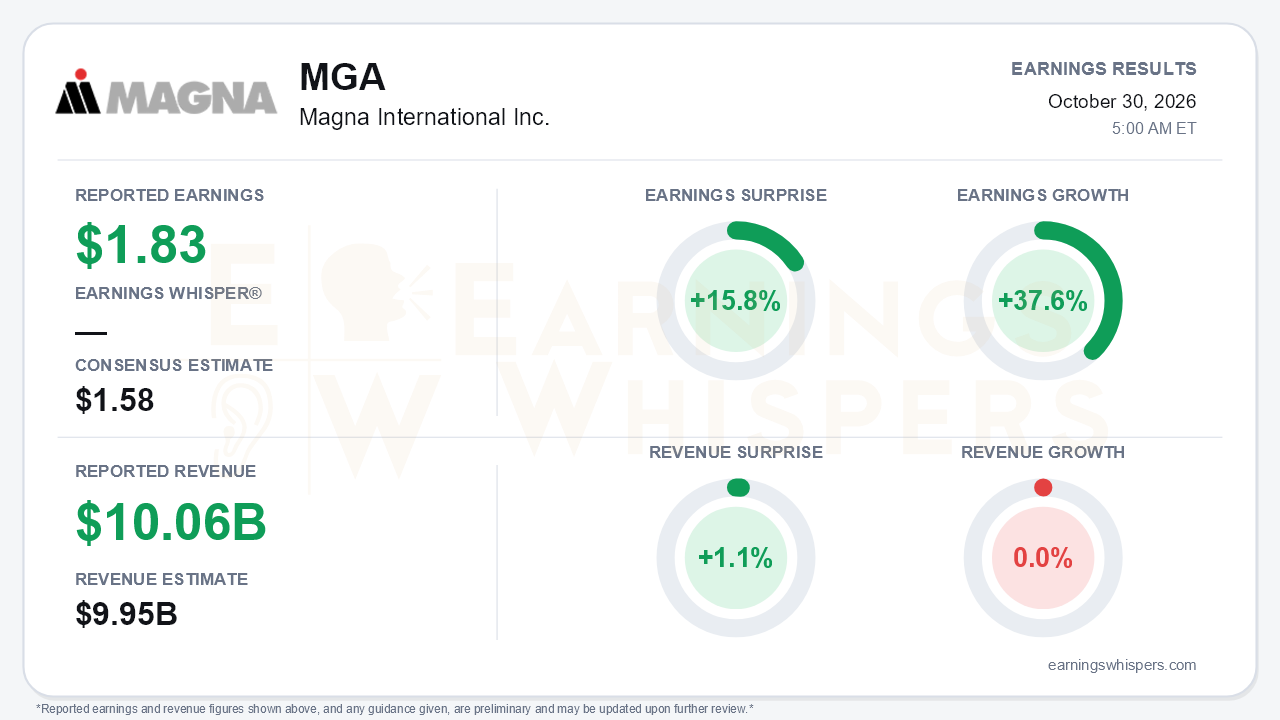
Magna International delivered a clear third-quarter beat. Adjusted EPS of $1.83 topped the $1.58 consensus by 15.8% and grew 37.6% year over year, while revenue of $10.059 billion exceeded the $9.95 billion estimate by 1.1%. Earnings growth re-accelerated from the roughly 29% pace of the second quarter. The central tension is that this earnings strength is coming from cost execution, financial engineering and timing benefits, while the revenue base and the outlook are deteriorating. Magna beat by $0.25 a share and still only held its full-year Adjusted EPS midpoint at $7.00. That says a lot about what management expects in the fourth quarter.
The quality of the beat deserves scrutiny. Earnings Whispers' normalized comparison shows revenue flat year over year. Magna's own reported figures show a different picture: sales fell 4% from $10.46 billion, and organic sales were down about 2.1%. The causes included lower light-vehicle production in North America and China, ended programs, the Lighting and Rooftop divestitures, and price concessions. That is a sharp reversal from roughly 3% growth in each of the first two quarters. Adjusted EBIT rose 11% to $683 million and margin expanded 90 basis points to 6.8%, so the operating improvement is real. But the gap between 11% EBIT growth and 38% EPS growth was filled below the line:
- net interest expense fell to $35 million from $65 million;
- the tax rate came down;
- diluted shares dropped to 266.0 million from 281.8 million.
Management also acknowledged that some favorable commercial items were pulled forward from the fourth quarter into the third and are expected to turn negative. GAAP EPS was $1.44, up 33%. That figure includes $79 million of other expense, much of it a $76 million Power & Vision restructuring charge tied to European overcapacity.
Beneath the consolidated number, the segment story is uneven. Body Exteriors & Structures lifted margin to 9.3% from 7.4%, and Power & Vision rose to 7.6% from 6.1%. Seating went the other way: margin fell to 2.2% from 4.1% as sales dropped 18%, pressured by changeovers at Ford Louisville and BMW Spartanburg. Margin progression through the year has been steady, from 5.4% in Q1 to 6.2% in Q2 to 6.8% in Q3. Operational excellence initiatives are tracking about 50 basis points of benefit versus the 35-40 basis point target. On demand, the news is worse. Growth over market narrowed to about 0.5% consolidated, down from 3% in Q2. The full-year view has been cut to roughly flat (about 1% excluding Complete Vehicles) from the prior 1-3%. Commodity and DRAM inflation escalated to a roughly 50 basis point margin headwind, and management expects a similar or larger drag in the fourth quarter.
The revised outlook reflects this split. The parts of guidance Magna controls were raised:
- free cash flow lifted to $1.85-$1.90 billion, the third increase this year, helped by capex trimmed to about $1.5 billion;
- tax rate guidance lowered to about 22%.
The market-driven parts were cut or narrowed:
- sales lowered to $41.2-$42.0 billion;
- China production assumption cut by another 800,000 units, with German OEMs in China down about 28%;
- Adjusted EBIT margin trimmed at the top to 6.3-6.5%;
- EPS narrowed to $6.85-$7.15.
This contrasts with the second-quarter call, when margin, EPS and cash flow guidance were all raised. Planned fourth-quarter downtime at key North American and European customers adds further pressure. There are offsetting catalysts:
- a new 25.8 million-share buyback (about 10% of float) after the prior program was completed in October;
- Waymo upfitting ramps in Arizona and new Xpeng and Arcfox models in Complete Vehicles;
- a new driveline award for 2028;
- management describing 6.4% as a structural margin base, with another 35-40 basis points of operational gains targeted for 2027.
The November 11 Investor Day will be the venue for that longer-term framework.
Investors were already leaning skeptical heading into the print. Earnings Whispers sentiment swung from modestly positive (0.15) to modestly negative (-0.14), a meaningful shift. Shares closed at $64.70 the day before the report, down 5.9% since the open after the July release. The stock had set a 52-week high of $73.22 in August and was 11.6% below it, sitting just 4.8% above its September low and 3.3% above its 200-day moving average. In other words, the stock had given back its summer rally before the quarter was even reported. Internal trend readings are mixed, with momentum positive but AVWAP negative.
The bottom line is that Magna is proving it can grow earnings and cash flow without help from volumes. Margin discipline, lower interest costs and aggressive buybacks are doing the work. But revenue has turned negative, growth over market is evaporating, commodity costs are rising, and part of the Q3 upside was borrowed from Q4. Bulls have a credible margin and capital-return story. Bears have legitimate ammunition in the top line and an EPS midpoint that did not budge despite a sizable beat. The Investor Day framework will need to show that margin expansion can outrun a soft production backdrop into 2027.
Read our earnings preview for Magna International Inc.: https://www.earningswhispers.com/article/MGA/21291
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-30 | |
| Oct-30 | |
| Oct-30 | |
| Oct-22 | |
| Oct-08 | |
| Sep-18 | |
| Sep-15 | |
| Sep-08 | |
| Sep-01 | |
| Aug-07 | |
| Jul-31 | |
| Jul-31 | |
| Jul-31 | |
| Jul-28 |
