Piper Sandler Faces Its Promised Slowdown As Tough Comps Test A Record First Half
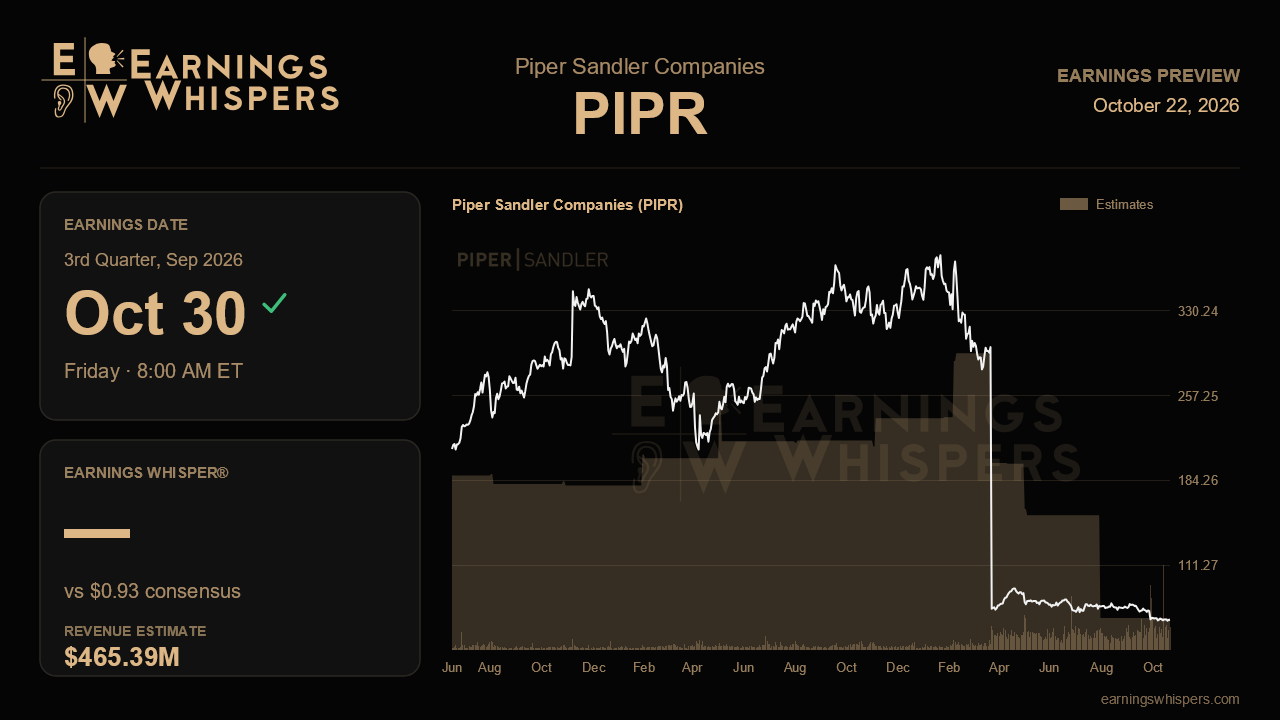
Piper Sandler heads into its third-quarter report having already told investors the good times would cool. After a record first half built on surging advisory fees and a sharp rebound in corporate financing, management warned that the back half would not match the roughly 30% growth pace of the front half, largely because the second half of last year set a very high bar. The market appears to have taken that warning to heart and then some. The open question on October 30 is whether the slowdown looks like the orderly, comp-driven deceleration management described, or something softer.
The Street is looking for revenue of about $465.4 million, roughly 3.1% below the year-ago quarter and a step down from the $495.5 million reported last quarter. That lines up reasonably well with management's guidance that third-quarter revenue would come in about in line with last year's third quarter, with consensus sitting a touch on the cautious side of flat. Consensus EPS of $0.93 compares with $1.04 last quarter and $1.00 the quarter before. The headline year-over-year EPS decline of nearly 76% looks dramatic, but it sits awkwardly beside a revenue forecast down only about 3% and a quarterly run rate that has hovered near $1. That suggests the comparison reflects a change in per-share basis rather than a collapse in profitability, and the sequential trend is the more useful yardstick.
The most important evidence will come from advisory. The segment posted a record $274 million in the second quarter, up 34%, marking six straight quarters of year-over-year growth. Management expected that growth rate to slow, and it flagged that results increasingly hinge on lumpy, large-fee deals closing in the fourth quarter. A third quarter that holds advisory roughly flat against last year would validate the plan; a meaningful drop would raise doubts about how much of the fourth quarter is really in the pipeline. Commentary on middle-market M&A, which management called gradual, and on bank M&A, where Piper ranked first by count and value in the first half even as large-scale bank deals remained scarce, will shape views of 2027. Readers should also listen for any sign that money-center banks returning to middle-market advisory are pressuring fees or win rates.
Newer catalysts deserve a progress check too. The private capital advisory group just had its best quarter ever on secondaries, and the firm moved two senior bankers to strengthen private equity coverage. Corporate financing, up 65% in the first half after management had expected it to decline, is another swing factor. Fixed income remains sensitive to short-term rates, with about half the book tied to bank clients.
Margins may matter as much as revenue. Operating margin climbed to 21.8% last quarter, and first-half operating income grew 42% on 22% revenue growth, helped by a non-comp ratio that improved 230 basis points to 17.5%. Holding the comp ratio near 61.5% and showing that early AI tooling efficiencies persist on flatter revenue would show the operating leverage is structural rather than purely volume-driven.
Sentiment has soured markedly, with bearish readings roughly tripling from the prior quarter, and the shares have fallen 11.4% since the last report while the S&P 500 gained 5%. At $64.40, the stock trades near the bottom of its post-earnings range of $61.35 to $78.80, and that entire range sits below the prior quarter's. Expectations, in other words, are subdued. The central issue is whether Piper can show that flat revenue against a brutal comparison still comes with resilient margins and a credible fourth-quarter deal pipeline. If it can, the record first half looks like a foundation rather than a peak.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-02 | |
| Oct-02 | |
| Sep-29 | |
| Sep-29 | |
| Sep-29 | |
| Sep-28 | |
| Sep-28 | |
| Sep-25 |
