Pinnacle Financial Beats On BHG Windfall And Hiring Momentum, But A Drifting Margin Keeps The Merger Story Unfinished
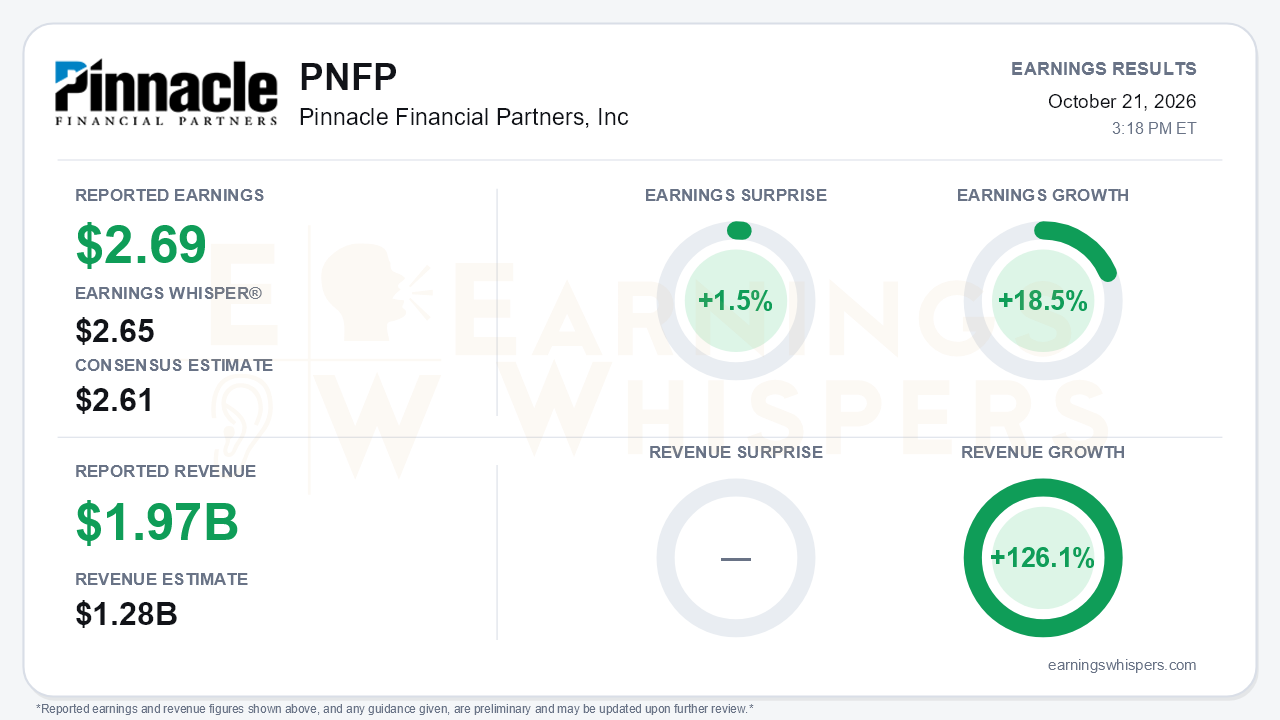
Pinnacle Financial Partners delivered a clean-looking third-quarter beat, but the composition of that beat matters more than its size. Adjusted EPS of $2.69 topped the $2.61 consensus by 1.5% and cleared the $2.65 Earnings Whisper number. Earnings grew 18.5% from a year ago, and the sequential path is improving, with adjusted EPS rising from $2.39 in the first quarter to $2.50 in the second and $2.69 now. GAAP EPS was $2.40, as merger costs of $56 million continued to weigh on reported results. The central tension is that the quarter's upside came largely from fee income and one-time items, while net interest margin, the core earnings engine, slipped for a second straight quarter.
The headline revenue figures need context. The Earnings Whispers revenue of $1.965 billion matches gross interest income plus non-interest revenue. By contrast, the company's reported total revenue, net of interest expense, was $1.312 billion, or $1.318 billion adjusted. The 53.5% revenue surprise against a $1.28 billion consensus therefore appears to reflect differing revenue definitions rather than a blowout. On a net basis, revenue was only modestly ahead of that estimate. The 126.1% year-over-year growth is likewise a product of the Synovus merger, which closed January 1 and more than doubled the balance sheet.
The quality of the beat deserves scrutiny. Adjusted non-interest revenue jumped $53 million sequentially, for two reasons:
- Income from the equity-method stake in BHG doubled to $48 million from $24 million on record production.
- A $23 million gain on an equipment lease payoff was included in adjusted results.
That lease gain alone exceeds the roughly $0.08 margin by which Pinnacle beat consensus. Meanwhile, adjusted expenses rose 4% to $690 million on an incentive-accrual true-up and accelerated hiring. Provision expense climbed to $86 million from $63 million as management leaned on a more adverse macroeconomic outlook.
Beneath the noise, the operating franchise looks healthy:
- Loans grew $1.7 billion, roughly 8% annualized, led by commercial and industrial lending.
- Core deposits excluding public funds rose about $2.6 billion, versus total deposit growth of only $795 million in the second quarter.
- Net interest income rose 3%, its third straight quarter of growth above 2%.
- New-production loan spreads widened about 10 basis points.
- The adjusted tangible efficiency ratio improved to 48.9%, and adjusted ROTCE reached 18.3%.
Hiring is the standout. Pinnacle added 96 revenue producers versus 74 in the second quarter, bringing the year-to-date total to 222, and now expects to clear the top of its 225–250 target. Banker retention ticked up to 95%, and Chief Banking Officer Rob McCabe agreed to stay an additional year. Management's tone was notably more assertive, and the McCabe extension helps defuse investor worries about departures among legacy Pinnacle bankers.
The margin is where bears have legitimate ammunition. Net interest margin fell to 3.40% from 3.44% in the second quarter and 3.53% in the first. Management attributed the decline to rising deposit costs and a wholesale-funded liquidity build. The full-year margin outlook has been trimmed repeatedly:
- 3.45%–3.55% in the fourth-quarter outlook
- about 3.50% in the first quarter
- 3.44%–3.47% in the second quarter
- 3.44%–3.46% now
Management expects a slight fourth-quarter expansion helped by the September Fed hike. However, it also flagged slight margin pressure in 2027 from building high-quality liquid assets, debt issuance and wholesale-funded growth. Higher rates are also softening commercial real estate demand.
Credit is steady but showing early signs of caution:
- Net charge-offs were 0.23% and nonperforming assets were flat at 0.50%.
- Criticized loans ticked up.
- The reserve is now weighted 45% toward below-consensus economic scenarios.
- The share of clients expecting business declines rose to 15% from 11%.
Capital adds another constraint. CET1 rose only 8 basis points to 10.01%, buybacks remain paused until 10.25%, and tangible book value per share of $61.86 still sits below the $63.71 level from before the merger.
On the positive side, guidance moved up where it mattered for fees:
- BHG income is now guided to $150–$160 million, up from $110–$120 million in July.
- Adjusted revenue is expected slightly above the midpoint of its range.
- Loan growth is tracking the top of the 9%–11% range.
- Revenue synergies reached $20 million year to date.
- AI-assisted conversion testing keeps the systems integration on track for March 2027.
Investor sentiment improved meaningfully heading into the report, moving from mildly negative (-0.115) to essentially neutral (+0.008). That leaves expectations balanced rather than stretched. The stock has done little since the July report, up 2.6% from the post-release open to $98.21 and sitting just 1.7% above its 200-day moving average. Price and AVWAP trend readings remain negative, consistent with a market that has not yet rewarded the integration progress.
The bottom line is that Pinnacle's merger execution is running ahead of plan on hiring, deposits, fee income and efficiency, but the earnings beat leaned on BHG strength and a one-time lease gain while the margin kept eroding. Until net interest margin stabilizes and capital builds enough to restart buybacks, the stock's lukewarm technical position looks like a fair reflection of a good franchise with a still-unresolved spread story.
Read our earnings preview for Pinnacle Financial Partners, Inc: https://www.earningswhispers.com/article/PNFP/20477
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 18 min | |
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-07 | |
| Sep-30 | |
| Sep-22 | |
| Sep-22 | |
| Aug-31 | |
| Jul-30 | |
| Jul-27 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 |
