Cavco's Record Backlog Meets A Margin Test As Stock Slides Toward Post-Earnings Lows
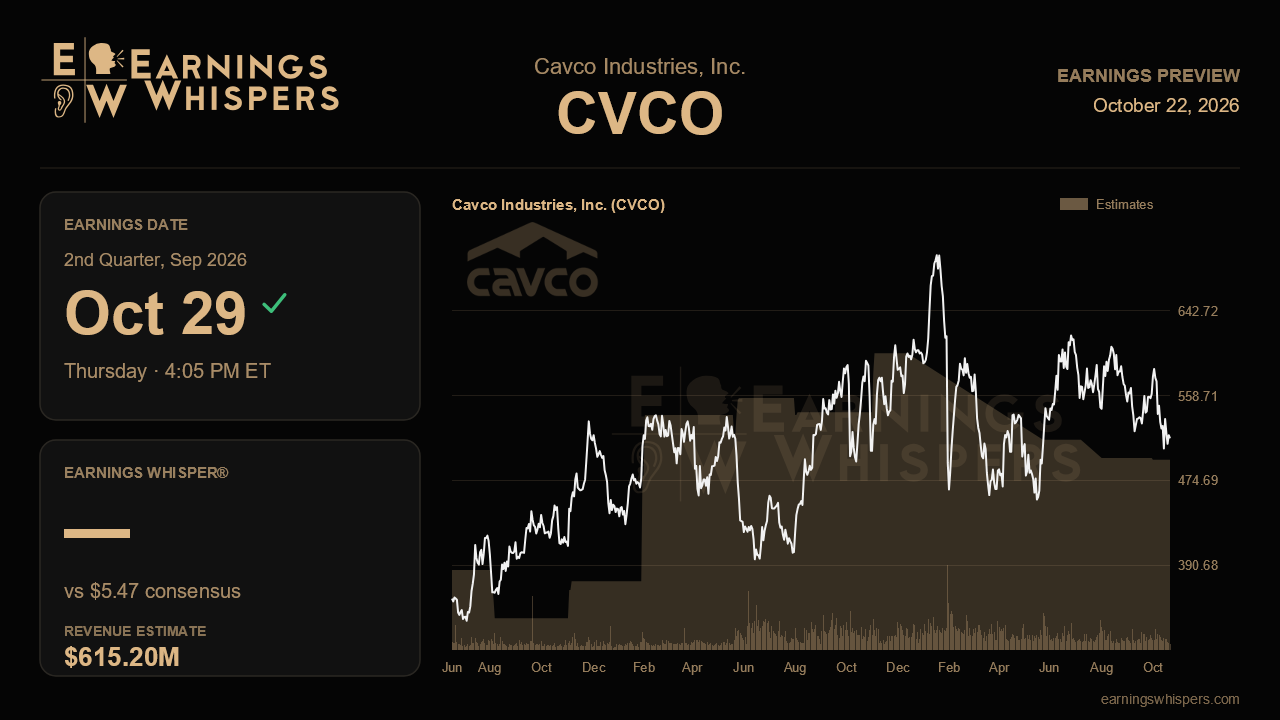
Cavco Industries enters its fiscal second-quarter report with a split personality. Demand looks better than at any point in the past year, with record shipments and an order book that swelled by half in a single quarter. Yet the stock has drifted lower since that upbeat report, because each extra home has been earning less. The release after the close on October 29 should show whether volume can begin to outrun the cost pressures that have been eroding profit.
The Street expects earnings of $5.47 per share on revenue of $615.2 million. That revenue figure would be up 10.5% from a year ago but barely above the $610 million Cavco posted last quarter, its first ever above $600 million. Earnings, by contrast, are projected to fall 16.5% from the $6.55 earned in the year-ago period and to edge only slightly above last quarter's $5.43. Put simply, analysts are modeling a business that sells more homes but keeps less of each sale. Management has not issued formal guidance, so the prior call is the best guide to whether that math is too cautious or too generous.
On that call, the story was momentum. Orders rose by double digits sequentially in every region and across all three channels, from builders and developers to community operators and retail. Backlog stretched to seven to nine weeks, from five to seven the quarter before, and plant utilization climbed to roughly 75%, leaving ample room to run harder. Management sounded ready to push factories to produce against that backlog. Against that backdrop, a consensus revenue estimate implying roughly 1% sequential growth looks like a modest hurdle. A clear beat on shipments and revenue would validate the demand inflection. A flat top line, or a backlog that shrinks back toward prior levels, would suggest the spring and summer surge was a catch-up rather than a trend.
Margins are where the real argument lies. Factory-built gross margin slipped to 20.8% from 22.6% a year earlier, pressured by higher per-unit costs, tariff and inflation drag that management pegged at around $5 million a quarter and rising, and fresh price competition at company-owned stores in Texas, where buyers browsed more but closed less. Higher utilization should, in theory, spread fixed costs and steady margins. If gross margin stabilizes or improves even modestly, the operating leverage thesis gains credibility. Another decline would signal that pricing power is weakening just as volume improves. The tax line also matters: the expiration of Energy Star credits at the end of June means this is the first full quarter without them, so an effective rate in the mid-20s is already the new normal rather than a surprise. Financial services, which grew revenue 13.3% last quarter as loan sales ramped under a new forward-flow arrangement, could provide a useful cushion.
The market has not been generous. Shares are down 4.6% since the last report while the S&P 500 gained 3.8%, and at $516.25 the stock sits below its 200-day moving average of about $554 and only about 2% above its post-earnings low of $505.04. Sentiment has warmed, moving from mildly bearish ahead of last quarter to mildly bullish now, but the price action shows that enthusiasm over the newly signed Road to Housing Act and progress toward a chattel loan secondary market has not translated into buying. That leaves a stock pricing in skepticism about profitability rather than demand.
The central question is whether Cavco's record order book can finally produce operating leverage. Strong volume alone may not be enough for a stock that has already looked past it. What would change the conversation is evidence that gross margin has found a floor, that Texas pricing pressure is contained, and that tariff costs are not climbing faster than plants can absorb them. Deliver that, and the demand story regains its earnings power. Miss on margin again, and the record backlog risks being viewed as revenue without reward.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Sep-29 | |
| Sep-17 | |
| Sep-09 | |
| Aug-07 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-23 | |
| Jun-01 | |
| Jun-01 | |
| May-22 | |
| May-21 | |
| May-21 |
