Cavco's Record Quarter Beats Big, But A One-Time Refund And Steel Inflation Complicate The Backlog Story
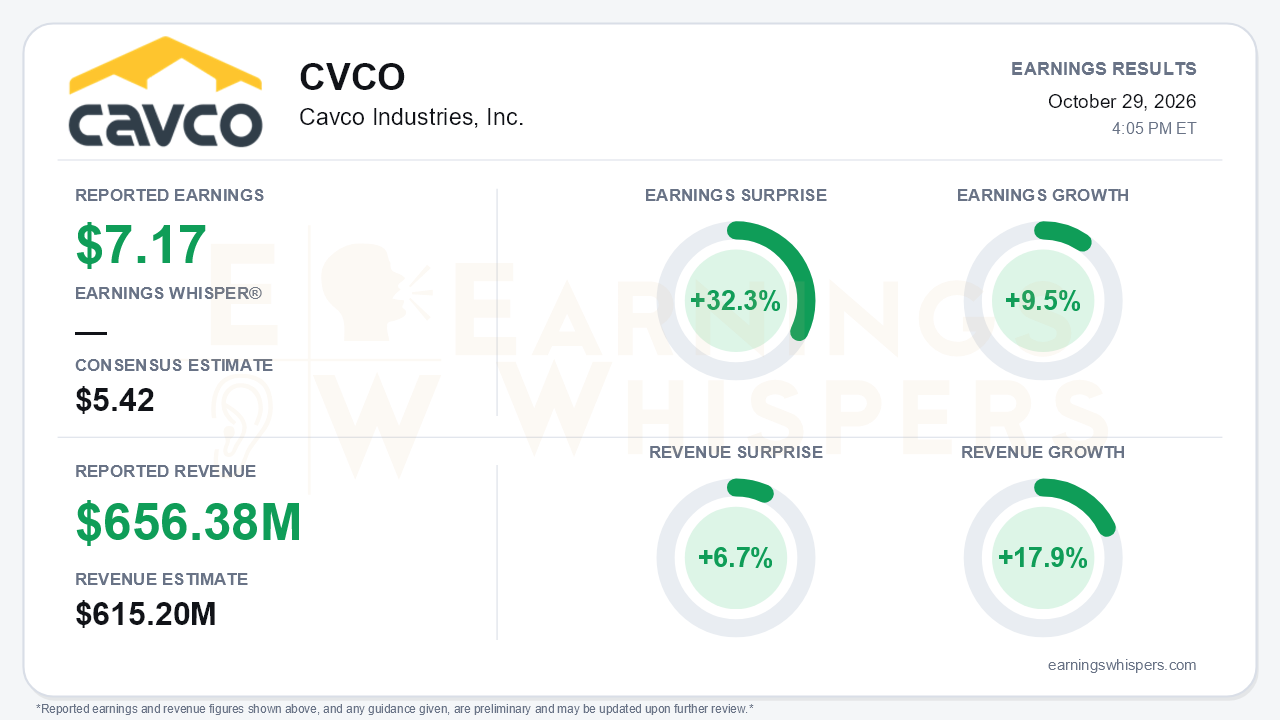
Cavco Industries delivered a headline beat that looks emphatic on paper. Fiscal second-quarter earnings of $7.17 per share topped the $5.42 consensus by 32.3%, and revenue of $656.4 million beat the $615.2 million estimate by 6.7%. Earnings grew 9.5% year over year and revenue grew 17.9%, a clear acceleration from a first half in which pre-tax profit had been shrinking. The quality of the beat still deserves scrutiny. The release discloses a one-time $7 million return of D&O insurance premium that added $0.70 to diluted EPS. Without it, earnings would have landed roughly in line with the prior-year $6.55. That would still have been well ahead of consensus, but it would not have been a growth quarter.
Beneath the headline, the top line is genuinely strong while profitability is merely stabilizing. Home shipments rose 15.3% to a record 5,972, and net revenue per home increased 2.7% to $106,118. Much of the volume gain, however, came from lapping the American Homestar acquisition. Management said legacy same-plant shipments grew only low single digits. Factory-built gross margin fell to 21.1% from 22.9% a year ago, and consolidated gross margin slipped to 22.5% from 24.2%. Lower interest income ($3.6 million versus $5.0 million) and a higher effective tax rate (24.4% versus 22.1%) also weighed on results. Net income rose only 5.8%, so the gap to 9.5% EPS growth came from buybacks: diluted shares fell to 7.73 million from 7.99 million, and the company repurchased another $30 million in the quarter.
The sequential picture is more encouraging, and the call leaned into it. Revenue has climbed from $550.1 million in the fiscal fourth quarter to $610 million in the first quarter and $656.4 million now. Factory-built gross margin edged up 30 basis points sequentially to 21.1% after falling for several quarters. Management attributed that improvement to real price increases on both single- and multi-section homes rather than mix. Pre-tax profit swung to 9.1% growth from a 14.6% decline in the prior quarter. Operating cash flow improved to $96.4 million, and unrestricted cash reached $272 million. Financial services was a quiet contributor, with gross margin of 60.2% on higher loan sales and retained insurance premium.
The most important new development is demand visibility. Backlog rose $50 million sequentially to $348 million, representing 8-10 weeks of production, up from 4-6 weeks three quarters ago. Management called it the largest since fiscal 2022-23 and said it is 63% higher year over year. Data center workforce housing became a tangible contributor this quarter. Those units run roughly $70,000-$100,000 wholesale, are mostly non-HUD code, and have been concentrated in remote Texas but are spreading to other regions. Management described their gross-margin impact as neutral and said they allow plants to lean into production through the seasonally slow winter. Policy tailwinds add optionality: the ROAD to Housing Act, the Grande Arbor off-chassis HUD-Code home, and a new HUD/FHFA task force on factory-built housing regulation.
Bears have legitimate ammunition, though. Orders fell sequentially from a very strong first quarter. Management admitted that visibility into workforce housing demand is low, including its size, duration, and the risk of delays or cancellations. Steel is up roughly 150% since the start of the year and carries availability risk, and the CFO would not assure that winter pricing will keep pace with inflation. Mix is shifting toward single-wides as affordability strains under higher prices. No formal guidance was provided. Capital spending also tripled to $29.7 million for the quarter, raising the stakes on sustained volume, even though utilization remains about 75%.
The market had not been positioned for a breakout. Shares stood at $547.25 heading into the report, up just 1.2% from the opening price after the July release and about 0.7% below the 200-day moving average of $551.21. Investor sentiment was essentially unchanged at a mildly negative -0.14. The Earnings Whispers price and AVWAP trend readings both remain negative, consistent with a stock that has gone sideways despite record revenue.
The bottom line is that Cavco produced a real top-line acceleration and the strongest demand visibility it has had in years. However, the headline EPS beat is inflated by a $0.70 one-time benefit, and year-over-year margins are still lower. The investment case now rests on whether a growing, workforce-housing-assisted backlog and continued pricing can outrun steel inflation through the winter. That is the central tension, and this quarter offered evidence on both sides rather than a resolution.
Read our earnings preview for Cavco Industries, Inc.: https://www.earningswhispers.com/article/CVCO/21325
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-29 | |
| Oct-29 | |
| Oct-22 | |
| Oct-22 | |
| Sep-29 | |
| Sep-17 | |
| Sep-09 | |
| Aug-07 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-23 | |
| Jun-01 | |
| Jun-01 |
