Credit Acceptance's Volume Rebound Faces Its First Real Test As Credit Revisions Linger
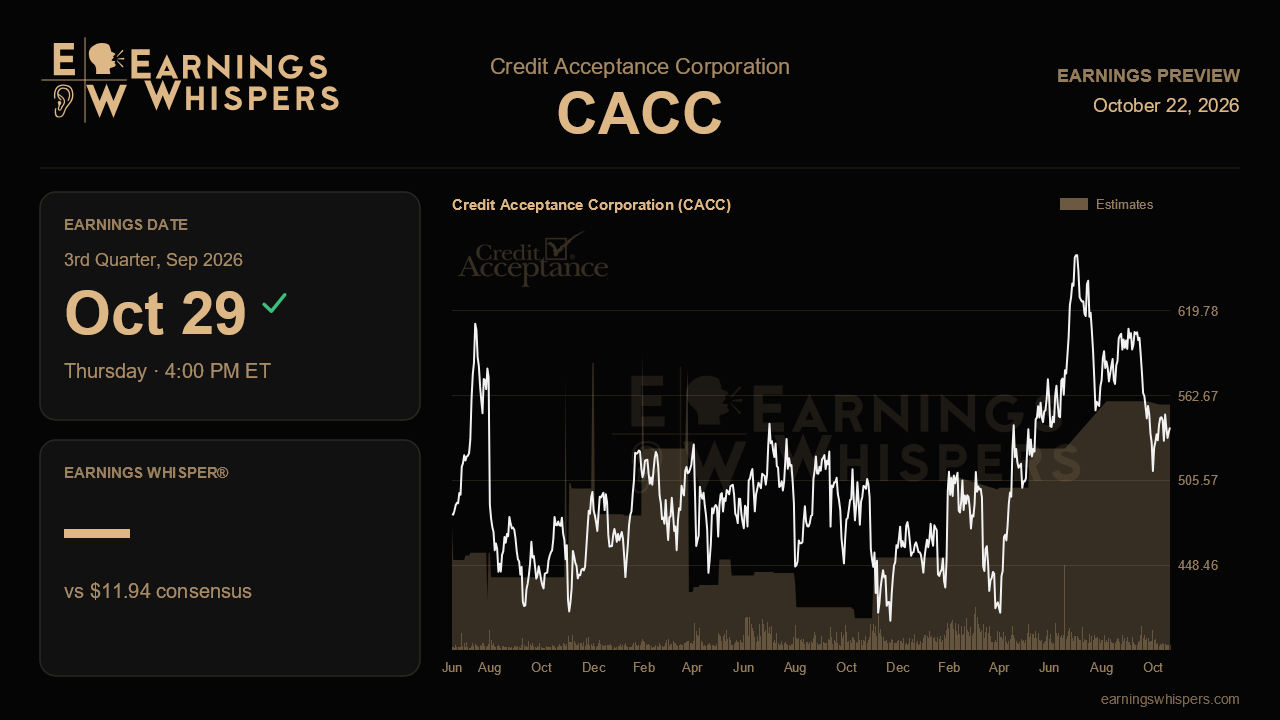
Credit Acceptance enters its third-quarter report with something it has not had in a long while: a growth story. After four straight calls in which unit volume declines narrowed, from a 16.5% drop a year earlier to just 1% last quarter, monthly volume turned positive in June and jumped more than 20% in July. The stock has not celebrated. Shares have fallen 8.9% since the last report while the S&P 500 was essentially flat, which tells you the market is treating the rebound as a promise rather than a fact. When the company reports after the close on October 29, the question is whether the summer surge was the start of a trend or mostly the product of an easy comparison.
The Street is looking for earnings of $11.94 per share, which would be roughly 16% above the $10.28 earned in the same quarter last year. That is solid growth, though it sits slightly below the $12.12 adjusted figure posted last quarter, so consensus is not demanding a sequential step up. Credit Acceptance does not issue formal guidance, which puts more weight on the operating metrics in the release. Revenue has been remarkably steady, at $587.4 million last quarter against $582.4 million a year earlier, so the earnings story here is really about loan volume, yield and provisions rather than the top line.
Volume is the first test. Management credited the turnaround to a data-driven overhaul under CEO Hegde: a refined, AI-enabled scorecard, deeper integrations with Route 1, DealerTrack and DealerCenter that are pulling in franchise dealers, and a newly opened segment for vehicles with light structural damage. If those initiatives are real, unit and dollar volume should keep growing year over year across the full quarter, not just in a single standout month. Active dealers topped 11,000, a second consecutive record, but volume per dealer fell 3.8% and market share of 4.9% still trailed last year's 5.3%. A quarter in which dealer count rises and per-dealer productivity also improves would be the strongest validation of the strategy. More dealers sending fewer loans each would suggest the company is buying breadth rather than winning share.
Credit is the second, and arguably more important, test. Forecasted net cash flows were revised down by $39.1 million last quarter, worse than the $9.1 million trim in the first quarter, and provisions tied to forecast changes rose to $82 million from $54 million. A recurring culprit is prepayments, which have run slower than forecast for several quarters without management resetting its assumptions. The young 2025 vintage was also running slightly behind expectations, within 10 basis points. A smaller revision this quarter would support the idea that credit is stabilizing. Another step up would raise an awkward question: is the company loosening standards to manufacture growth, especially with the new scorecard and the damaged-vehicle segment still early in their lives?
That concern ties into a leadership transition that drew pointed questions last quarter. CFO Jay Martin retired in late July, Joe Bilante now holds the role, and former CEO Ken Booth has left the board. Some investors worry the new team lacks deep subprime auto experience, so clean execution on underwriting will matter as much as the volume numbers. Bearish sentiment has eased, from 7.7% to 3.3%, but remains negative. The stock sits at $541.25, just above its 200-day average of $534.93 and closer to the bottom of its post-earnings range of $506.55 to $621.52 than the top.
The verdict will come down to whether growth and credit can improve together. Sustained year-over-year volume gains paired with a shrinking forecast revision would confirm that the new playbook is working and could close the gap between improving fundamentals and a lagging share price. Growth accompanied by heavier provisions would suggest the rebound is being paid for with tomorrow's losses.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-07 | |
| Sep-24 | |
| Sep-22 | |
| Sep-21 | |
| Sep-17 | |
| Sep-15 | |
| Aug-20 | |
| Aug-13 | |
| Aug-13 | |
| Aug-04 | |
| Aug-04 | |
| Jul-28 | |
| Jul-27 |
