Credit Acceptance Beats On Adjusted Earnings As Origination Boom Collides With A $291 Million Forecast Write-Down
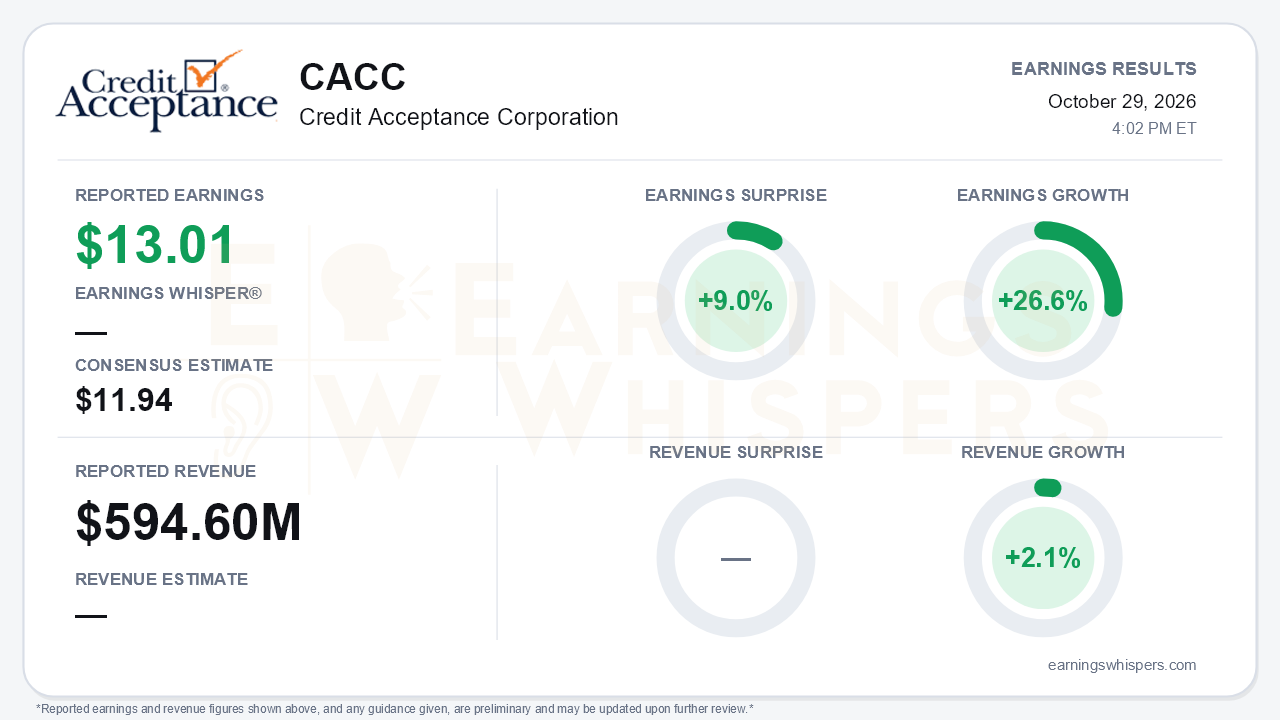
Credit Acceptance delivered two very different quarters at once. On the adjusted basis Earnings Whispers tracks, the subprime auto lender earned $13.01 per share, beating the $11.94 consensus by 9.0%. That was up 26.6% year over year and a clear step up from $12.12 in the second quarter and $10.71 in the first. Under GAAP, however, the company swung to a net loss of $56.6 million, or $5.43 per share, from net income of $108.2 million a year ago and $135.9 million in the second quarter. The cause was a methodology change that cut forecasted net cash flows by $291.2 million, or 2.5%. That is the central tension: originations just inflected sharply higher at the same moment management admitted its recent loan books will collect less than it told investors.
The quality of the beat deserves scrutiny. Credit Acceptance's adjusted earnings use a floating yield adjustment, which recognizes changes in expected cash flows over the remaining life of the loans rather than immediately. Under GAAP, provision for credit losses jumped 170% to $410.9 million, including $281.9 million tied to forecast changes. The adjusted framework absorbs that hit gradually. The adjusted return on capital of 9.9% and the 2.1% revenue growth therefore do not yet reflect the lower collection expectations. Analysts pressed management on how much the adjusted yield, currently 19.2% of adjusted average capital, will compress as the write-down flows through. Management did not quantify it. The earnings that beat consensus this quarter are partly built on economics the company has already marked down.
The credit revisions were broad. Forecasted collection rates fell for every vintage from 2023 through 2026:
- The 2025 cohort dropped 2.0 points in a single quarter, to 64.9%.
- Loans written in the first half of 2026 were cut 250 basis points, to 64.7%.
- Even loans originated in the third quarter itself already sit 90 basis points below their initial forecast.
Management said the adjustment formalizes small but persistent quarterly underperformance, concentrated in lower scorecard bands and largely in loans assigned before the new scorecard launched in the second quarter. That context matters, because just one quarter earlier management had described increasing forecast stability. Bears have legitimate ammunition on forecasting credibility.
The growth story, though, is real and accelerating. Unit volume rose 37.7% and dollar volume 51.0% to $1.4 billion, after declines of 1.0% in units in the second quarter and 4.3% in the first. Active dealers hit a record 12,093, and volume per active dealer swung to +15.2% from -3.8% in the second quarter. Management said core market share climbed to 5.4% from 4.9% in the second quarter. It credited aggregator integrations with RouteOne, Dealertrack and DealerCenter, sales-force segmentation, and the new scorecard, and its tone was markedly more confident. Costs moved the right way too: operating expenses fell 9.7%, with roughly another 6% headcount reduction. The company also completed a $600 million securitization at its tightest spreads since late 2021.
The risk is that growth is accelerating fastest exactly where seasoning is thinnest. Several features of the new business raise the bar for execution:
- Third-quarter loans carry higher advance rates (46.6%) and a lower initial spread.
- Purchased loans rose to 35.7% of dollar volume, and their weaker initial forecasts helped push provision on new assignments up $65.1 million.
- Early performance on new-scorecard loans was described as encouraging, but those loans are unseasoned.
- Prepayments remain below historical norms.
Capital allocation adds a further wrinkle. The company spent $161.6 million repurchasing 2.6% of its shares even as shareholders' equity slipped to $1.39 billion from $1.52 billion at year-end. Liquidity also eased to $1.2 billion from roughly $1.4 billion. No formal guidance was offered.
The market setup is more complicated than the surprise implies. Investor sentiment remained slightly negative but improved modestly, from -0.077 to -0.038, which suggests skepticism softened rather than reversed. Shares closed at $575.78, down 3.1% from the open after the August report. They remain about 7.1% above the 200-day moving average of $537.47, so the market has not abandoned the stock despite drifting lower over the quarter. Trend readings are modestly constructive, with AVWAP positive and price trend neutral. Even so, the stock entered this report without having priced in a write-down of this size.
The bottom line is that Credit Acceptance just posted its strongest origination quarter in years and a solid adjusted beat, but it paid for it with a credibility cost. The $291 million forecast cut shows recent vintages were underwritten too optimistically. The adjusted earnings stream will likely absorb that over time, and the new growth is being written on an unproven scorecard at higher advance rates. Investors who focus on volume and market share have a credible growth story. Those who focus on collection forecasts will want several quarters of stable vintage curves before trusting it.
Read our earnings preview for Credit Acceptance Corporation: https://www.earningswhispers.com/article/CACC/21324
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-22 | |
| Oct-22 | |
| Oct-07 | |
| Sep-24 | |
| Sep-22 | |
| Sep-21 | |
| Sep-17 | |
| Sep-15 | |
| Aug-20 | |
| Aug-13 | |
| Aug-13 | |
| Aug-04 |
