Telesat's Lightspeed Backlog Meets Its Deadline: Refinancing Clarity Needed Before December Maturities
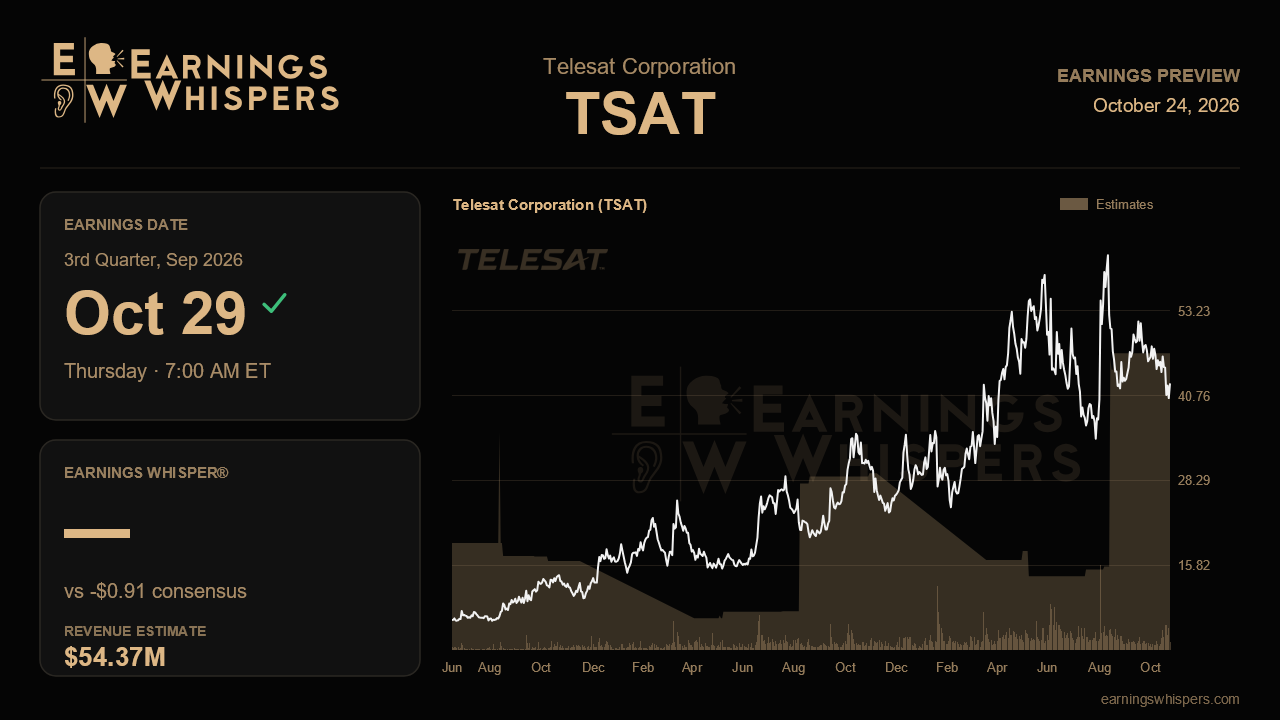
Telesat heads into its third-quarter report with two stories pulling in opposite directions. Its low-Earth-orbit Lightspeed business has just had the best stretch in its history. Meanwhile, the legacy geostationary operation keeps shrinking, and US$1.7 billion of Telesat Canada debt comes due in December. With that maturity roughly two months away, this release is less about the quarter's numbers than about whether management can show the bridge from today's eroding cash generator to tomorrow's constellation is still intact.
The Street expects a loss of $0.91 per share on revenue of about $54.4 million. That loss would be roughly 47% narrower than the $1.73 loss a year ago. Revenue, however, would fall nearly 26% from $73.4 million and slip again from last quarter's $57.4 million. Per-share results have been badly distorted by non-cash swings in the fair value of the company's warrants, so the reported last quarter figure of $9.83 says little about operations. Revenue and adjusted EBITDA from the geostationary fleet are the cleaner gauges. Management has not issued fresh formal guidance for the period, so consensus is essentially a bet that the GEO decline continues at a similar pace rather than accelerating.
That bet looks reasonable given what management said last time. GEO revenue was falling about 26% year over year and segment adjusted EBITDA was down around 30%. Utilization sat near 60%, and the retirements of Anik F4 and Telstar 14R were flagged as a lingering drag. Non-renewals from broadcast and enterprise customers added to the pressure. There was one modest bright spot: GEO backlog ticked up to $900 million on a five-year broadcast extension, its first increase in some time. A result in line with consensus would confirm that erosion is predictable rather than worsening. Any further slide in utilization or a weaker margin would challenge the idea that the legacy business can keep funding the transition.
The Lightspeed side carries the bullish case. Backlog jumped from about $1.1 billion to roughly $5.6 billion on the 15-year ESCAPE contract, which includes US$1.5 billion in milestone payments, and a five-year Northwestel deal. Telesat also expanded its firm MDA order from 156 to 225 satellites without delaying the schedule. Management raised its public Lightspeed revenue and EBITDA forecast and said backlog should be meaningfully higher by the end of 2027. Several things would validate that confidence:
- new contract additions, even modest ones;
- progress on the MEO UHF/X-band opportunity or space relay work;
- a reaffirmed service entry around the end of the first quarter of 2028;
- the 2026 investment budget, already lifted to C$1.3 to 1.5 billion, holding there.
Another schedule slip or a further spending increase would weaken the narrative, since service entry has already moved once from late 2027. Updates on the $189 million US C-band incentive payment would also matter for liquidity.
The market has turned skeptical despite the upbeat call. Shares have dropped about 26% since the last report, trailing the S&P 500 by roughly 24 percentage points. Sentiment has swung from essentially neutral to clearly bearish. At $42.55, the stock sits right on its 200-day moving average and in the lower third of its post-earnings range of $38.10 to $60.24. That positioning suggests investors are pricing balance-sheet risk rather than celebrating backlog. Management denied a Chapter 11 question raised by a July court filing and is pursuing a consensual refinancing, but the uncertainty clearly lingers.
Ultimately, the quarter will be judged on refinancing. Strong Lightspeed momentum cannot fully reassure investors while a large maturity looms over the GEO silo. A concrete path to resolving the December debt, paired with stable GEO cash flow and no new Lightspeed delays, would let the backlog story reassert itself. Silence or vague progress on the debt would likely keep the discount firmly in place, however good the satellite pipeline looks.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 5 hours | |
| Oct-23 | |
| Oct-14 | |
| Oct-09 | |
| Sep-17 | |
| Sep-15 | |
| Sep-09 | |
| Sep-09 | |
| Sep-02 | |
| Sep-01 | |
| Aug-14 | |
| Aug-13 | |
| Aug-04 | |
| Jul-31 | |
| Jul-27 |
